
This article contains 4 figures and 12 tables.
Figures
Tables
| Database | Number of Residence Households* | Number of Persons | ||
|---|---|---|---|---|
| Unweighted | Weighted | Unweighted | Weighted | |
| EUROMOD/SILC input (LU-Resident population) | 3,833 | 252,336 | 10,493 | 574,184 |
| EUROMOD/HFCS-R input (LU-Resident population) | 1,616 | 226,378 | 4,333 | 535,897 |
| EUROMOD/HFCS-XB input (“Active” Cross-border households) | 2,362 | 147,380 | 7,341 | 418,997 |
All persons living in the same dwelling, not to be confused with the “residents” who involve inhabitants of Luxembourg.
| Data and EUROMOD platforms | SILC | HFCS-R | HFCS-XB (Active households & LU-incomes only) | ||
|---|---|---|---|---|---|
| Population covered by the survey (see Table 1), in persons | 574,184 | 535,897 | 418,997 | ||
| Taxable Income, before Tax allowances, in millions € / year (from tinty_s in HFCS-R, or tinty_lu_s for Active XB households) | 20,808 | 20,041 | 7,947 | ||
| … out of additional amount from XBs not covered by the survey (for subsequent macro adjustment, see Section 2.4) | 1,109 | ||||
| Public Revenue (in millions € / year) | |||||
| Social contributions | [I]* | [II] | [III] | ||
| 3,914 | 3,714 | 2,030 | |||
| whose | Employee | 1,820 | 1,693 | 945 | |
| Self-employed | 178 | 221 | 27 | ||
| Others (Long term care from Social assistance) | 3 | 3 | 0 | ||
| Employers | 1,710 | 1,667 | 1,059 | ||
| Credited (Replacement income, Social assistance, Pensions) | 202 | 130 | 0 | ||
| … out of additional amount from XBs not covered by the survey (for macro adjustment) | 62 | ||||
| Personal Income Tax | [VII] | [VIII] | |||
| 3,289 | 3,439 | 824 | |||
| Implicit Tax Rate on Tax Base (tinty_s – tinta_s, or LU versions if XBs), before Tax Credits | 20.9% | 14.4% | |||
| Global Tax Rate (after Tax Allowances & Credits) = Income Tax / Taxable Income, on average | 17.2% | 10.4% | |||
| … out of additional amount from XBs not covered by the survey (for macro adjustment) | 115 | ||||
| ⇒ Total Public Revenue (before macro adjustment) | 7,203 | 7,153 | 2,855 | ||
| Inequalities | If All Incomes | ||||
| Gini | |||||
| Relative = Abs / (2*Avg) | 0.2524 | 0.2993 | 0.1940 | ||
| Absolute (in € / month) | 1,701 | 2,103 | 1,088 | ||
| Average (in € / month) | 3,371 | 3,513 | 2,804 | ||
| Poverty | |||||
| Line (in € / month) | 1,790 | 1,770 | 1,564 | ||
| Rate | 11% | 13% | 2% | ||
| by Type of Residence Household: | |||||
| Single (<65) | 14% | 16% | 1% | ||
| Single (65+) | 8% | 9% | 2% | ||
| Single with dependent(s) | 31% | 18% | 0% | ||
| Couple - 0 dep | 6% | 5% | 2% | ||
| Couple - 1-2 dep | 11% | 18% | 2% | ||
| Couple - 3+ dep | 14% | 21% | 2% | ||
| "Well-being", as equivalized income (all in € / month), on average | If All Incomes | ||||
| All | 3,371 | 3,513 | 2,804 | ||
| 1st Decile | 1,574 | 1,472 | 1,635 | ||
| by Type of Residence Household: | |||||
| Single (<65) | 3,308 | 3,249 | 2,828 | ||
| Single (65+) | 3,215 | 3,440 | 2,878 | ||
| Single with dependent(s) | 2,473 | 2,661 | 2,530 | ||
| Couple - 0 dep | 3,922 | 4,150 | 3,194 | ||
| Couple - 1-2 dep | 3,117 | 3,292 | 2,768 | ||
| Couple - 3+ dep | 2,673 | 2,826 | 2,353 | ||
The references [I], [II], ... refer to Table B1 and Table B2 (Appendix B)
| Component (EUROMOD variable) | Meaning | HFCS-R | HFCS-XB† | ||||
|---|---|---|---|---|---|---|---|
| All incomes | LU-income | ||||||
| Avg ‡ | % of total | Avg ‡ | % of total | Avg ‡ | % of total | ||
| tinty_IT_s | Taxable income, by fiscal household § | 5,392 | 4,537 | 3,492 | |||
| tinta_IT_s | Tax allowances, by fiscal household § | ||||||
| tinty_s | Taxable income, by person | 3,116 | 100% | 2,054 | 100% | 1,581 | 100% |
| bsacm_s | Social assistance | 58 | 1.9% | 22 | 1.1% | 0 | 0.0% |
| il_repl | Replacement income | 10 | 0.3% | 0 | 0.0% | 0 | 0.0% |
| il_taxpen | Taxable pensions | 626 | 20.1% | 19 | 0.9% | 0 | 0.0% |
| yem | Employee gross income | 2,047 | 65.7% | 1,894 | 92.3% | 1,544 | 97.7% |
| yiy | Interest, dividends, profit from capital investments in unincorporated business | 16 | 0.5% | 18 | 0.9% | 14 | 0.9% |
| ypp | Pension from private pension plans | 43 | 1.4% | 0 | 0.0% | 0 | 0.0% |
| ypr | Income from property | 128 | 4.1% | 79 | 3.8% | 0 | 0.0% |
| ypt | Regular inter-household cash transfers received | 16 | 0.5% | 0 | 0.0% | 0 | 0.0% |
| yse | Gross income from self-employment | 172 | 5.5% | 22 | 1.1% | 22 | 1.4% |
Mean over all 5 imputations (see Section 2.1)
Averages for “All incomes” and “LU-Income” are considering the whole surveyed population
Mean = (weighted) total / number of persons or fiscal households in 2017
A fiscal household is gathering persons considered as to be taxed jointly on income, taking into account the relevant fiscal rules
| Proportions, in % of Fiscal Households | ||
|---|---|---|
| Class of Tax | HFCS-R | HFCS-XB (Active Households) |
| 0 | 17% | 9% |
| 1 | 47% | 38% |
| 2 | 37% | 54% |
Mean over all 5 imputations (Section 2.1)
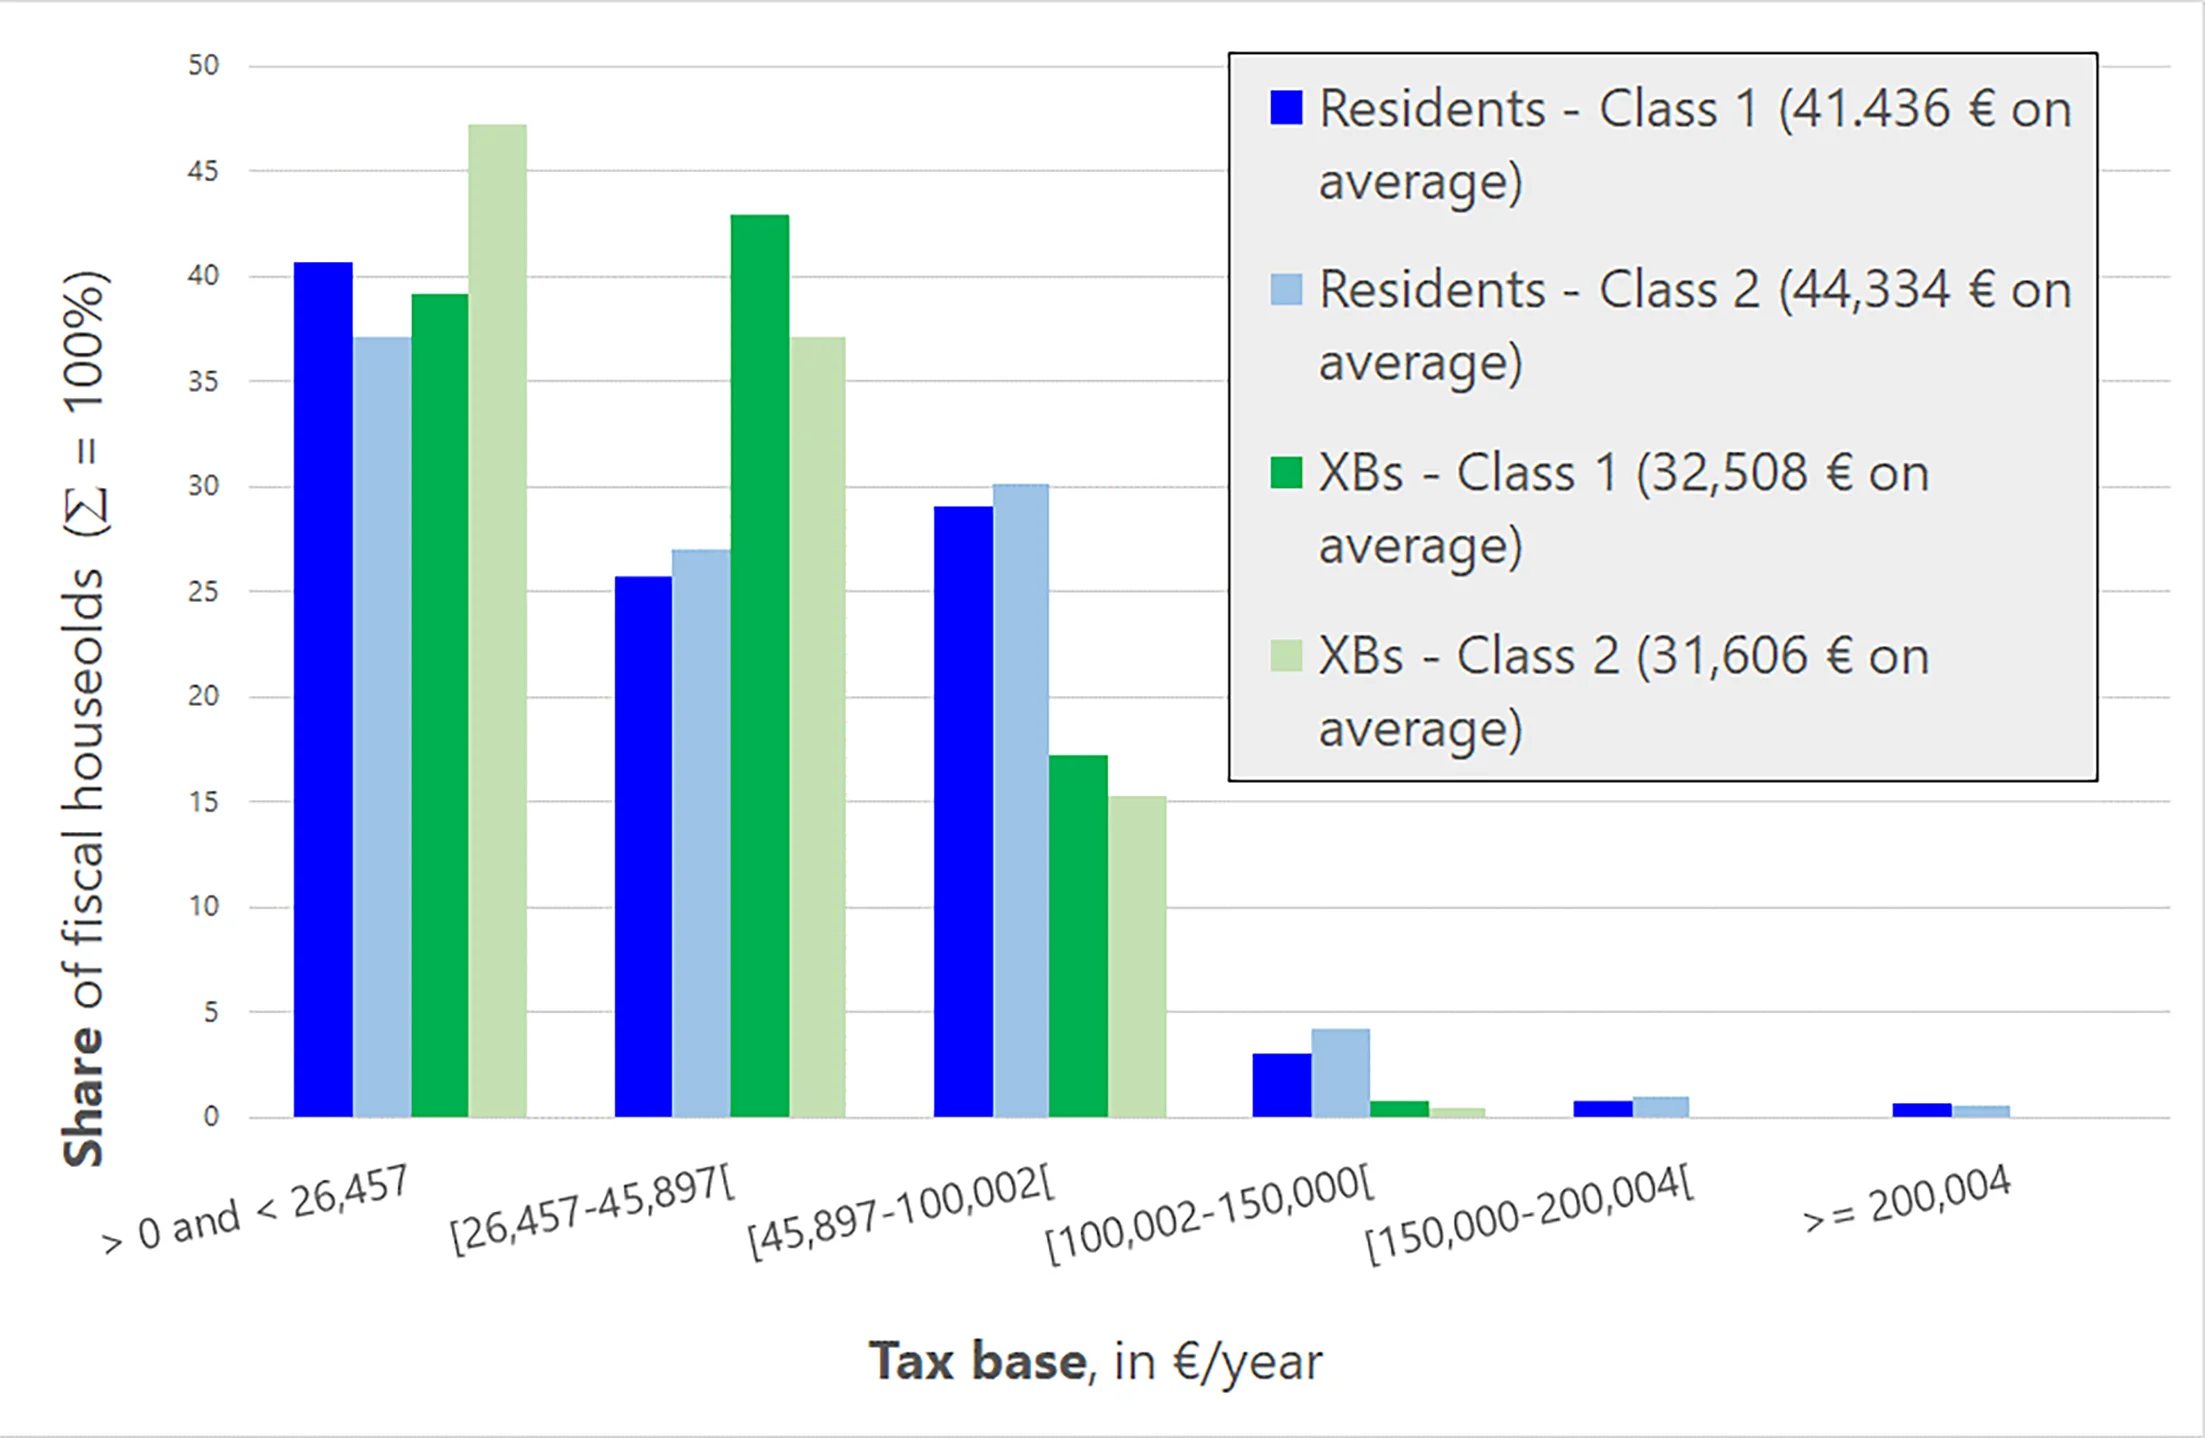
| Part [A] – RESIDENTS) Fiscal Bracket (in €) | Share of Fiscal Households within the bracket, in p.p. (see Figure 4) [a] | Percent of Fiscal Households impacted by that bracket * [b] = [b>] + [a] | Mean Tax Base for that bracket [c] | Lower limit for that fiscal bracket (€, yearly) [d] | Income from tax payers belonging to that bracket, above the Minimum level of Fiscal Bracket [e] = [c] - [d] | Σ of Tax Bases impacted by that Bracket, for 100 fiscal households (€, yearly) [f] = [a] * [e] + [b>] * ([d>] - [d]) | Approximate Marginal Tax Rate (+/- mean tax rate over the bracket †) (2017 STD system) [g] | Income Tax from that Tax Bracket, for 100 fiscal households (€, yearly) [h] = [f] * [g] | % of income Tax from that Tax Bracket [i] = [h] / [k] and Avg % tax below =[k] / [j] |
|---|---|---|---|---|---|---|---|---|---|
| > 0 and < 26,457 | 37.1 | 100 | 17,976 | 0 | 17,976 | 2,330,900 | 6.2% | 144,944 | 17% |
| [26,457-45,897[ | 27 | 62.9 | 35,848 | 26,457 | 9,391 | 950,689 | 28.6% | 271,611 | 31% |
| [45,897-100,002[ | 30.1 | 35.8 | 63,520 | 45,897 | 17,623 | 840,398 | 39.0% | 327,755 | 38% |
| [100,002-150,000[ | 4.2 | 5.7 | 119,684 | 100,002 | 19,682 | 157,891 | 40.0% | 63,156 | 7% |
| [150,000-200,004[ | 1 | 1.5 | 167,270 | 150,000 | 17,270 | 43,312 | 41.0% | 17,758 | 2% |
| ≥ 200,004 | 0.5 | 0.5 | 4,05,658 | 200,004 | 205,654 | 110,230 | 42.0% | 46,297 | 5% |
| Total Tax Bases [j], for 100 fiscal households ⇓ | Total Tax [k] | (Avg % Tax: 19.7%)‡ ‡ | |||||||
| 4,433,421 | 871,521 | ||||||||
[b>]” refers to the value of [b] for the fiscal bracket above the present one (e.g. [150,000-200,004[, as for bracket [100,002-150,000[)
Approximate weighted mean tax rate over the Fiscal Bracket: for example in Part [A], “28.6%” = ( ([a]/100*28%) + ([b]-[a])/100*((20%+38%)/2) ) / ( [b]/100 ), where 28% is the tax rate at [c]-income and 20%/38% are the tax rates at the extremes of this fiscal bracket
20.9% on average, all fiscal classes considered for HFCS-R in 2017, including a 7% (mainly) or 9% Tax for Unemployment fund ⇒ about 19.5% without it
13.8% on average, all fiscal classes considered for HFCS-XB in 2017, including a 7% (mainly) or 9% Tax for Unemployment fund ⇒ about 12.9% without it
| Part [A] – RESIDENTS) Fiscal Bracket (in €) | Share of Fiscal Households within the bracket, in p.p. [a] | Mean Tax Base for that Bracket [b] | Lower limit Fiscal bracket (€, yearly) [c] | Approximate Marginal Tax Rate if Income reaching the Upper limit of the Tax Bracket * (2017 STD system) [d] | Tax receipt per Fiscal Household if Tax Base = lower limit of this Tax Bracket (€/year) † [e] = [e<] + [d<] * ([c] - [c<]) | Tax receipt per Fiscal Household whose Tax Base lays within this Tax Bracket (€/year) [f] = [e] + [d] * ([b] - [c]) | Tax receipt for ALL Fiscal Households whose Tax Base lays within this Tax Bracket, if considering 100 fiscal households on the whole (€/year) [g] = [a] * [f] | % of Income Taxes from Fiscal Households belonging to this Tax Bracket [i] = [g] / [h] | Intensity of Contribution to Personal Income Taxes [j] = [g] / ([a] * [b]) |
|---|---|---|---|---|---|---|---|---|---|
| > 0 and < 26,457 | 37.1 | 17,976 | 0 | 7.5% | 0 | 738 | 27,400 | 3% | 0.04 |
| [26,457-45,897[ | 27 | 35,848 | 26,457 | 29.0% | 1,975 | 4,605 | 124,534 | 14% | 0.13 |
| [45,897-100,002[ | 30.1 | 63,520 | 45,897 | 39.0% | 7,613 | 14,486 | 436,218 | 50% | 0.23 |
| [100,002-150,000[ | 4.2 | 119,684 | 100,002 | 40.0% | 28,714 | 36,586 | 154,833 | 18% | 0.31 |
| [150,000-200,004[ | 1 | 167,270 | 150,000 | 41.0% | 48,713 | 55,793 | 53,338 | 6% | 0.33 |
| ≥ 200,004 | 0.5 | 405,658 | 200,004 | 42.0% | 69,214 | 155,589 | 83,396 | 9% | 0.38 |
| Total Tax Bases [k], for 100 fiscal households ⇓ | Total Tax [h] | (Avg % Tax: 19.8%) ‡ | |||||||
| 4,433,421 | 879,719 | ||||||||
| Part [B] – XBs | [a] | [b] | [c] | [d] | [e] = [e<] + [d<] * ([c] - [c<]) | [f] = [e] + [d] * ([b] - [c]) | [g] = [a] * [f] | [i] = [g] / [h] | [j] = [g] / ([a] * [b]) |
| > 0 and < 26,457 | 47.2 | 19,199 | 0 | 7.5% | 0 | 952 | 44,964 | 11% | 0.05 |
| [26,457-45,897[ | 37.1 | 34,668 | 26,457 | 29.0% | 1,975 | 4,274 | 158,632 | 38% | 0.12 |
| [45,897-100,002[ | 15.3 | 60,455 | 45,897 | 39.0% | 7,613 | 13,290 | 202,832 | 48% | 0.22 |
| [100,002-150,000[ | 0.4 | 111,375 | 100,002 | 40.0% | 28,714 | 33,263 | 13,305 | 3% | 0.3 |
| [150,000-200,004[ | 0 | 150,000 | 41.0% | 48,713 | |||||
| ≥ 200,004 | 0 | 200,004 | 42.0% | 69,214 | |||||
| Total Tax Bases [k], for 100 fiscal households ⇓ | Total Tax [h] | (Avg % Tax: 13.3%) § | |||||||
| 3,160,620 | 419,733 | ||||||||
Approximate weighted mean tax rate over the Fiscal Bracket: for example, “29.0%” = (20% + 38%) / 2
“[c<]” refers to the value of [c] for the Fiscal Bracket below the present one (e.g. [100,002-150,000[, as for bracket [150,000-200,004[)
20.9% on average, all Fiscal Classes considered for HFCS-R in 2017, including a 7% (mainly) or 9% Tax for Unemployment fund ⇒ about 19.5% without it
13.8% on average all Fiscal Classes included for HFCS-R in 2017, including a 7% (mainly) or 9% Tax for Unemployment fund ⇒ about 12.9% without it
| Fiscal Bracket (in €) | Share of Fiscal Households within the bracket, in p.p. [a] | Mean Tax Base for that Bracket [b] | Lower limit Fiscal bracket (€, yearly) [c] | Approximate Marginal Tax Rate if Income reaching the Upper limit of the Tax Bracket * (2017 STD system) [d] | Tax receipt per Fiscal Household if Tax Base = lower limit of this Tax Bracket (€/year) † [e] = [e<] + [d] * ([c] - [c<]) | Tax receipt per Fiscal Household whose Tax Base lays within this Tax Bracket (€/year) [f] = [e] + [d] * ([b] - [c]) | Tax receipt for ALL Fiscal Households whose Tax Base lays within this Tax Bracket, if considering 100 fiscal households on total (€/year) [g] = [a] * [f] | % of Income Taxes from Fiscal Households belonging to this Tax Bracket [i] = [g] / [h] | Intensity of Contribution to Personal Income Taxes [j] = [g] / ([a] * [b]) |
|---|---|---|---|---|---|---|---|---|---|
| > 0 and < 26,457 | 37.1 | 17,976 | 0.00 | 7.5% | 0 | 738 | 27,400 | 3% | 0.04 |
| [26,457-45,897[ | 27.0 | 35,848 | 26,457 | 29.0% | 1,975 | 4,605 | 124,534 | 14% | 0.13 |
| [45,897-100,002[ | 30.1 | 63,520 | 45,897 | 40.0% | 7,613 | 14,662 | 441,525 | 49% | 0.23 |
| [100,002-150,000[ | 4.2 | 119,684 | 100,002 | 42.0% | 29,255 | 37,521 | 158,789 | 18% | 0.31 |
| [150,000-200,004[ | 1.0 | 167,270 | 150,000 | 44.0% | 50,254 | 57,852 | 55,307 | 6% | 0.35 |
| ≥ 200,004 | 0.5 | 405,658 | 200,004 | 46.0% | 72,255 | 166,856 | 89,435 | 10% | 0.41 |
| Total Tax Bases [j], for 100 fiscal households ⇓ | Total Tax [k] | (Avg % Tax: 20.2%) ‡ | |||||||
| 4,433,421 | 896,990 | ||||||||
Approximate weighted mean tax rate over the Fiscal Bracket: for example, “29.0%” = (20% + 38%) / 2
“[e<]” refers to the value of [c] for the Fiscal Bracket below the present one (e.g. [100,002-150,000[, as for bracket [150,000-200,004[)
21.4% on average, all Fiscal Classes considered for HFCS-R in 2017, including a 7% (mainly) or 9% Tax for Unemployment fund ⇒ about 20.0% without it
| EUROMOD models (out of MACRO adjustment) | |||||
|---|---|---|---|---|---|
| EUROMOD /HFCS-R | EUROMOD/ HFCS-XB (Active households) | ||||
| STD | Alternative policy | STD | Alternative policy (LU-Incomes only) | ||
| Population covered by the surveys | 535,897 | 418,997 | |||
| Taxable Income, before Tax allowances (for XBs, LU-incomes only) in millions € / year [a + b] | 20,041 | 9,056 | |||
| a] Covered by the surveys (for XBs, LU-incomes only) | 20,041 | 7,947 | |||
| b] Additional amount not covered by the XB survey | 1,109 | ||||
| Total Public Revenue (in millions € / year) | |||||
| Social contributions [c + d] | 3,714 | 3,714 | 2,092 | 2,092 | |
| c] Resulting from the microsimulation (based on HFCS surveys) | 3,714 | 3,714 | 2,030 | 2,030 | |
| d] Contribution for XBs not covered by the HFCS-XB survey (evaluated based on b] and while hypothesizing that those persons are all retired) | 62 | 62 | |||
| Personal Income Tax [e + f] | 3,439 | 3,517 | 939 | 947 | |
| e] Resulting from the microsimulation (based on HFCS surveys) | 3,439 | 3,517 | 824 | 832 | |
| f] Additional tax from XBs not covered by the HFCS-XB survey (evaluated based on b] while hypothesizing that the tax rate applicable is the one determined for the covered households after tax credits [*]) | 115 | ||||
| and Tax Rates | |||||
| Global Tax Rate on Tax Base, before Tax Credits, on average and through the HFCS surveys | 20.9% | 21.4% | 14.4% | 14.5% | |
| [*] Global Tax Rate, after Tax Credits, through the HFCS surveys [e/a] | 17.2% | 17.5% | 10.4% | 10.5% | |
| ⇒ Total Revenue | Through the surveys, LU-incomes only for XBs [c + e] (in millions € / year) | 7,153 | 7,231 | 2,855 | 2,862 |
| With macro adj., for XBs [c + d + e + f] | 3,032 | 3,039 | |||
| General (Residents + XBs, including macro adjustment) (in millions € / year) | STD: 10,185 | Alternative: 10,270 | |||
| Inequalities | |||||
| Gini | All Incomes | ||||
| Relative = Absolute gap / (2*Average) | 0.2993 | 0.2966 | 0.1940 | 0.1934 | |
| Absolute gap, on average (in € / month) | 2,103 | 2,074 | 1,088 | 1,084 | |
| Average well-being (in € / month) | 3,513 | 3,496 | 2,804 | 2,802 | |
| Poverty | All Incomes | ||||
| Line (in € / month) | 1,770 | 1,768 | 1,564 | 1,564 | |
| Rate | 13% | 13% | 2% | 2% | |
| "Well-being", as equivalized income (all in € / month), on average | All Incomes | ||||
| All | 3,513 | 3,496 | 2,804 | 2,802 | |
| 1st Decile | 1,472 | 1,472 | 1,635 | 1,635 | |
| 9th Decile | 4,943 | 4,923 | 3,820 | 3,816 | |
| EUROMOD Variable | Imputation | Origin (in % of total) | Remarks | |||
|---|---|---|---|---|---|---|
| Name | Content | in % of (yem + yse) at household level | if another base | From LU | From ABROAD | |
| poa | Old-age Pension | 20.3% if 1 pensioner in the household, 42.5% for each pensioner if more than 1, and 0.2% if no pensioner | 0 | 100% | 0.2% if no pensioner preferred to “0”, in conformity to HFCS-R | |
| psu | Survival Pension | 0 | 0 | 0 | Incorporated in the imputation of “poa” | |
| xmp | Maintenance payment | 0 | 0 | 0 | Lower amounts | |
| yiy | Investment income | 1.9% | In conformity with proportions in HXG0100x (total gross household income, separated based on its origins, LU versus other countries altogether) | May come from LU or other capital investments | ||
| yot | Other income by children < 16 | 1.3% | 0 | 100% | Mainly from children, hence from “home” | |
| ypp | Private pension | 0 | 0 | 0 | Lower amounts (in LU !) | |
| ypr | Property income | 4.1% | 0 | 100% | “Properties” supposed from ABROAD | |
| C] SOCIAL CONTRIBUTIONS | |||||
| Reference | Component | Computation information | Value (in Millions €/year or %) | ||
| [I] | From model platforms (cf. Table 2) | SILC (Social contributions) | 3,914 | ||
| [II] | HFCS-R (Social contributions) | 3,714 | |||
| ⇒ HFCS-R [II], in % of SILC [I] | = [II] / [I] | 94.9% | |||
| [III] | HFCS-XB (Social contributions for Active households & LU-incomes only) | 2,030 | |||
| [%1] | ⇒ HFCS-XB [III[, in % of HFCS-R [II] | = [III] / [II] | 54.7% | ||
| [SC/HFCS+] == [IV] | ⇒ C.1] Social contributions for populations covered through HFCS-R & XB surveys | = [II] + [III] | 5,745 | ||
| [SC/SILC+] | Alternatively, Residents/SILC + XBs in % of SILC | = [I] * (1 + [%1]) | 6,054 | ||
| ⇒ [SC/HFCS+], in % of [SC/SILC+] | 94.9% | ||||
| C.2] MACRO Correction for Social Contributions from gross income from XBs not covered by the HFCS/XB survey | |||||
| [V] | Additional gross LU-income from XBs not covered by the HFCS/XB survey, based on Pensions paid to XBs from Luxembourg in 2017 (considered as the LU-taxable income for that sub-population), whereas Pensions received by XBs covered by the HFCS survey are considered as from foreign origin only | 1,109 | |||
| [VI] | ⇒ Additional contribution for XBs not covered by HFCS surveys (considering 2.8% * 2 of contributions for Health In-Kind, as for pensioners) | = [V] * 5.6% | 62 | ||
| [%2] | ⇒ Total Social Contributions from XBs, in % of SC from RESIDENTS | = ([III] + [VI]) / [II] | 56.3% | ||
| [SC/HFCS++] | ⇒ C.3] TOTAL SOCIAL CONTRIBUTIONS, if considering All XBs, including those not covered by the HFCS/XB survey on top (based on HFCS) | = [IV] + [VI] = [II] + [III] + [VI] | 5,807 | ||
| Alternatively, if based on SILC, completed by HFCS data for XBs | = [I] * (1 + [%2]) | 6,120 | |||
| T] PERSONAL INCOME TAX (as for LU-Incomes, unless otherwise mentioned) | ||||
| Reference | Component | Computation information | Value (in Millions €/year or %) | |
| [VII] | From model platforms (cf. Table 2) | SILC (Personal Income Tax) | 3,289 | |
| [VIII] | HFCS-R (Personal Inc Tax) | 3,439 | ||
| ⇒ HFCS-R, in % of SILC | = [VIII] / [VII] | 105% | ||
| [IX] | HFCS-XB (Personal Income Tax for Active households & LU-incomes only) | 824 | ||
| [%3] | ⇒ HFCS-XB, in % of HFCS-R | = [IX] / [VIII] | 24% | |
| [TAX/HFCS+] | ⇒ T.1] Personal Income Taxes for populations covered through HFCS-R & XB surveys | = [VIII] + [IX] | 4,263 | |
| [TAX/SILC+] | Alternatively, Residents/SILC + XBs in % of SILC | = [VII] * (1 + [%3]) | 4,077 | |
| ⇒ [TAX/HFCS+] in % of [TAX/SILC+] | 104.6% | |||
| T.2] MACRO Correction for Personal Income Tax from gross income of XBs not covered by the HFCS/XB survey | ||||
| [X] | T.2.1] Total Taxable Income of HFCS-XBs (covered by the survey, LU-Incomes only), before Tax Allowances | = EUROMOD variable "tinty_lu_s" (on average) * 12 * HFCS-XBs Population in 2017 / 1,000,000 | 7,947 | |
| [XI] | Total Tax Allowances for XBs/HFCS (LU-incomes) | = EUROMOD variable "tinta_lu_s" (on average) * 12 * HFCS-XBs Population in 2017 / 1,000,000 | 1,627 | |
| [XII] | Income Tax for HFCS-XBs before Tax credits (LU-Incomes) | = "tin_lu_s" (/ year & for whole covered population) | 911 | |
| [XIII] | ⇒ Implicit Tax Rate on Tax Base for HFCS-XBs, before Tax Credits | = [XII] / ([X] - [XI]) | 14.4% | |
| [XIV] | Total Tax Credits for HFCS-XBs | = [XII] - [IX] | 87 | |
| [%4] | ⇒ HFCS-XBs' Global Tax on Taxable Income, after Tax Credits, LU-Incomes only | = [IX] / [X] | 10.4% | |
| T.2.2] Additional gross income from XBs not covered by the HFCS/XB survey, based on Pensions paid to XBs from Luxembourg in 2017 | [V] | 1,109 | ||
| [XV] | ⇒ Total Tax on Income for XB households not covered by the HFCS/XB survey, if Residents' average rate [%4] applied | = [V] * [%4] | 115 | |
| [XVI] | & Equivalent computation taking into account Tax Allowances and Tax Credits | = ([V] - [XI] * [V]/[X]) * [XIII] - ([XIV] * [V]/[X]) | 115 | |
| [%5] | ⇒ Total Income Tax from ALL XBs, in % of Tax from RESIDENTS | = ([IX] + [XV]) / [VIII] | 27.3% | |
| [TAX/HFCS++] | ⇒T.3] TOTAL TAXES, if considering All XBs, including those not covered by the HFCS/XB survey on top | = [TAX/HFCS+] + [XV] | 4,378 | |
| R] TOTAL PUBLIC REVENUE: SOCIAL CONTRIBTIONS and PERSONAL INCOME TAXES as for LU accounts (hence from LU Incomes) & including ALL Cross-border households (whatever active or not) & Residents | |||
|---|---|---|---|
| Reference | Component | Computational information | Value (in Millions €/year or %) |
| [TOT/ HFCS++] | Total Public Revenue from Residents/HFCS + ALL XBs, if through HFCS data and models | = [SC/HFCS++] + [TAX/HFCS++] | 10,185 |
| [TOT/ SILC++] | Alternatively, Residents/SILC + ALL Cross-Borders considered through an additional % (derived from HFCS) | = [I] * (1 + [%2]) + [VII] * (1+ [%5]) | 10,307 |
| ⇒ [TOT/HFCS++] in % of [TOT/SILC++] | 98.8% | ||