Dynamic microsimulation, Taxes and benefits

Research articles · Aug 20, 2025

Dynamic Simulation of Taxes and Welfare Benefits by Database Imputation

Justin van de Ven, Patryk Bronka, Matteo Richiardi

National Institute of Economic and Social Research, London, United Kingdom; University of Essex, UK, Colchester, United Kingdom

Volume 18(2) Summer 2025

Cite as: J. van de Ven, P. Bronka, M. Richiardi; 2025; Dynamic Simulation of Taxes and Welfare Benefits by Database Imputation; International Journal of Microsimulation; 18(2); 124–155. doi: 10.34196/ijm.00326

Abstract

This paper proposes a new method for describing a realistic tax-benefit system in a dynamic microsimulation model. The suggested approach draws upon existing third-party tax-benefit calculators and provides an alternative to integration of tax functions within a dynamic structure. It has the advantages of adapting to the degree of household sector detail described by a model and permits taxes and benefits to be imputed directly from commonly available micro-data sources. A practical application to a dynamic programming model designed to reflect the contemporary UK policy context indicates that the proposed method for projecting taxes and benefits implies a comparable computational burden and generates qualitatively comparable results to a detailed functional description of fiscal policy, while simplifying model development.

This article contains 6 figures and 2 tables.

Figures
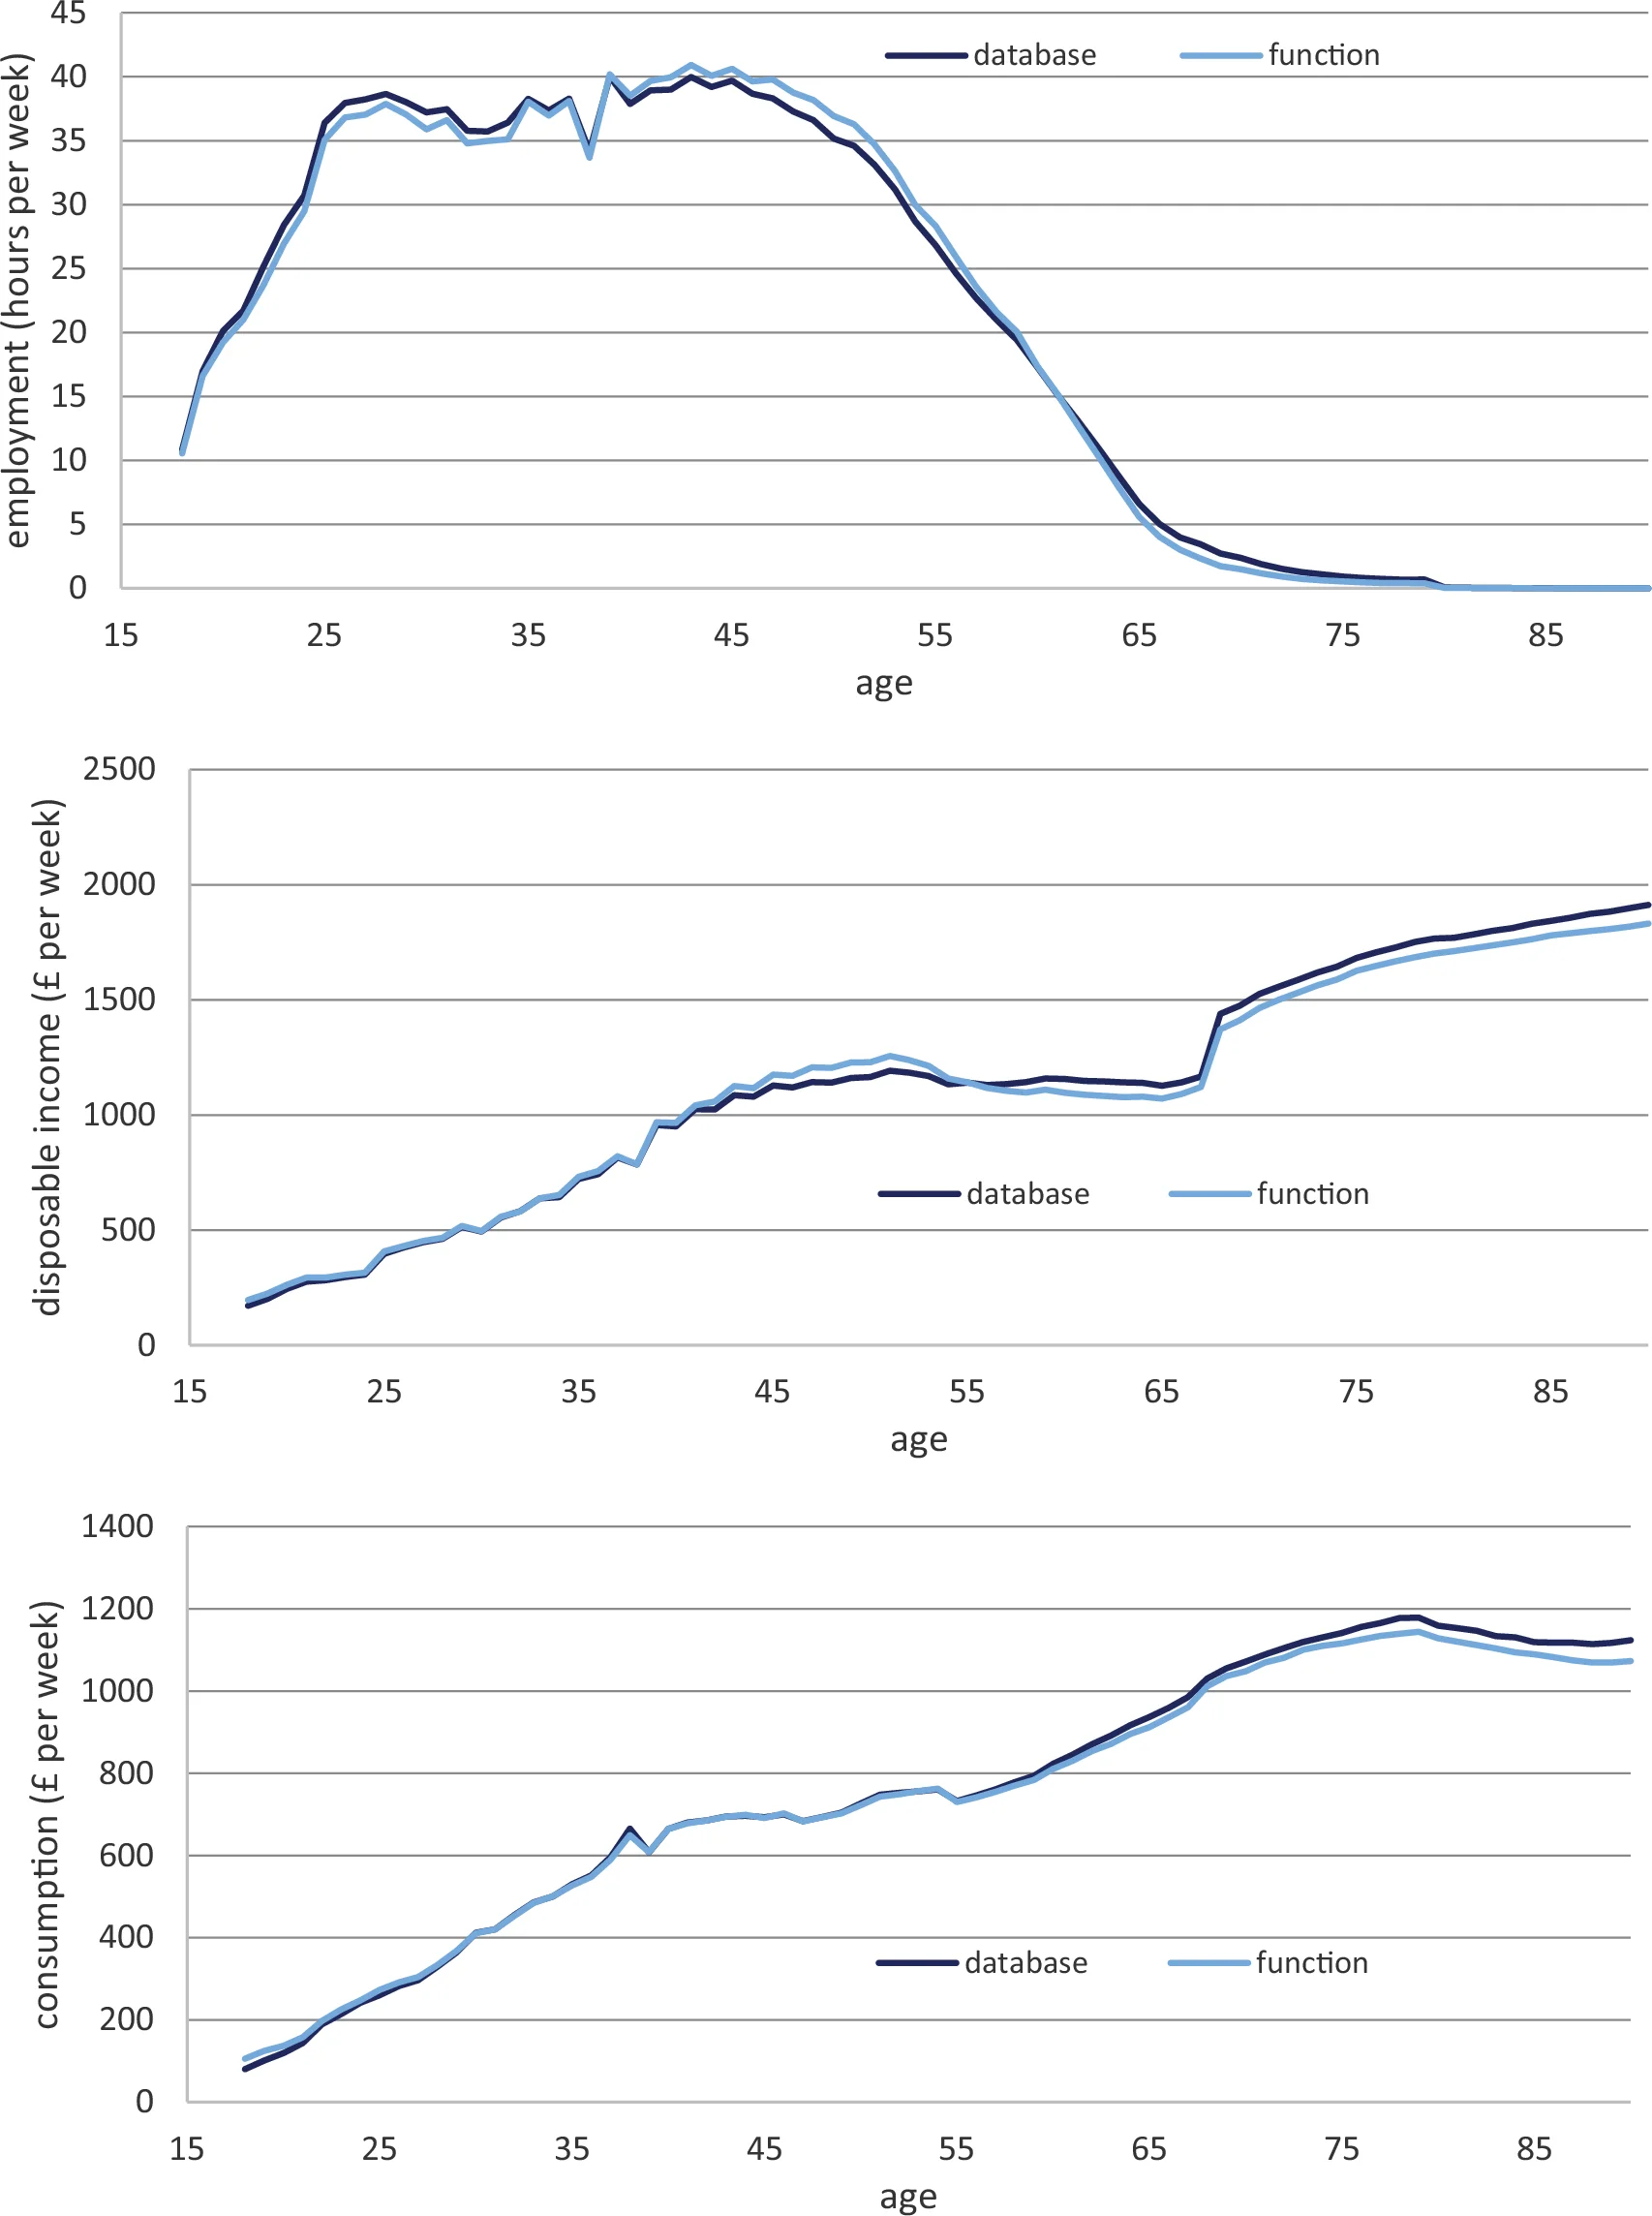
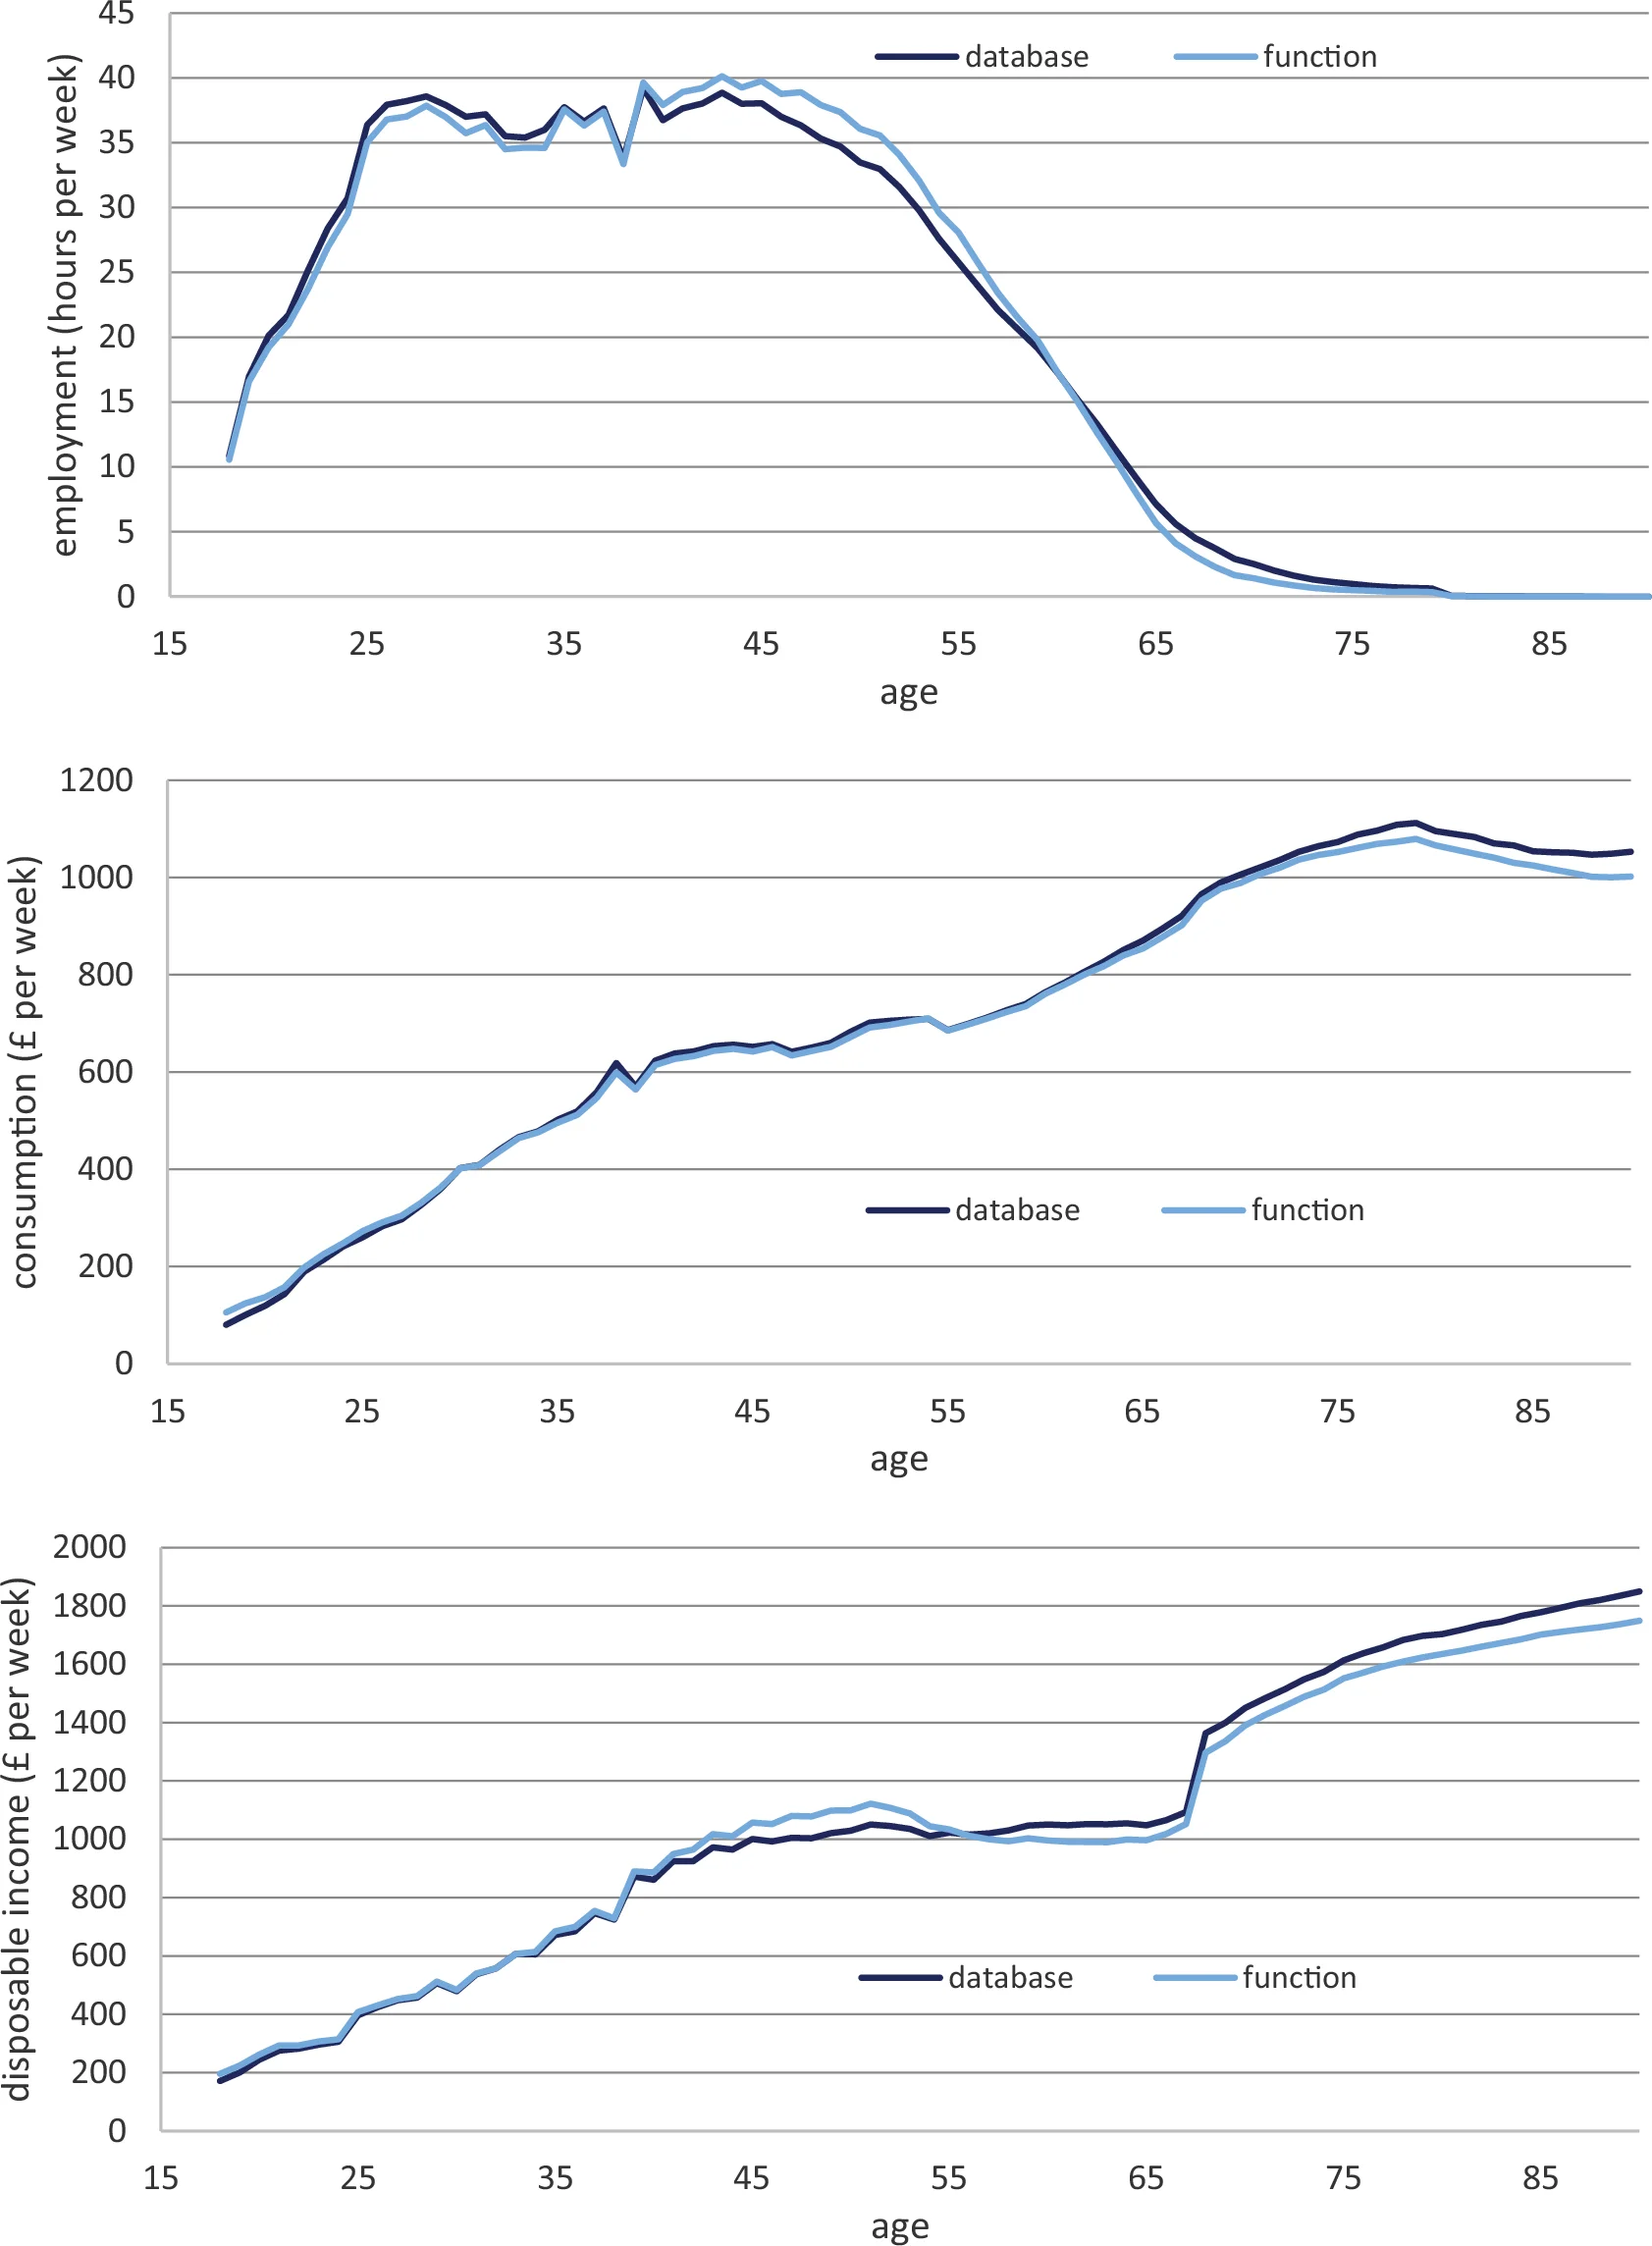
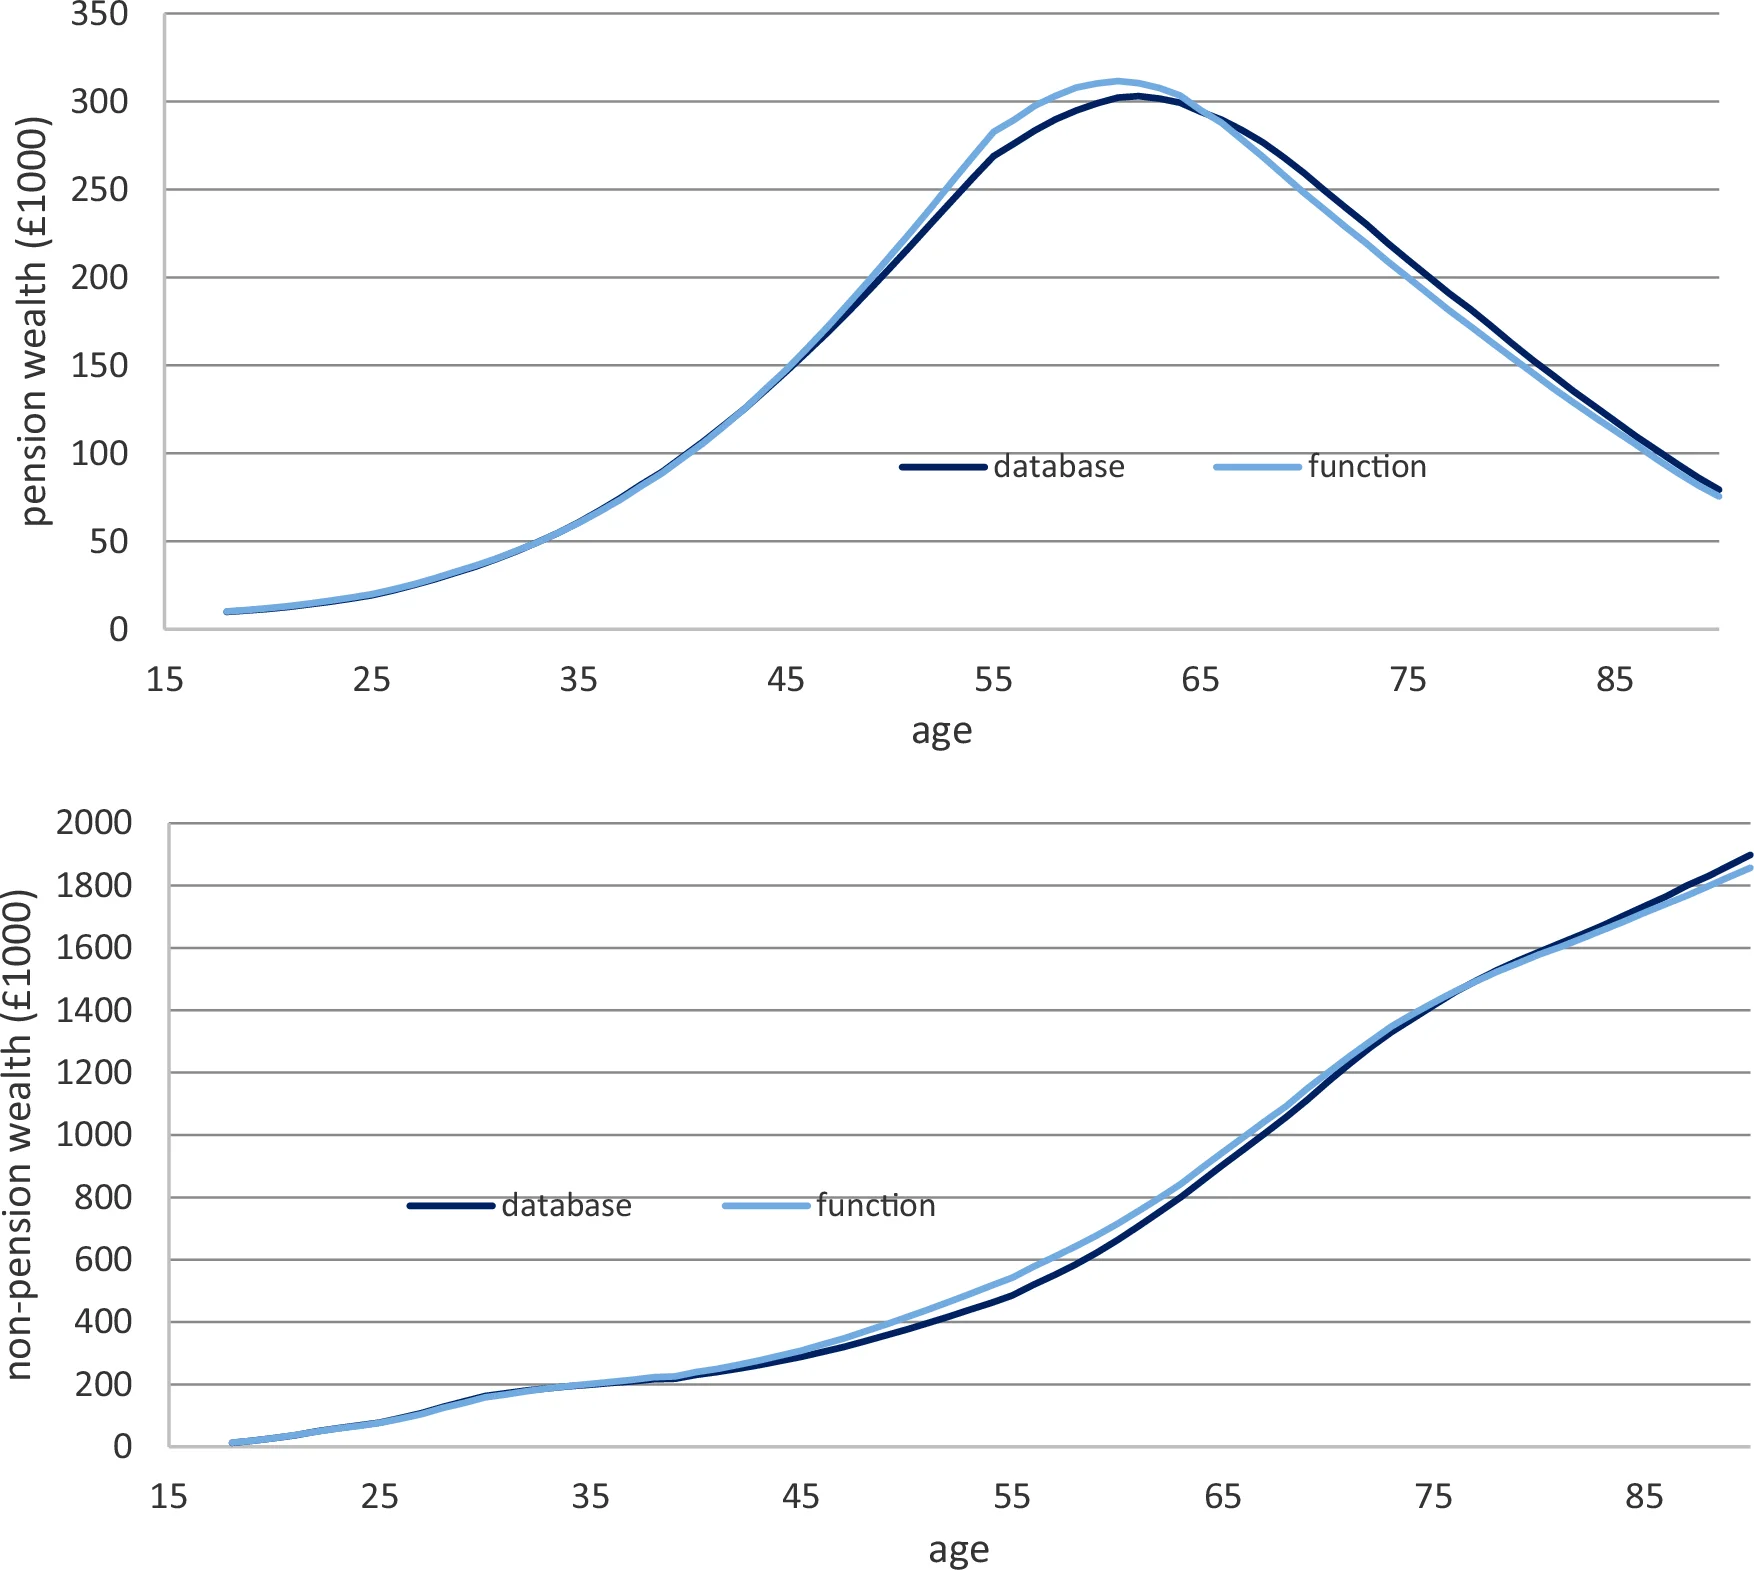
Figure 4.1. Selected age-specific simulated population averages projected under the base policy scenario for cohorts born between 1980 and 1989, by method of transfer payment imputation. Source: Authors’ calculations using simulated data Notes: Age specific population averages evaluated for population cohorts born between 1980 and 1989. All financial figures reported in 2017 prices. The two series reported in each panel are distinguished by the method used to impute tax and benefit payments. The “base policy scenario” refers to an assumed status-quo policy environment.
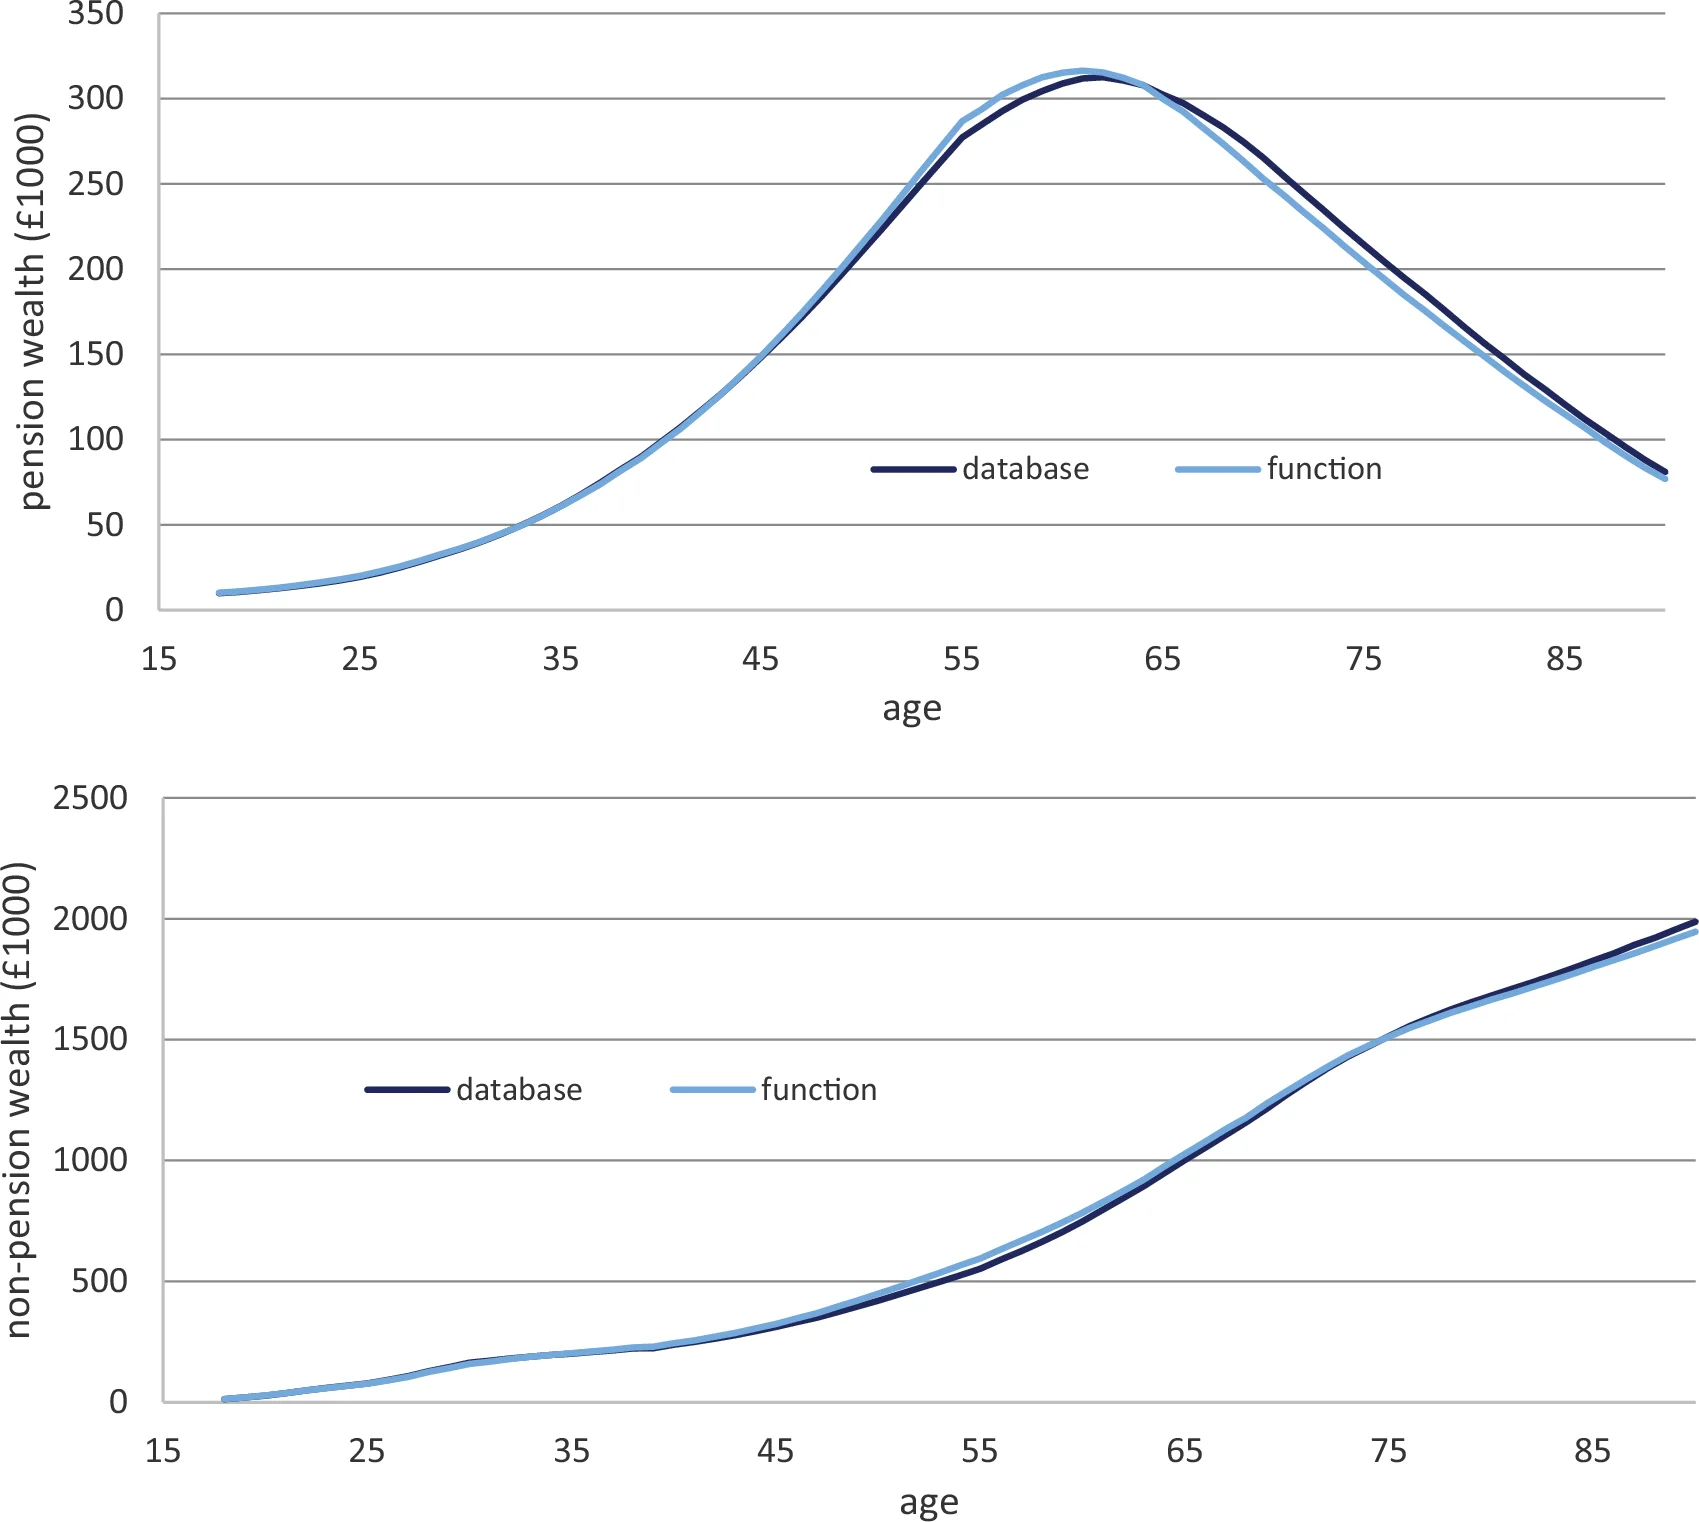
Figure 5.1. Selected age-specific simulated population averages projected under the base policy scenario for cohorts born between 1980 and 1989, by method of transfer payment imputation. Source: Authors’ calculations using simulated data. Notes: See notes to Figure 4.1.
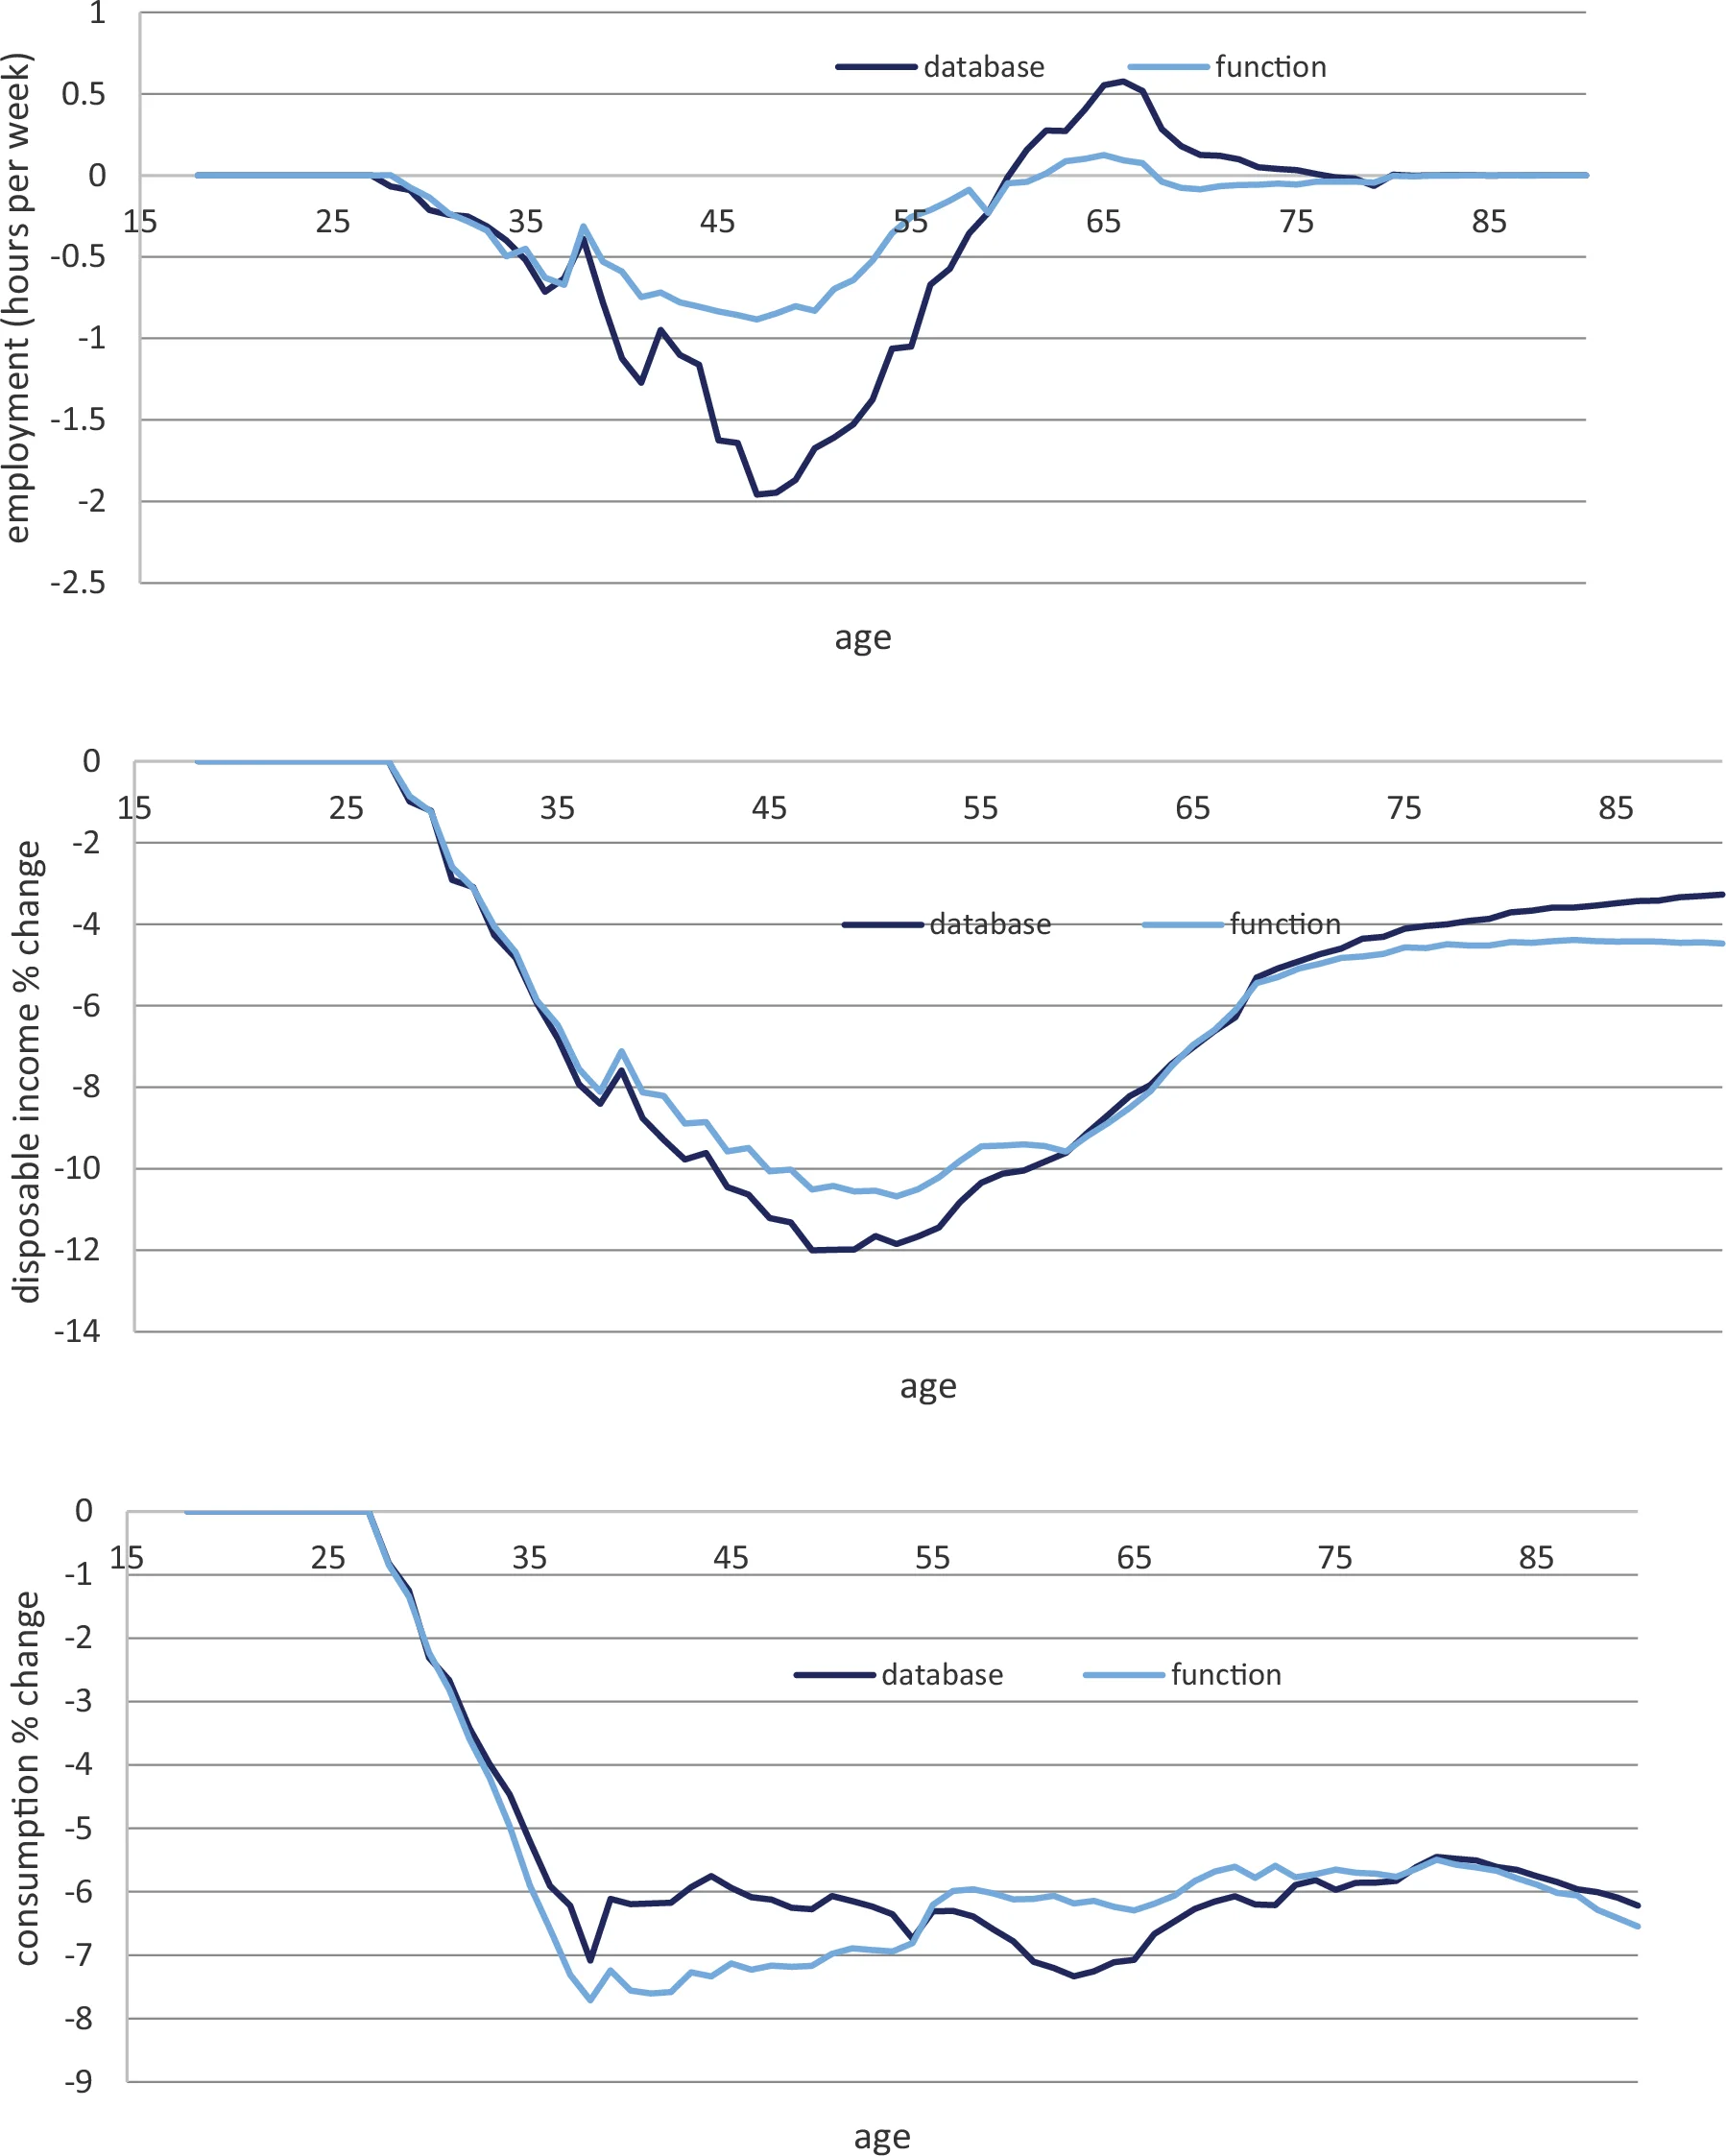
Figure 6.1. Selected age-specific population average effects of a 10-percentage point increase in income tax rates on cohorts born between 1980 and 1989, by method of transfer payment imputation. Source: Authors’ calculations using simulated data Notes: Age specific population averages for population cohorts born between 1980 and 1989 projected under the policy reform, less the same statistics projected under the base simulation scenario. All financial figures reported as percentage changes relative to the base simulation scenario. The two series reported in each panel are distinguished by the method used to impute tax and benefit payments.
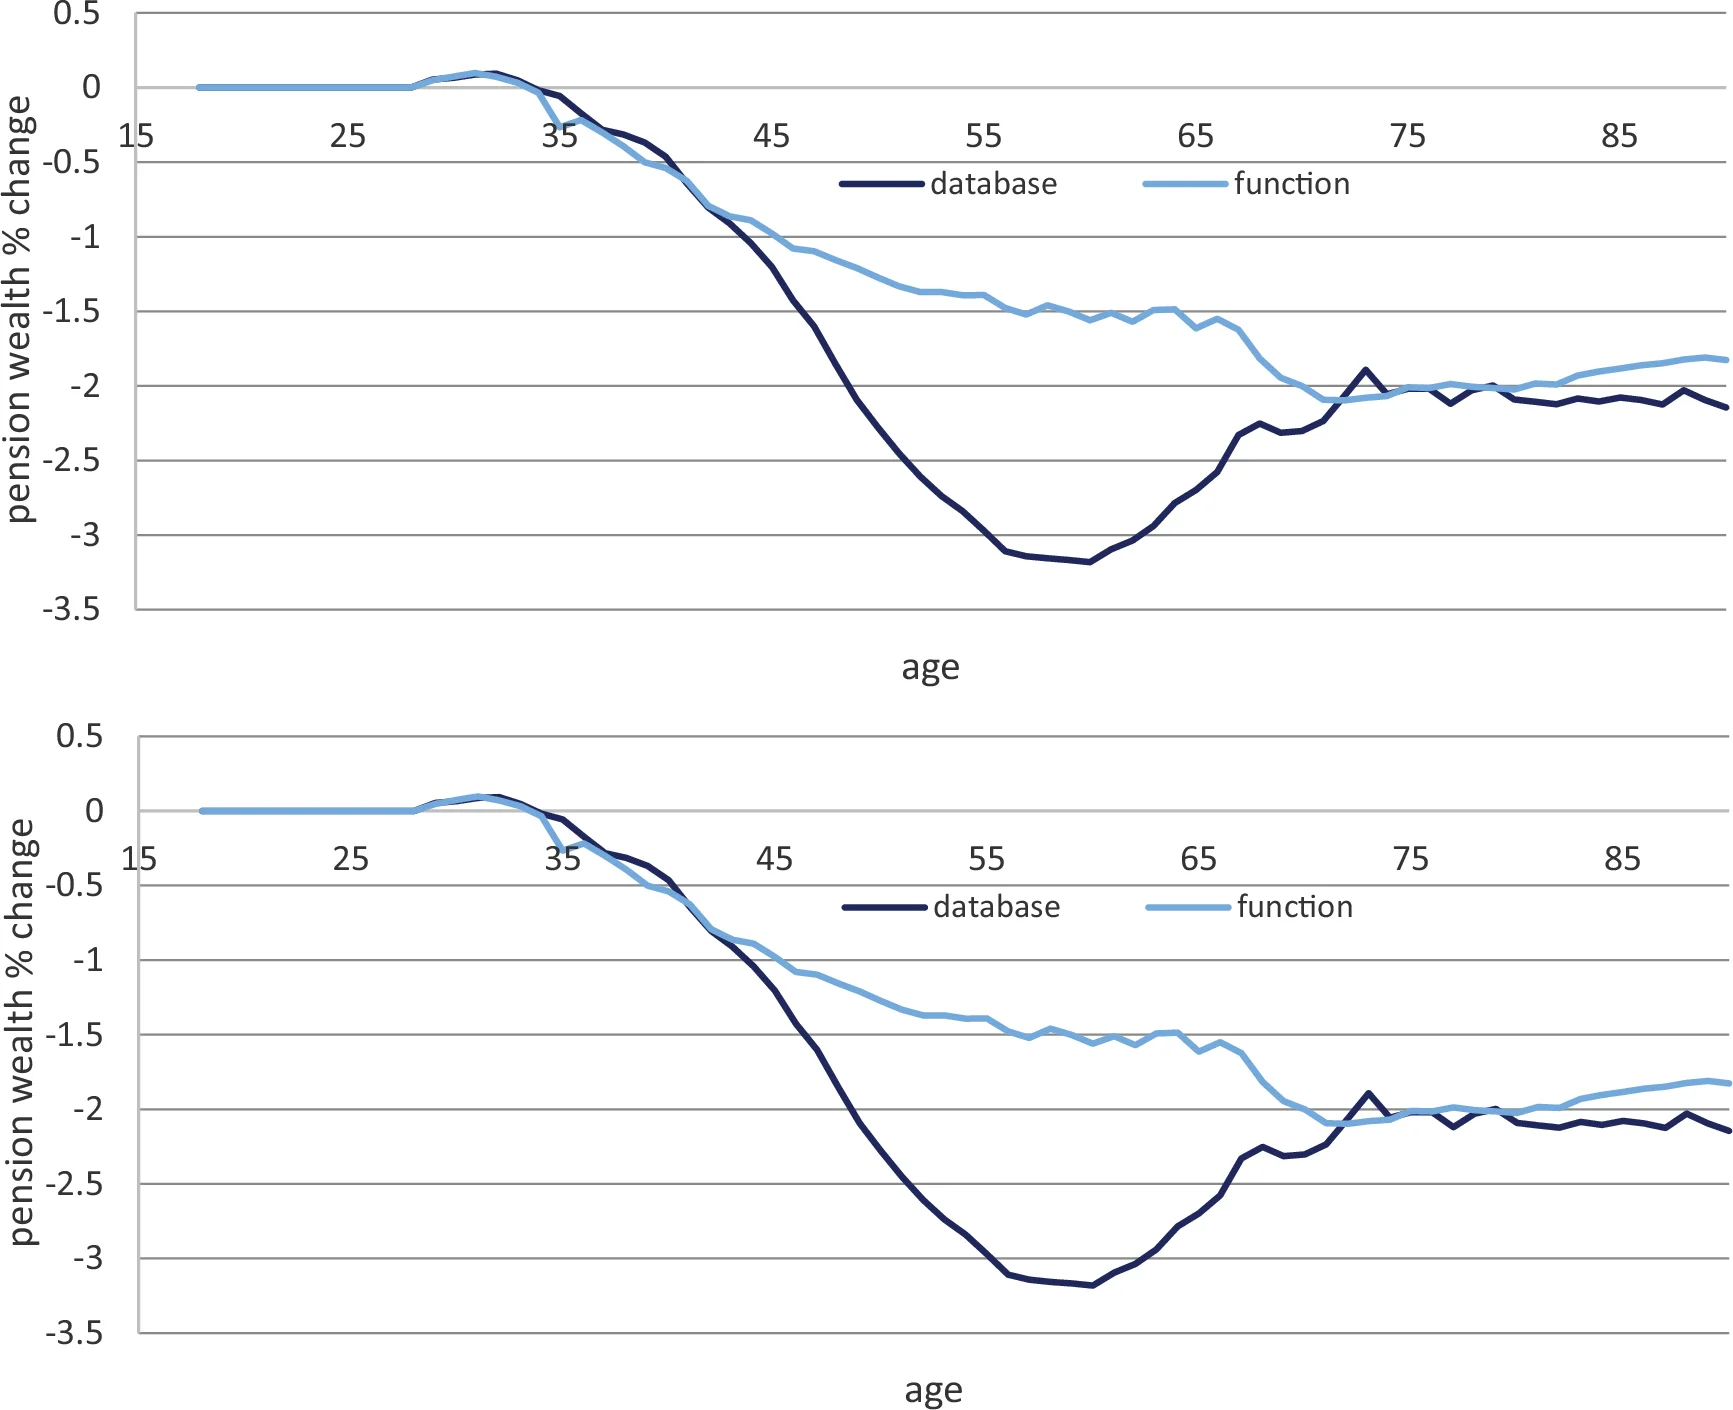
Figure 7.1. Selected age-specific population average effects of a 10-percentage point increase in income tax rates on cohorts born between 1980 and 1989, by method of transfer payment imputation. Source: Authors’ calculations using simulated data Notes: See notes to Figure 4.1.
Figure C1. Selected age-specific population averages projected under the reform policy scenario of a 10-percentage point increase in income tax rates on cohorts born between 1980 and 1989, by method of transfer payment imputation Source: Authors’ calculations using simulated data Notes: Age specific population averages evaluated for population cohorts born between 1980 and 1989. All financial figures reported in 2017 prices. The two series reported in each panel are distinguished by the method used to impute tax and benefit payments.
Figure C2. Selected age-specific population averages projected under the reform policy scenario of a 10-percentage point increase in income tax rates on cohorts born between 1980 and 1989, by method of transfer payment imputation Source: Authors’ calculations using simulated data Notes: Age specific population averages evaluated for population cohorts born between 1980 and 1989. All financial figures reported in 2017 prices. The two series reported in each panel are distinguished by the method used to impute tax and benefit payments.

Tables

Table 1. Correspondence between net tax burden imputed using functional and database descriptions for transfer payments of simulated population cross-section in 2037.
meancorrelation coefficientmean differencestandard deviation of differencemean absolute difference
base policy scenario
full population84.260.930-12.0798.6836.93
single working aged no children44.630.9601.0158.1023.27
single working aged with children84.730.9713.50104.3455.34
couple working aged no children212.750.816-72.01191.7785.24
couple working aged with children307.990.957-0.32128.6657.83
single pensioner2.390.807-13.5245.8822.00
couple pensioner33.360.786-22.3470.0826.08
reform scenario (all rates of income tax increased by 10 percentage points)
full population105.640.936-17.34112.7043.10
single working aged no children57.570.947-1.6766.9926.96
single working aged with children121.360.974-2.28119.9862.81
couple working aged no children245.930.868-87.95214.95101.98
couple working aged with children384.350.961-10.82153.6768.49
single pensioner5.710.860-14.6747.0023.86
couple pensioner41.680.847-27.7982.2532.27

Source: Authors’ calculations using simulated data.

Notes: working age adults between 18 and 66 years; pensioners aged 67 and over; children include all dependents aged 0 to 17 years; all income measured in £ per week; "mean" reports sample arithmetic averages for net taxes evaluated using functional description for transfer payments; "correlation coefficients" report correlations between net tax payments evaluated using functional and database descriptions for transfer payments. "mean difference" statistics report sample averages for net taxes evaluated using database description for transfer payments less net taxes evaluated using functional description for transfer payments. "standard deviation of difference" statistics report sample statistics for "mean differences". "mean absolute difference" statistics report sample averages for absolute differences between net taxes evaluated using functional and database descriptions for transfer payments.

Table A1. Simulation run-times by policy scenario and method of transfer payment imputation.
behavioural solutionpopulation projectiontotal
net transfer payments imputed using database
Base54.590.9145.4
Reform55.752.0107.7
net transfer payments calculated using function
Base54.387.0141.3
Reform54.453.3107.7

Source: Authors’ calculations using simulated data. Notes: "base" defines reference policy context; "reform" defines policy context that is identical to "base" in all respects, expect that all income tax rates are increased by 10 percentage points. All times reported in minutes. Simulations run on workstation with dual Xeon E5-2670 processors and 96GB of RAM.