
This article contains 9 figures and 2 tables.
Figures
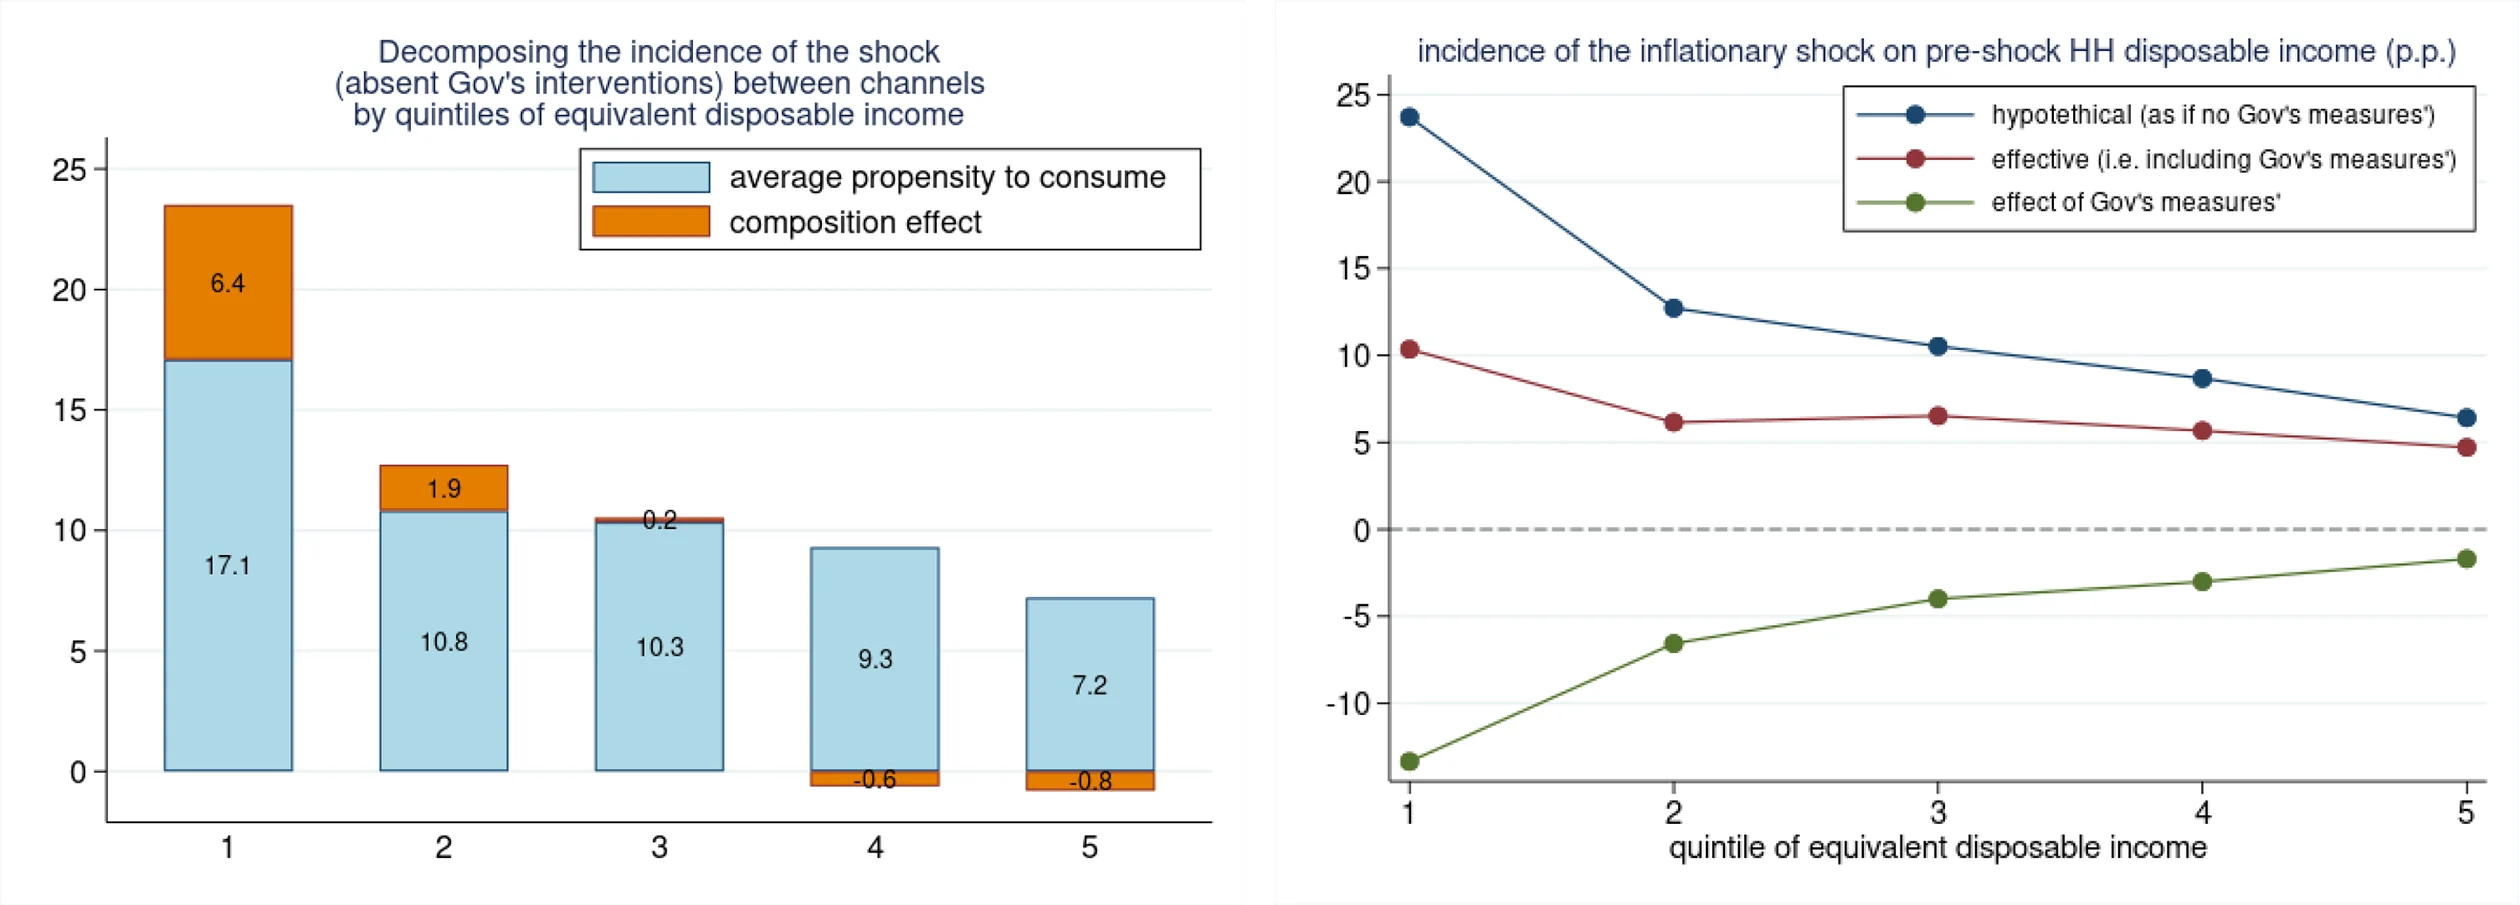
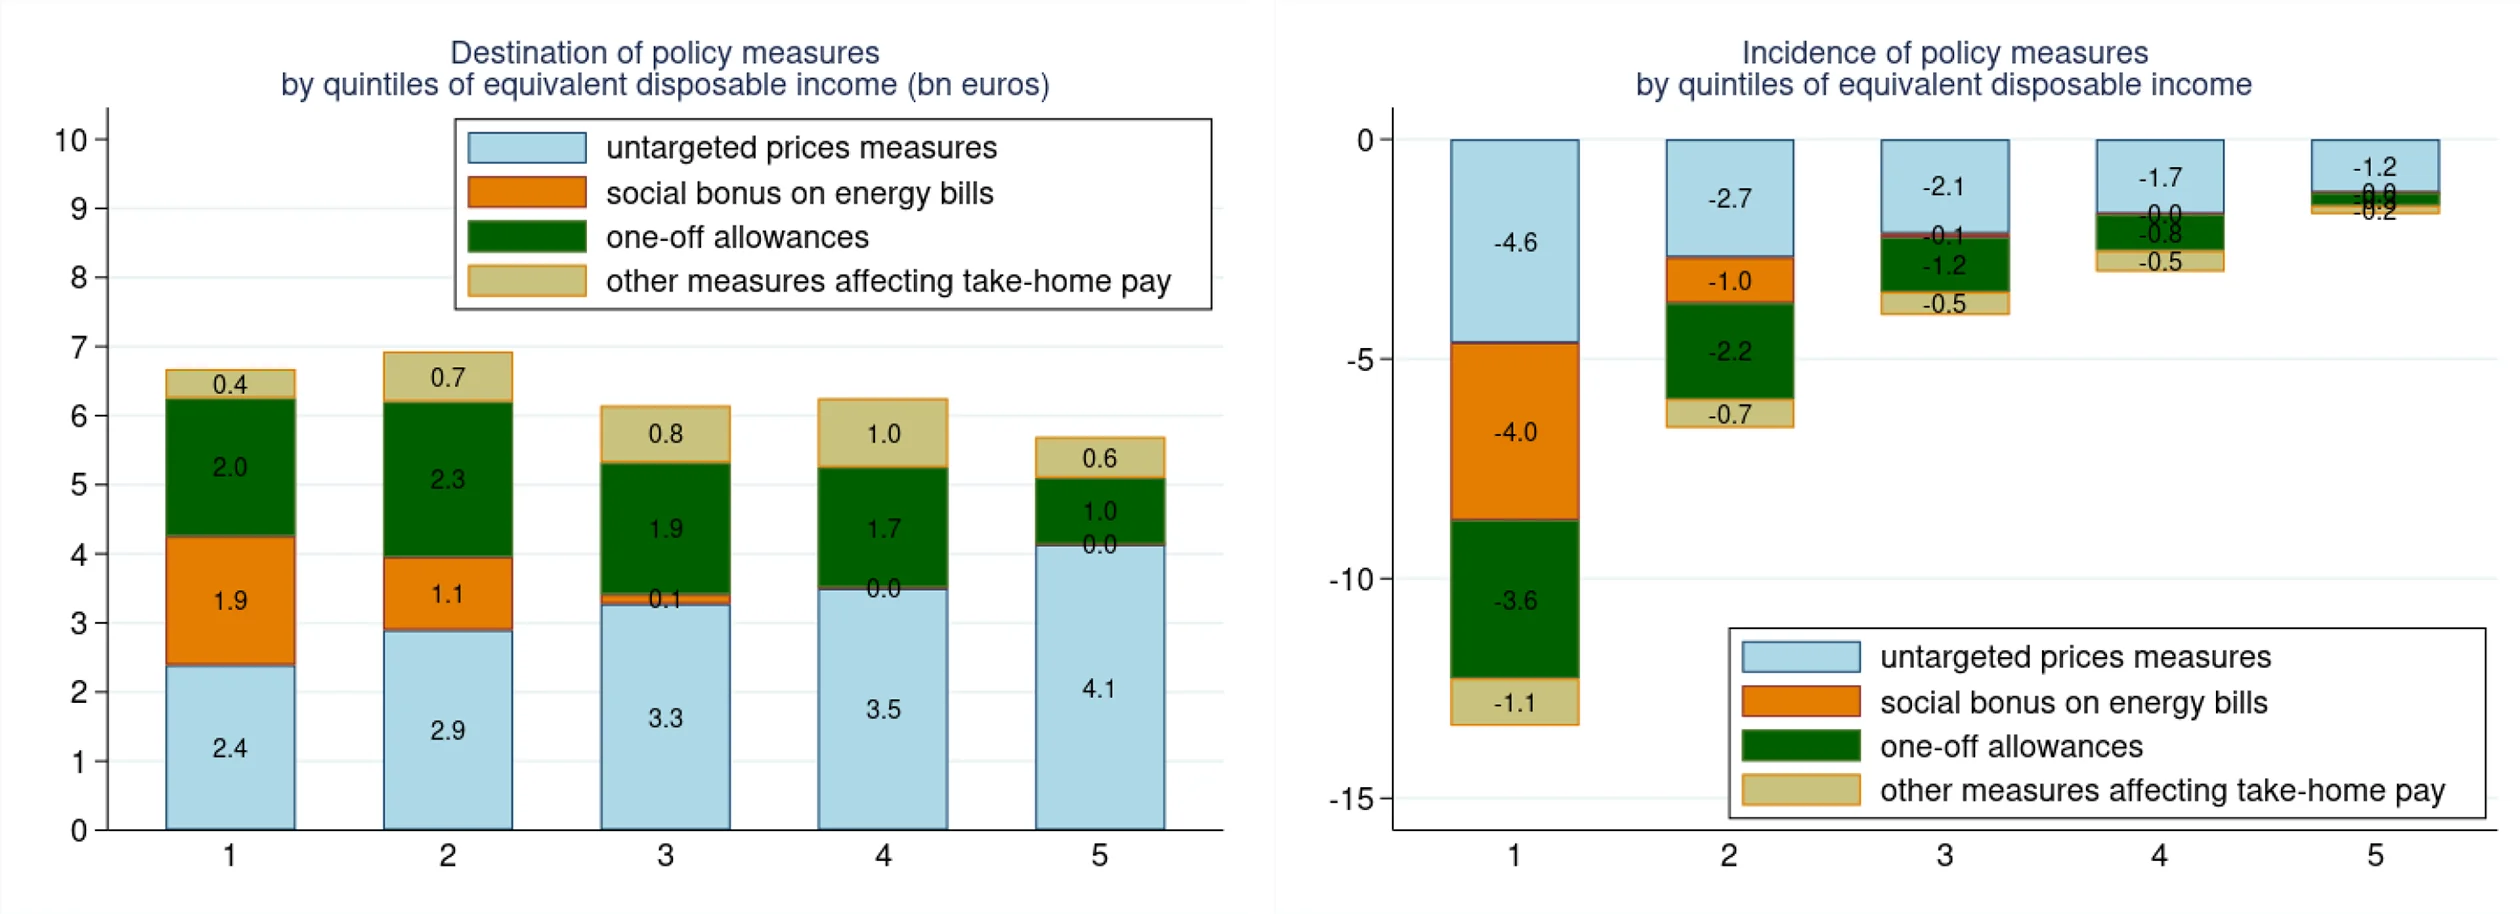
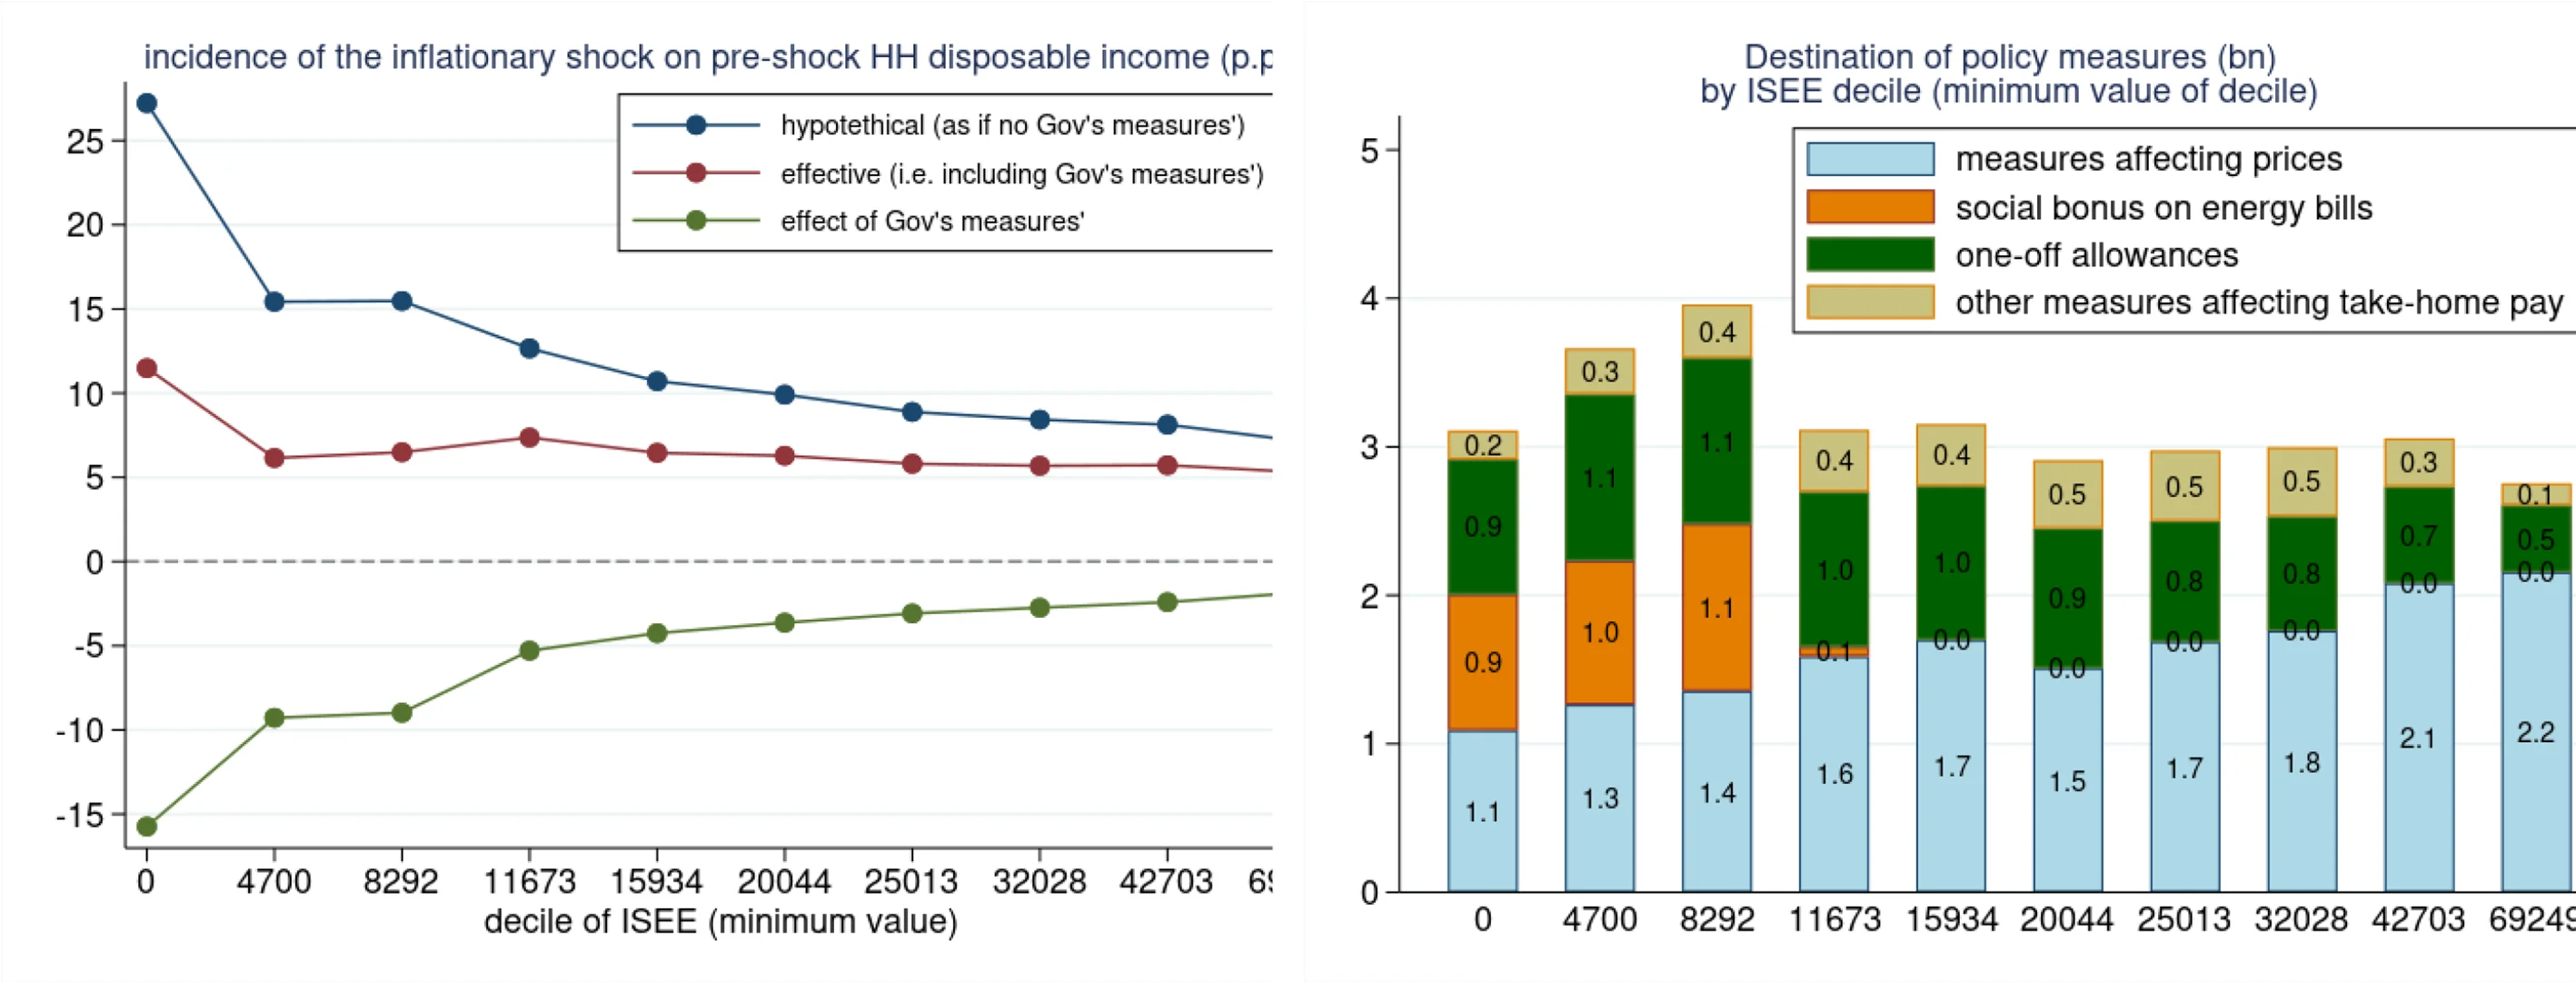
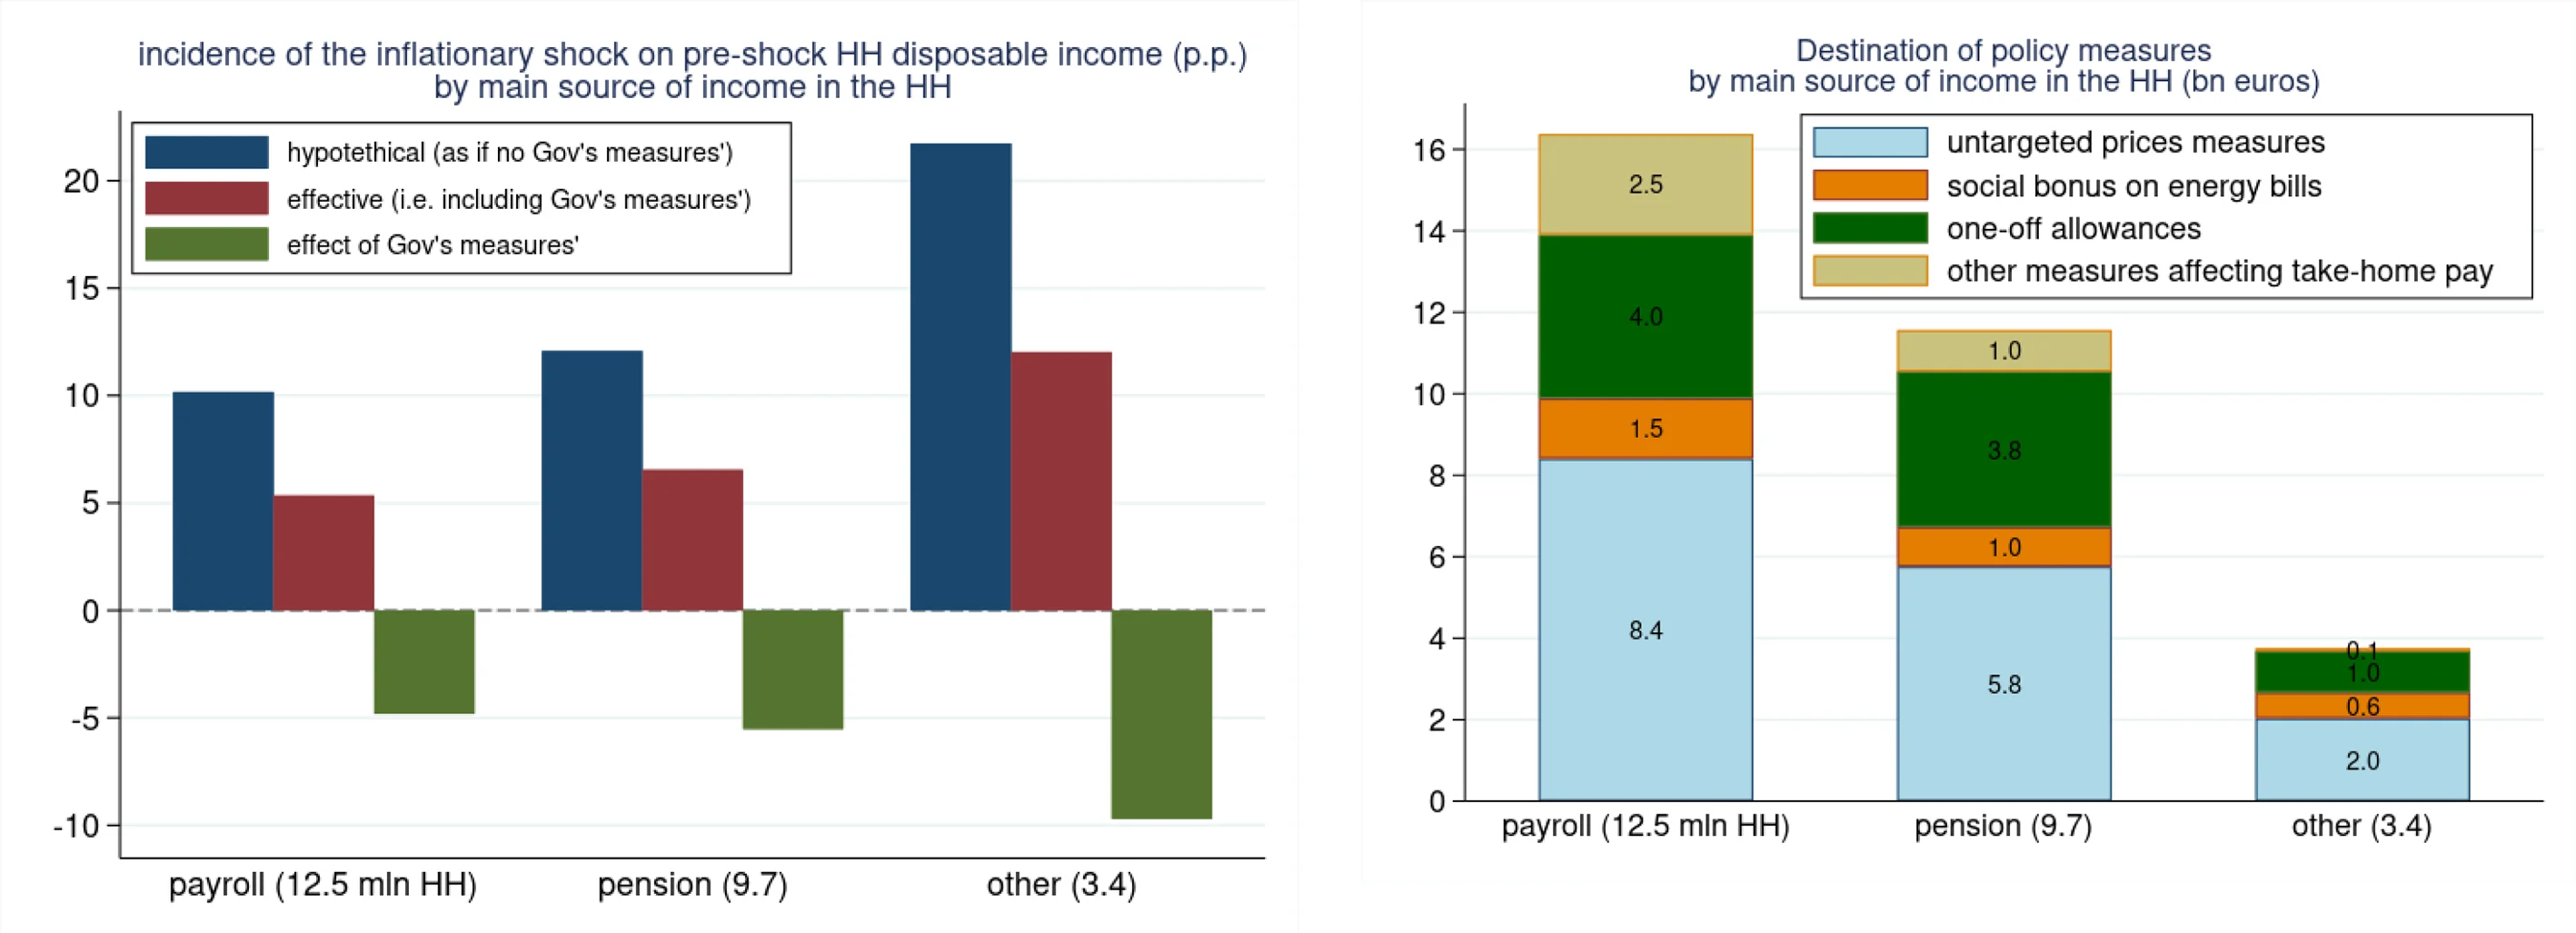
Tables
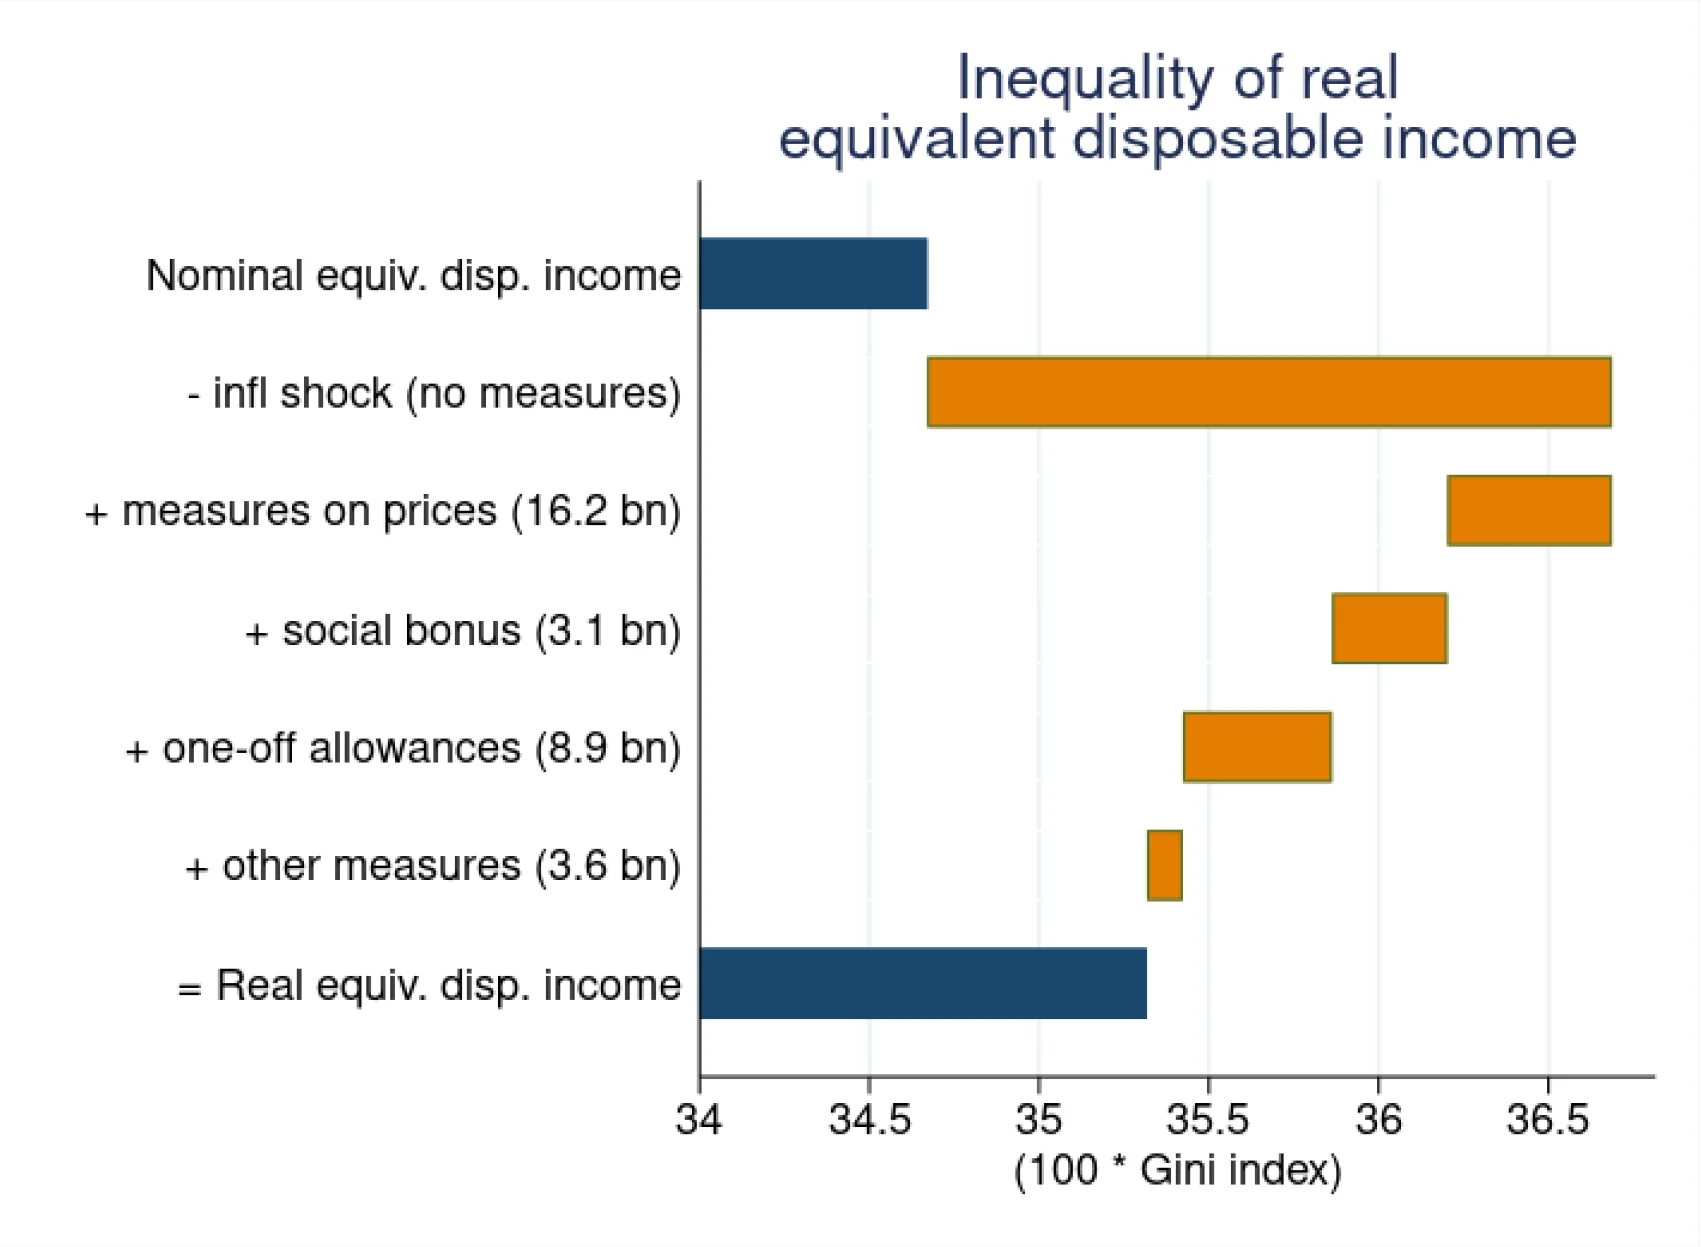
| Estimated total effect without Government intervention | 81.3 |
|---|---|
| - minus reduction of general system charges, excise duties and VAT | 16.2 |
| - minus increase of the social bonus on energy bills | 3.1 |
| - minus one-off allowances | 8.9 |
| - minus other measures affecting take-home pay | 3.6 |
| = Effective impact including Government intervention | 49.6 |
Source: our calculations on data from Istat, Banca d’Italia and BIMic.
Note: “one-off allowances” include the 200- and 150-euros bonuses; “other measures affecting take-home pay” include the reduction of social security contributions paid by employees and the partial advance to 2022 of pension indexation.
| Total | Quintiles of disposable income | |||||
|---|---|---|---|---|---|---|
| 1 | 2 | 3 | 4 | 5 | ||
| Total effect without Government intervention: (a) | 3,186 | 2,305 | 2,675 | 3,160 | 3,497 | 4,292 |
| Total effect with Goverm-nment intervention: (b) | 1,944 | 998 | 1,320 | 1,955 | 2,273 | 3,176 |
| Attenuation of the total effect due to Government intervention: (a)-(b) of which | 1,241 | 1,307 | 1,356 | 1,205 | 1,224 | 1,115 |
| measures on general system charges, excise duties and VAT | 635 | 468 | 567 | 642 | 685 | 811 |
| social bonus on energy bills | 120 | 365 | 206 | 27 | 3 | 0 |
| one-off allowances | 347 | 392 | 441 | 374 | 341 | 189 |
| other measures affecting take-home pay | 139 | 82 | 142 | 162 | 195 | 116 |
Source: our calculations on data from Istat, Banca d’Italia and BIMic.
Note: “one-off allowances” include the 200- and 150-euros bonuses; “other measures affecting take-home pay” include the reduction of social security contributions paid by employees and the partial advance to 2022 of pension indexation.