
This article contains 8 figures and 10 tables.
Figures
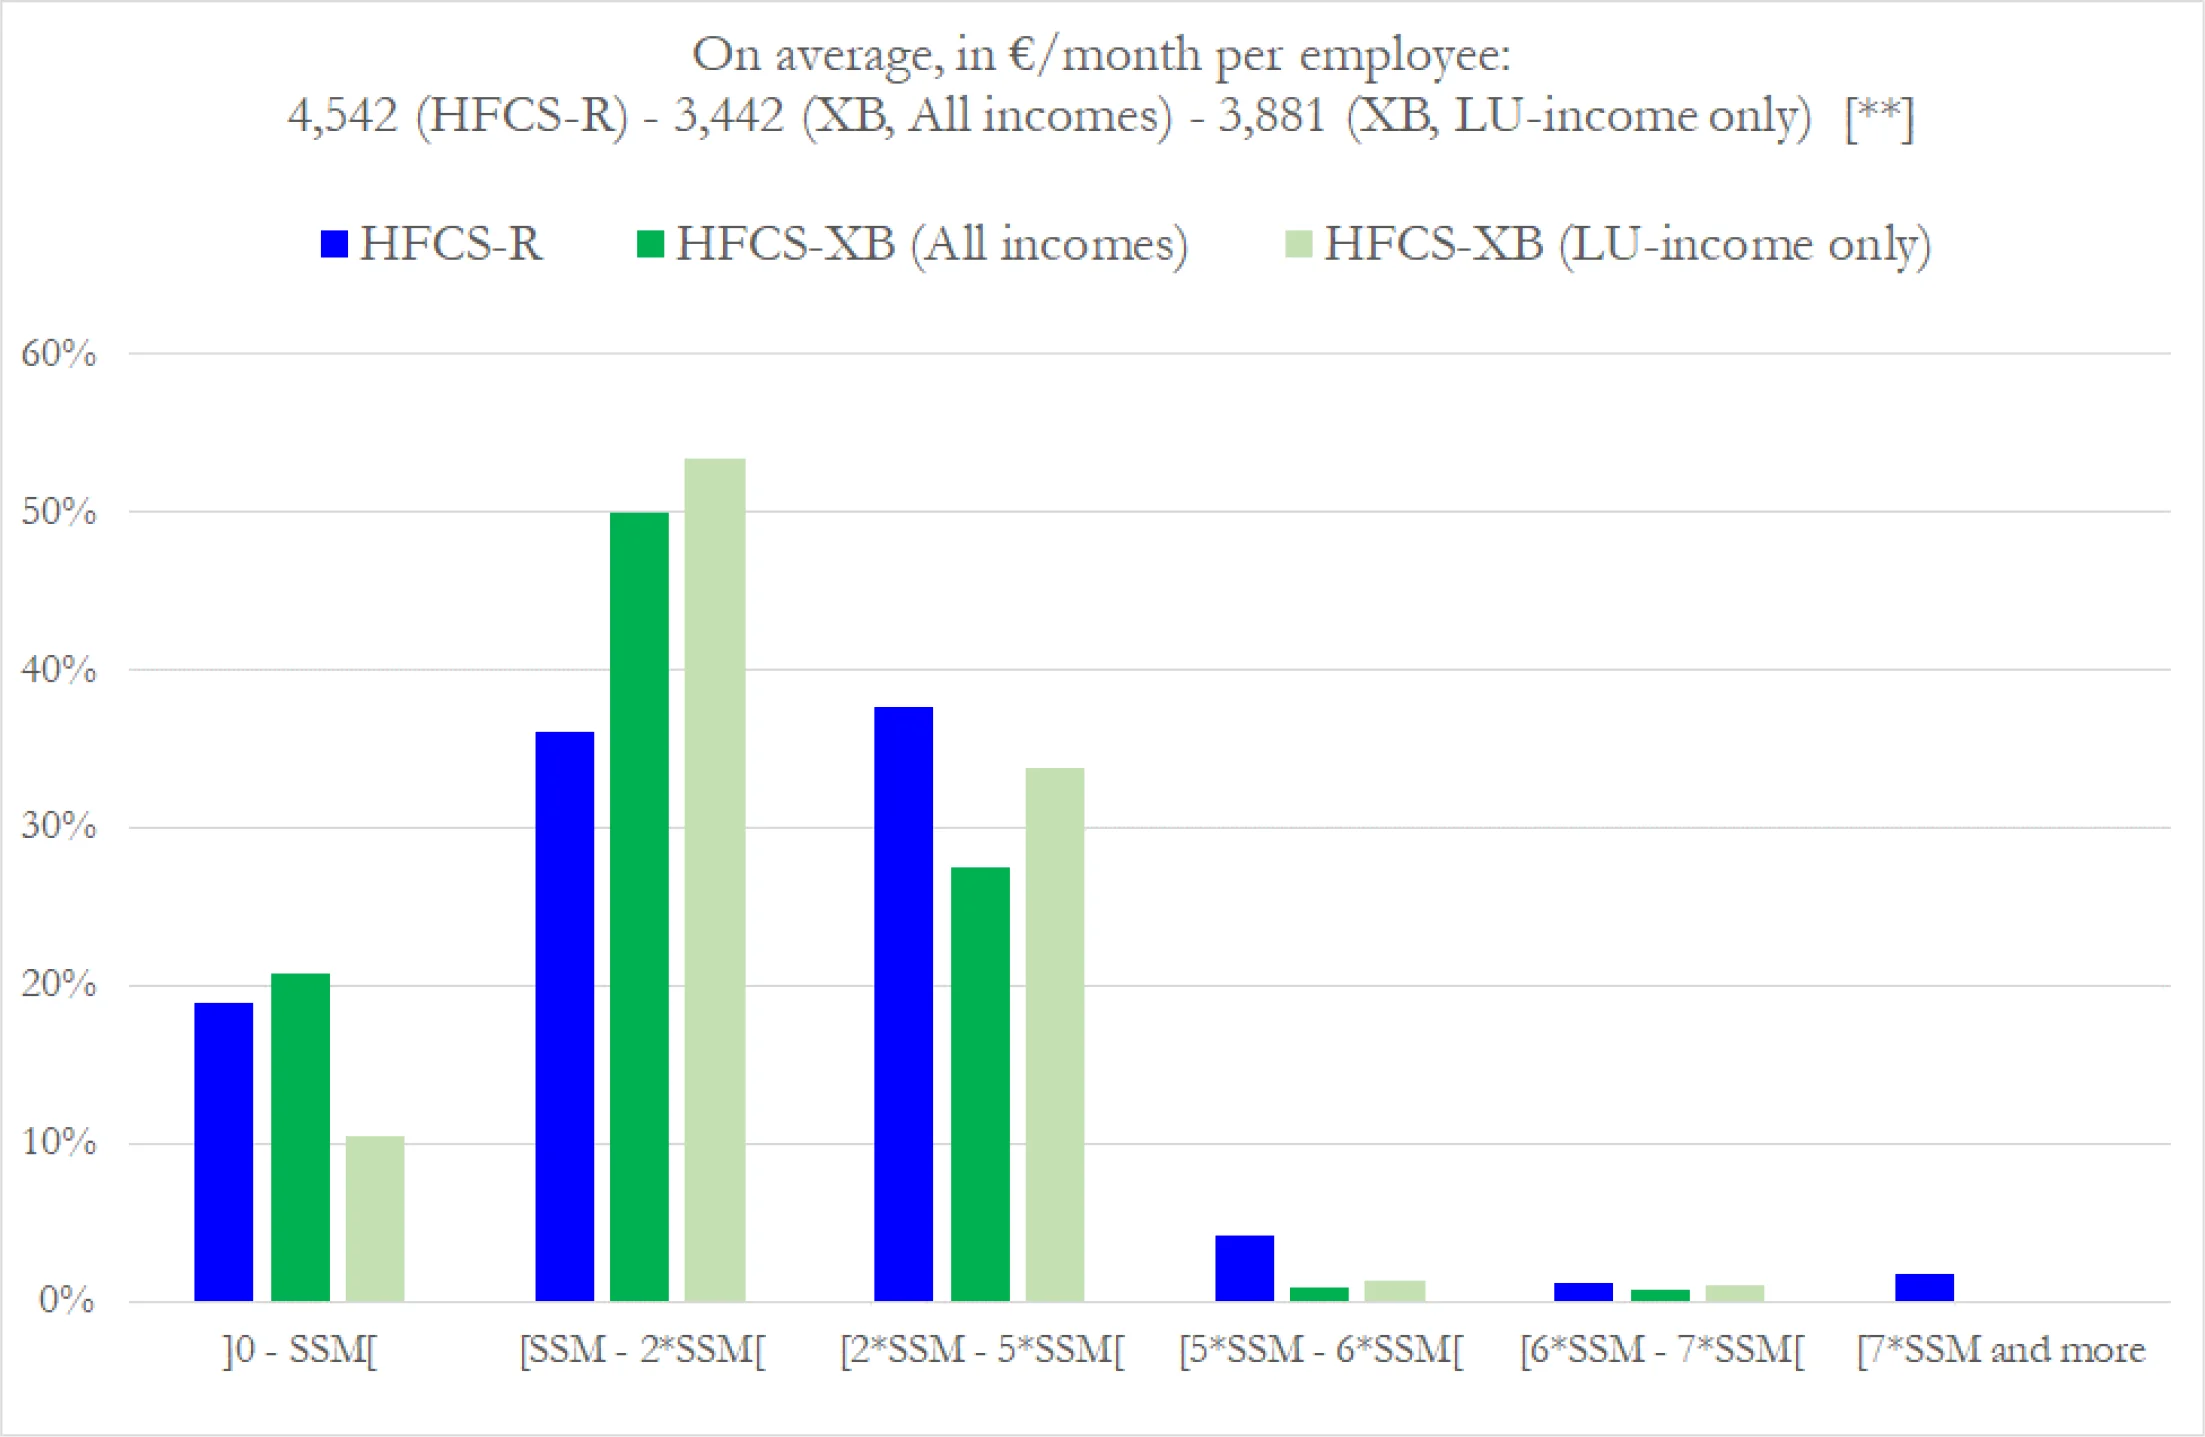
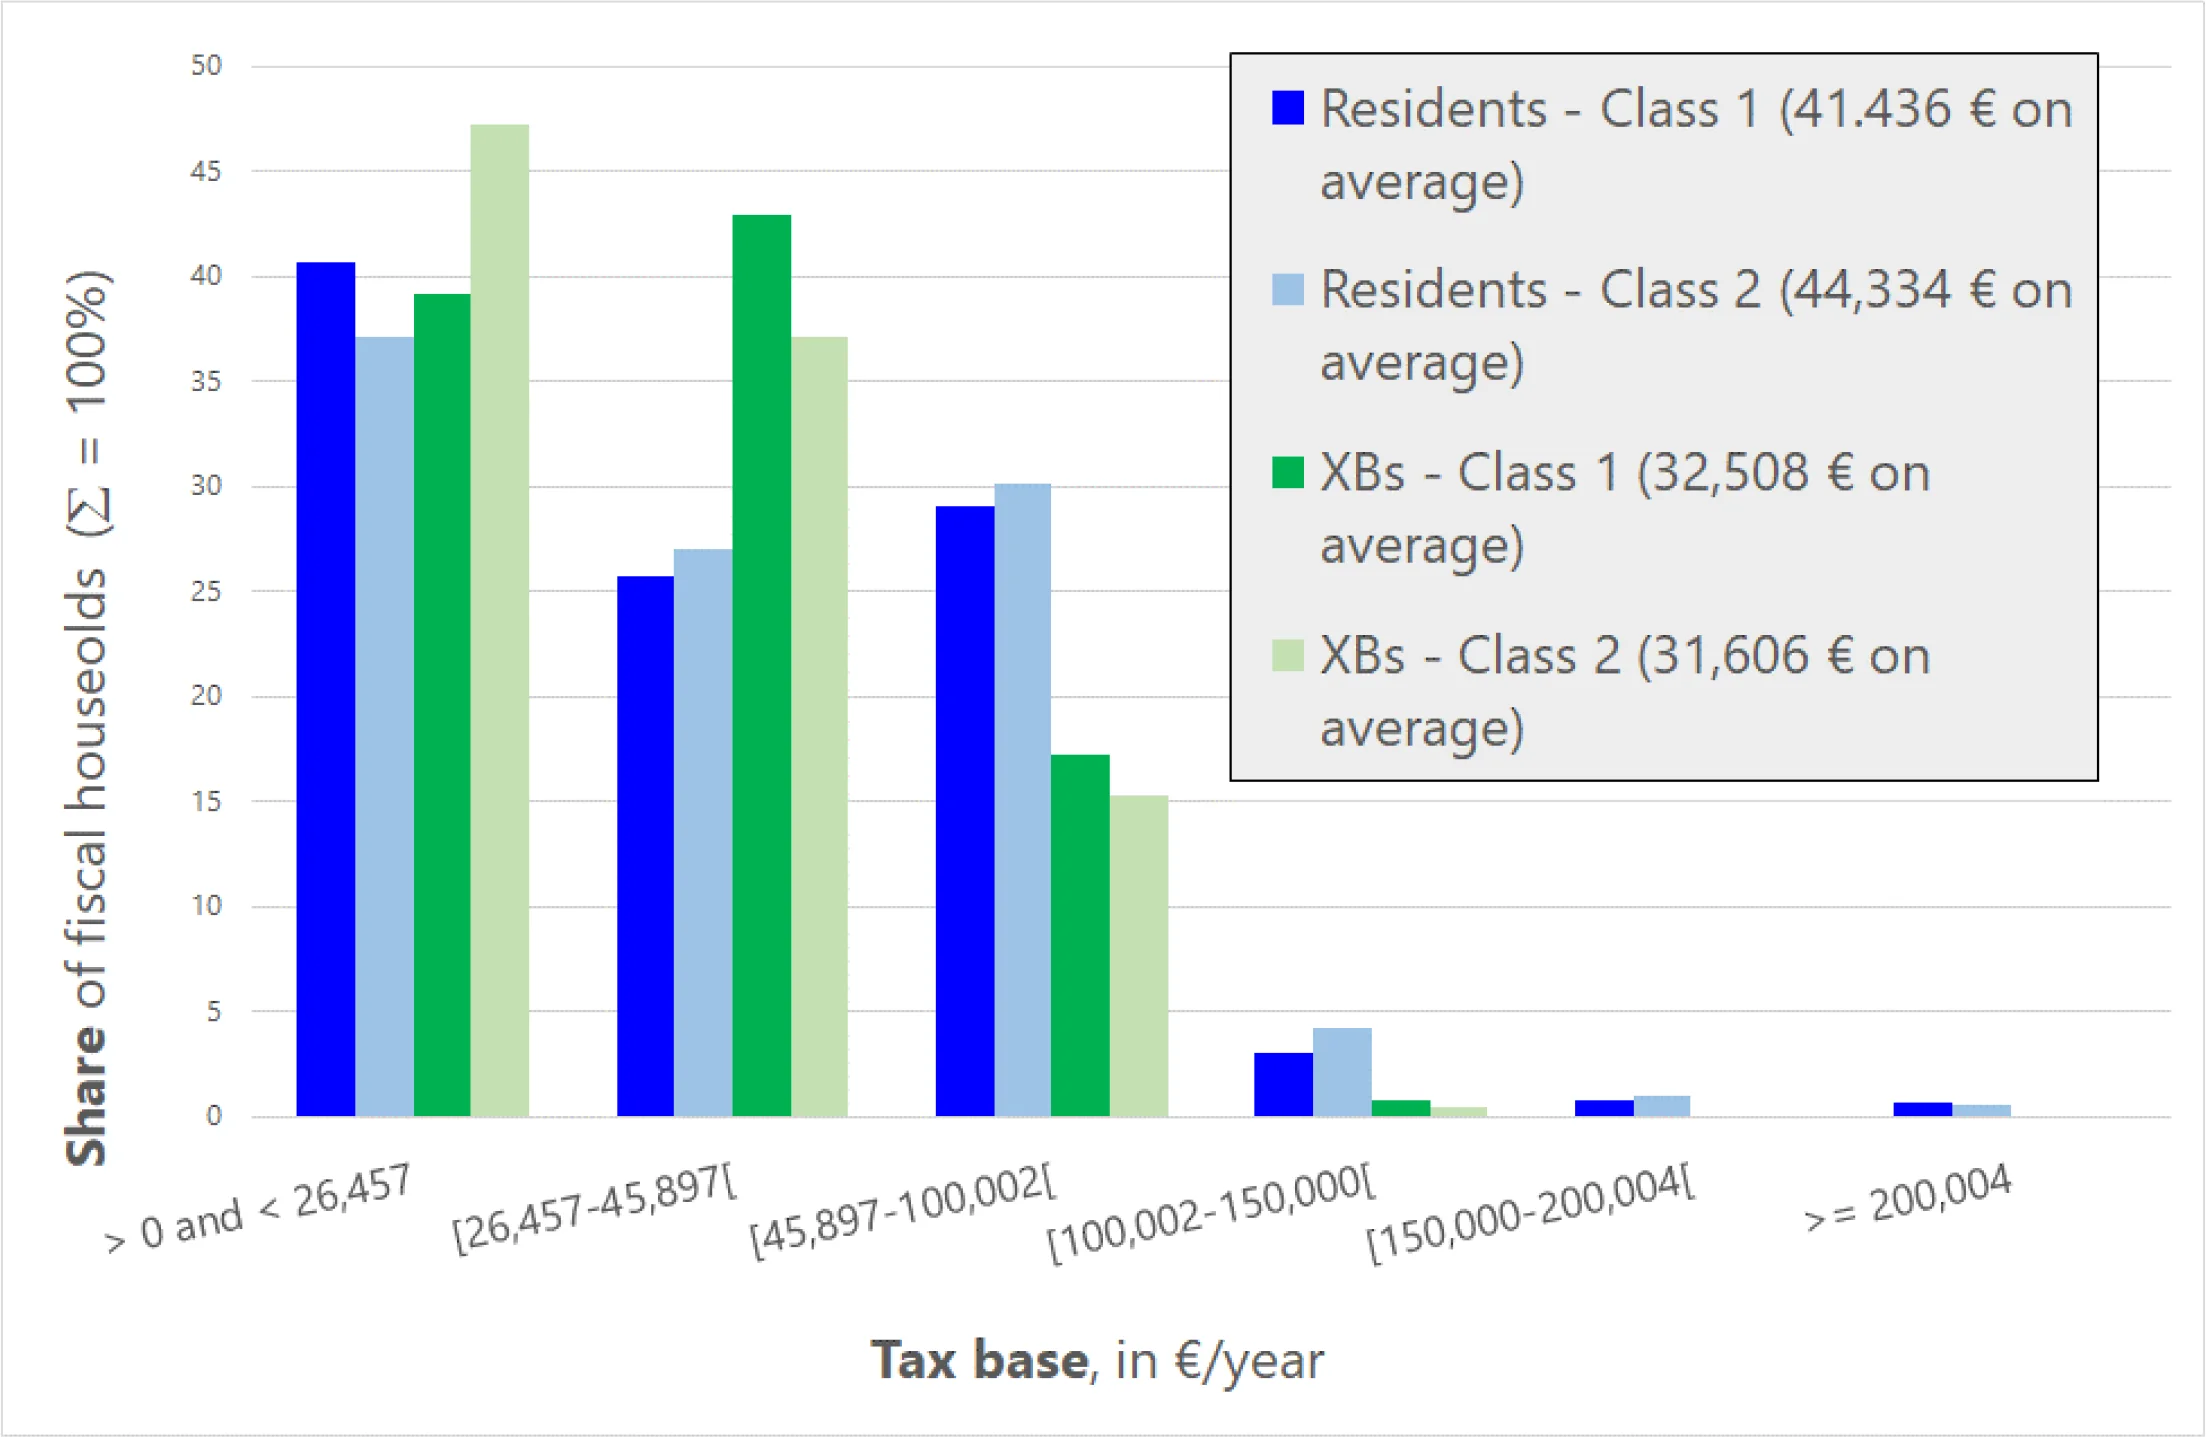
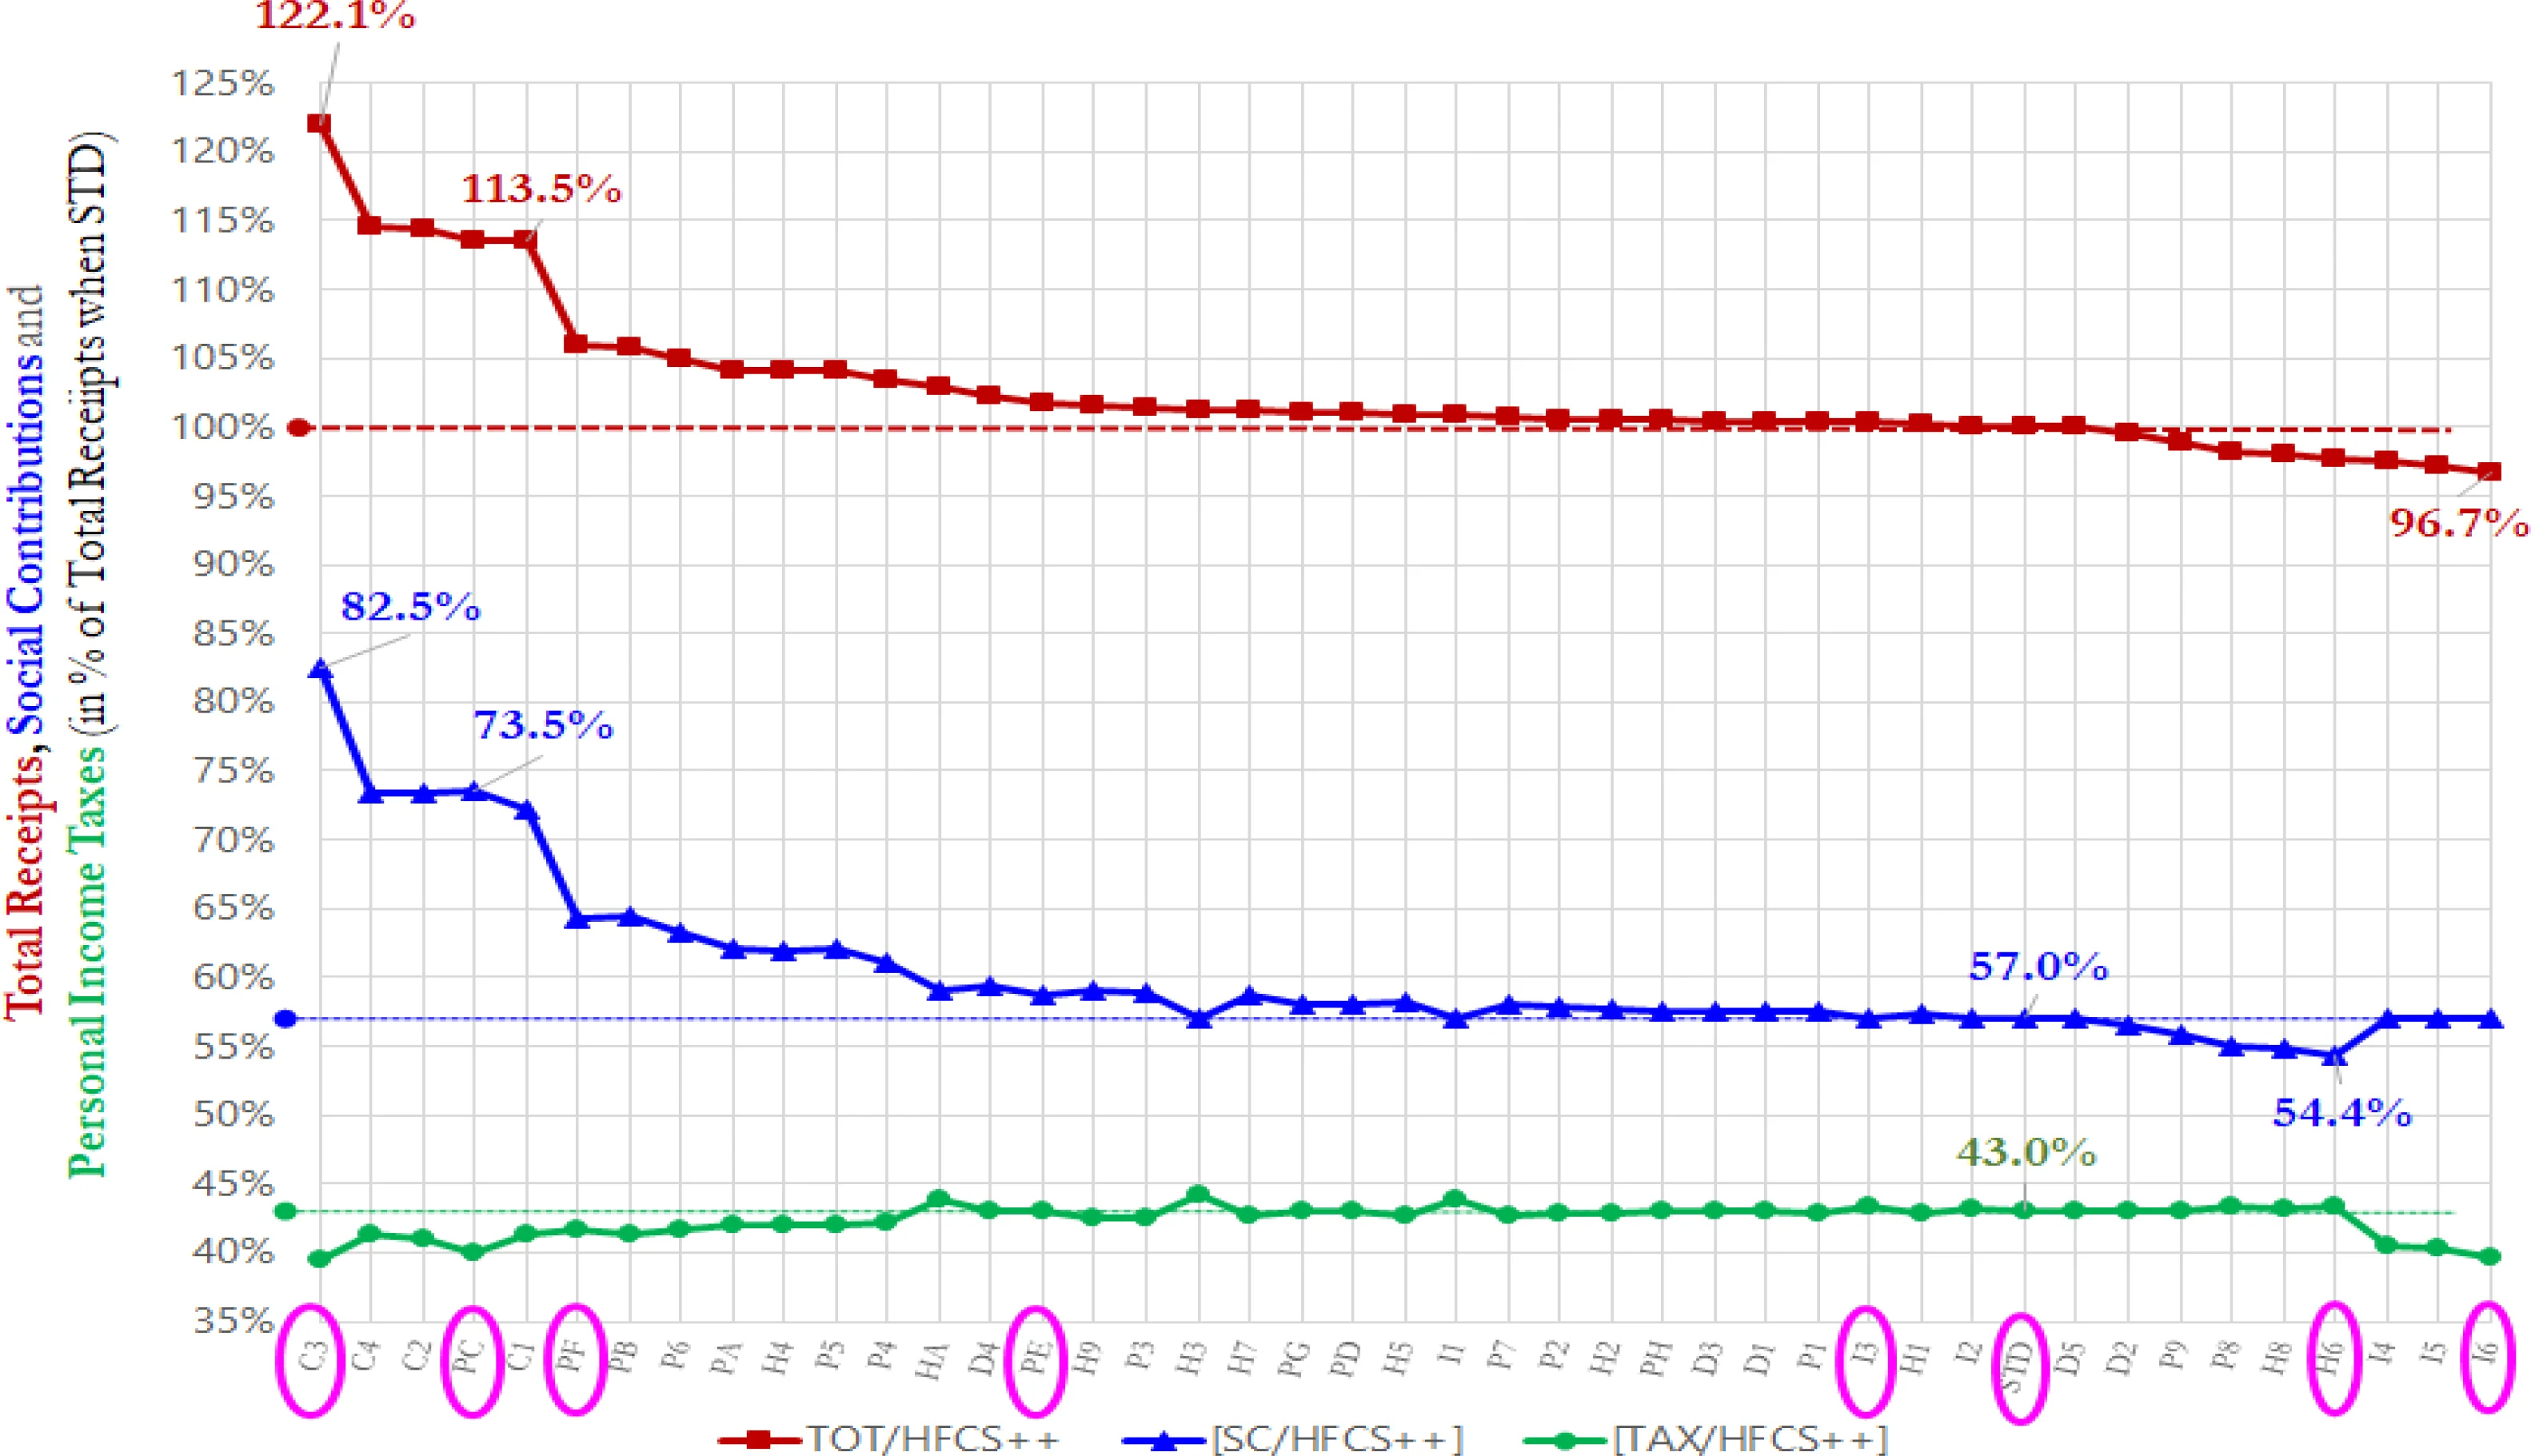
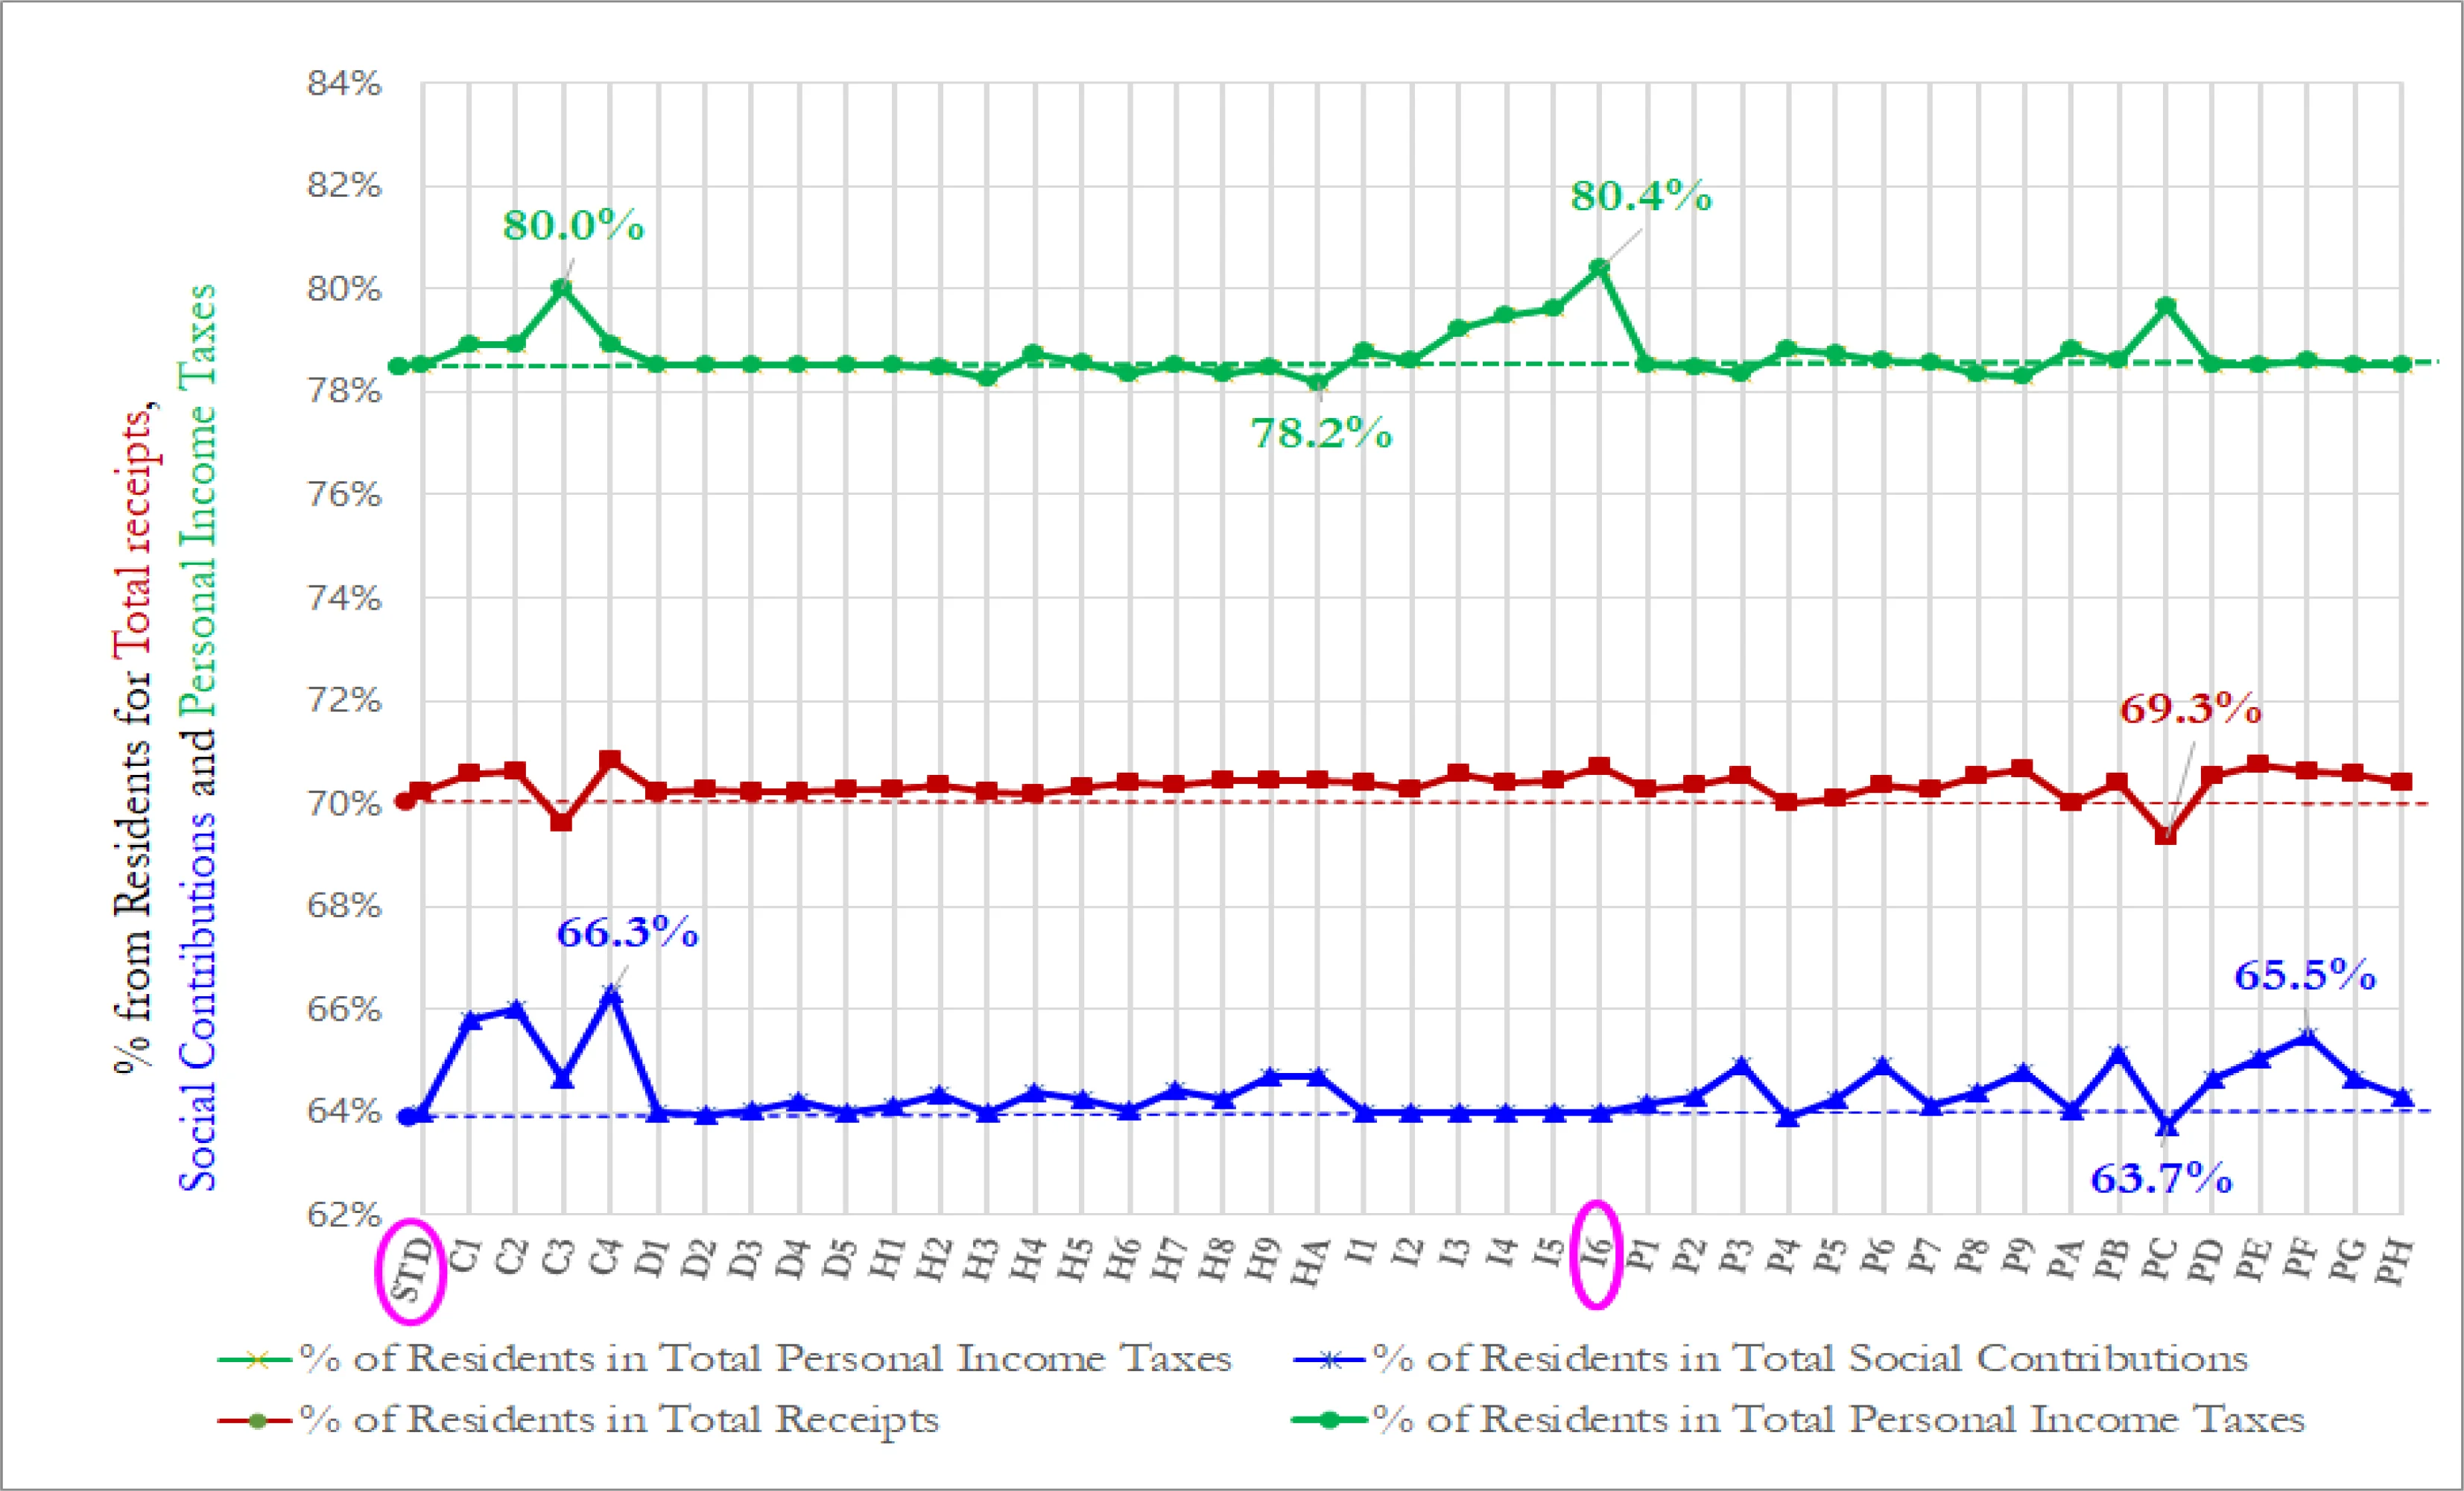
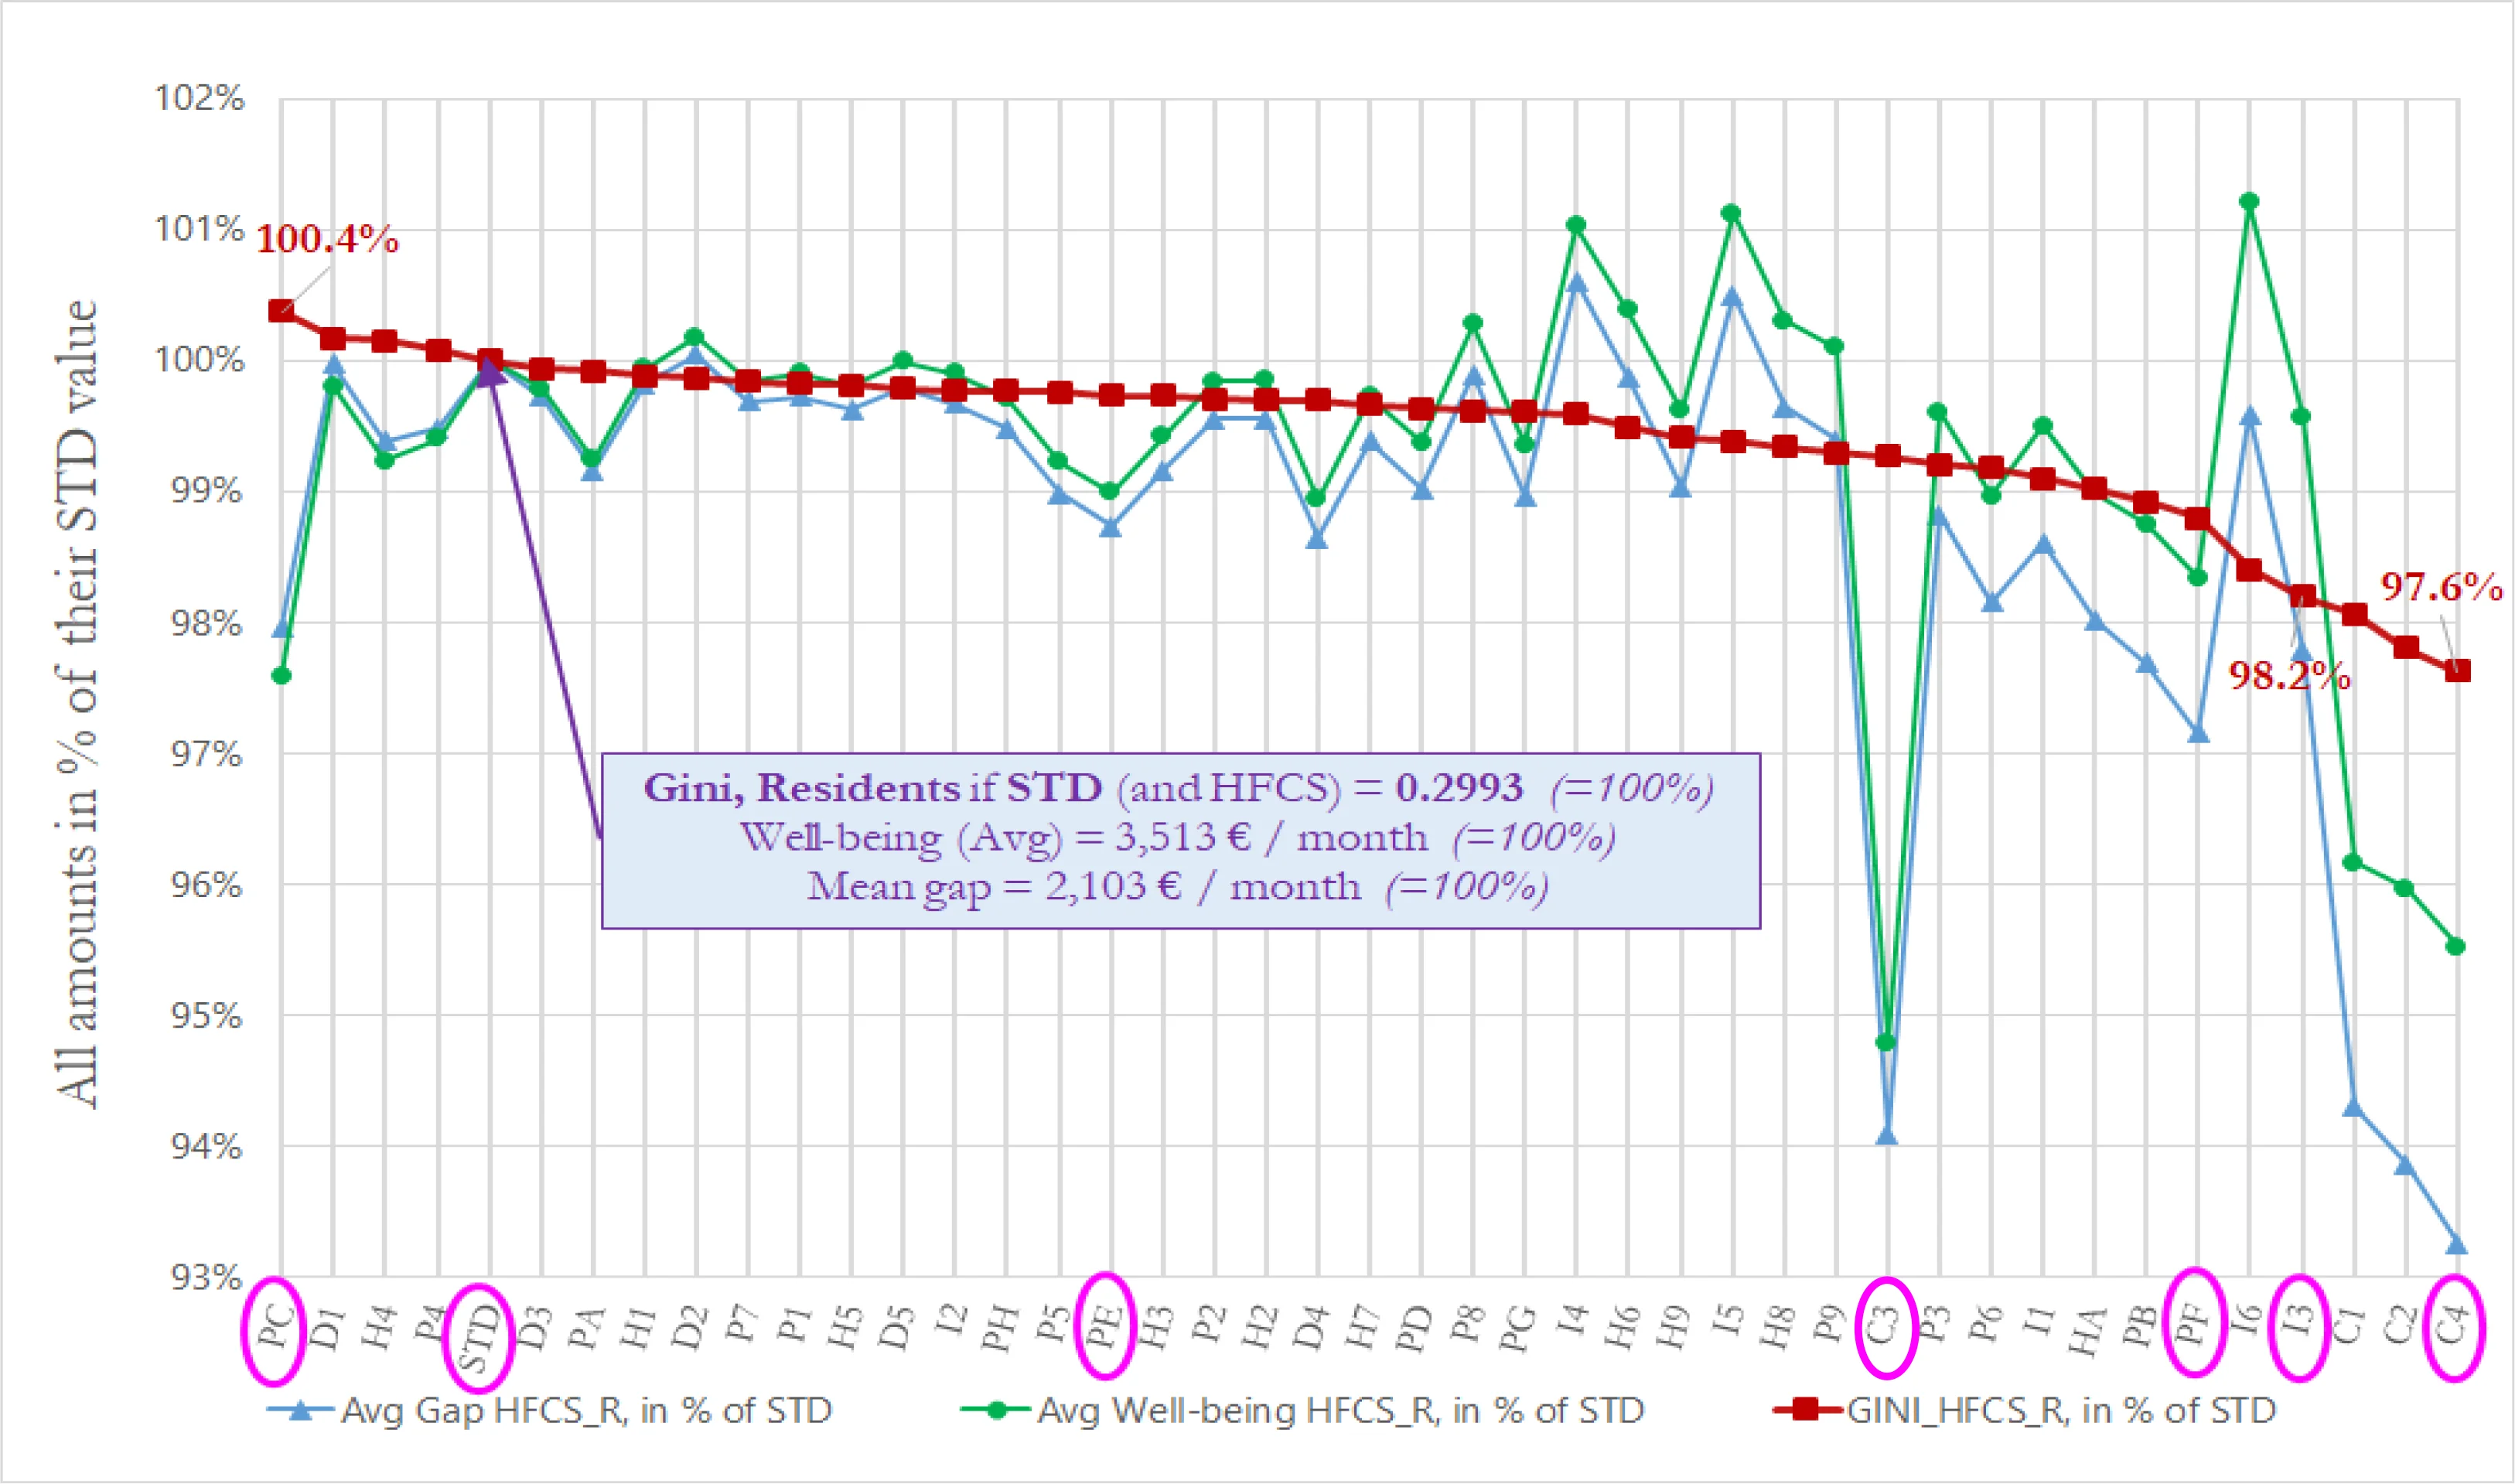
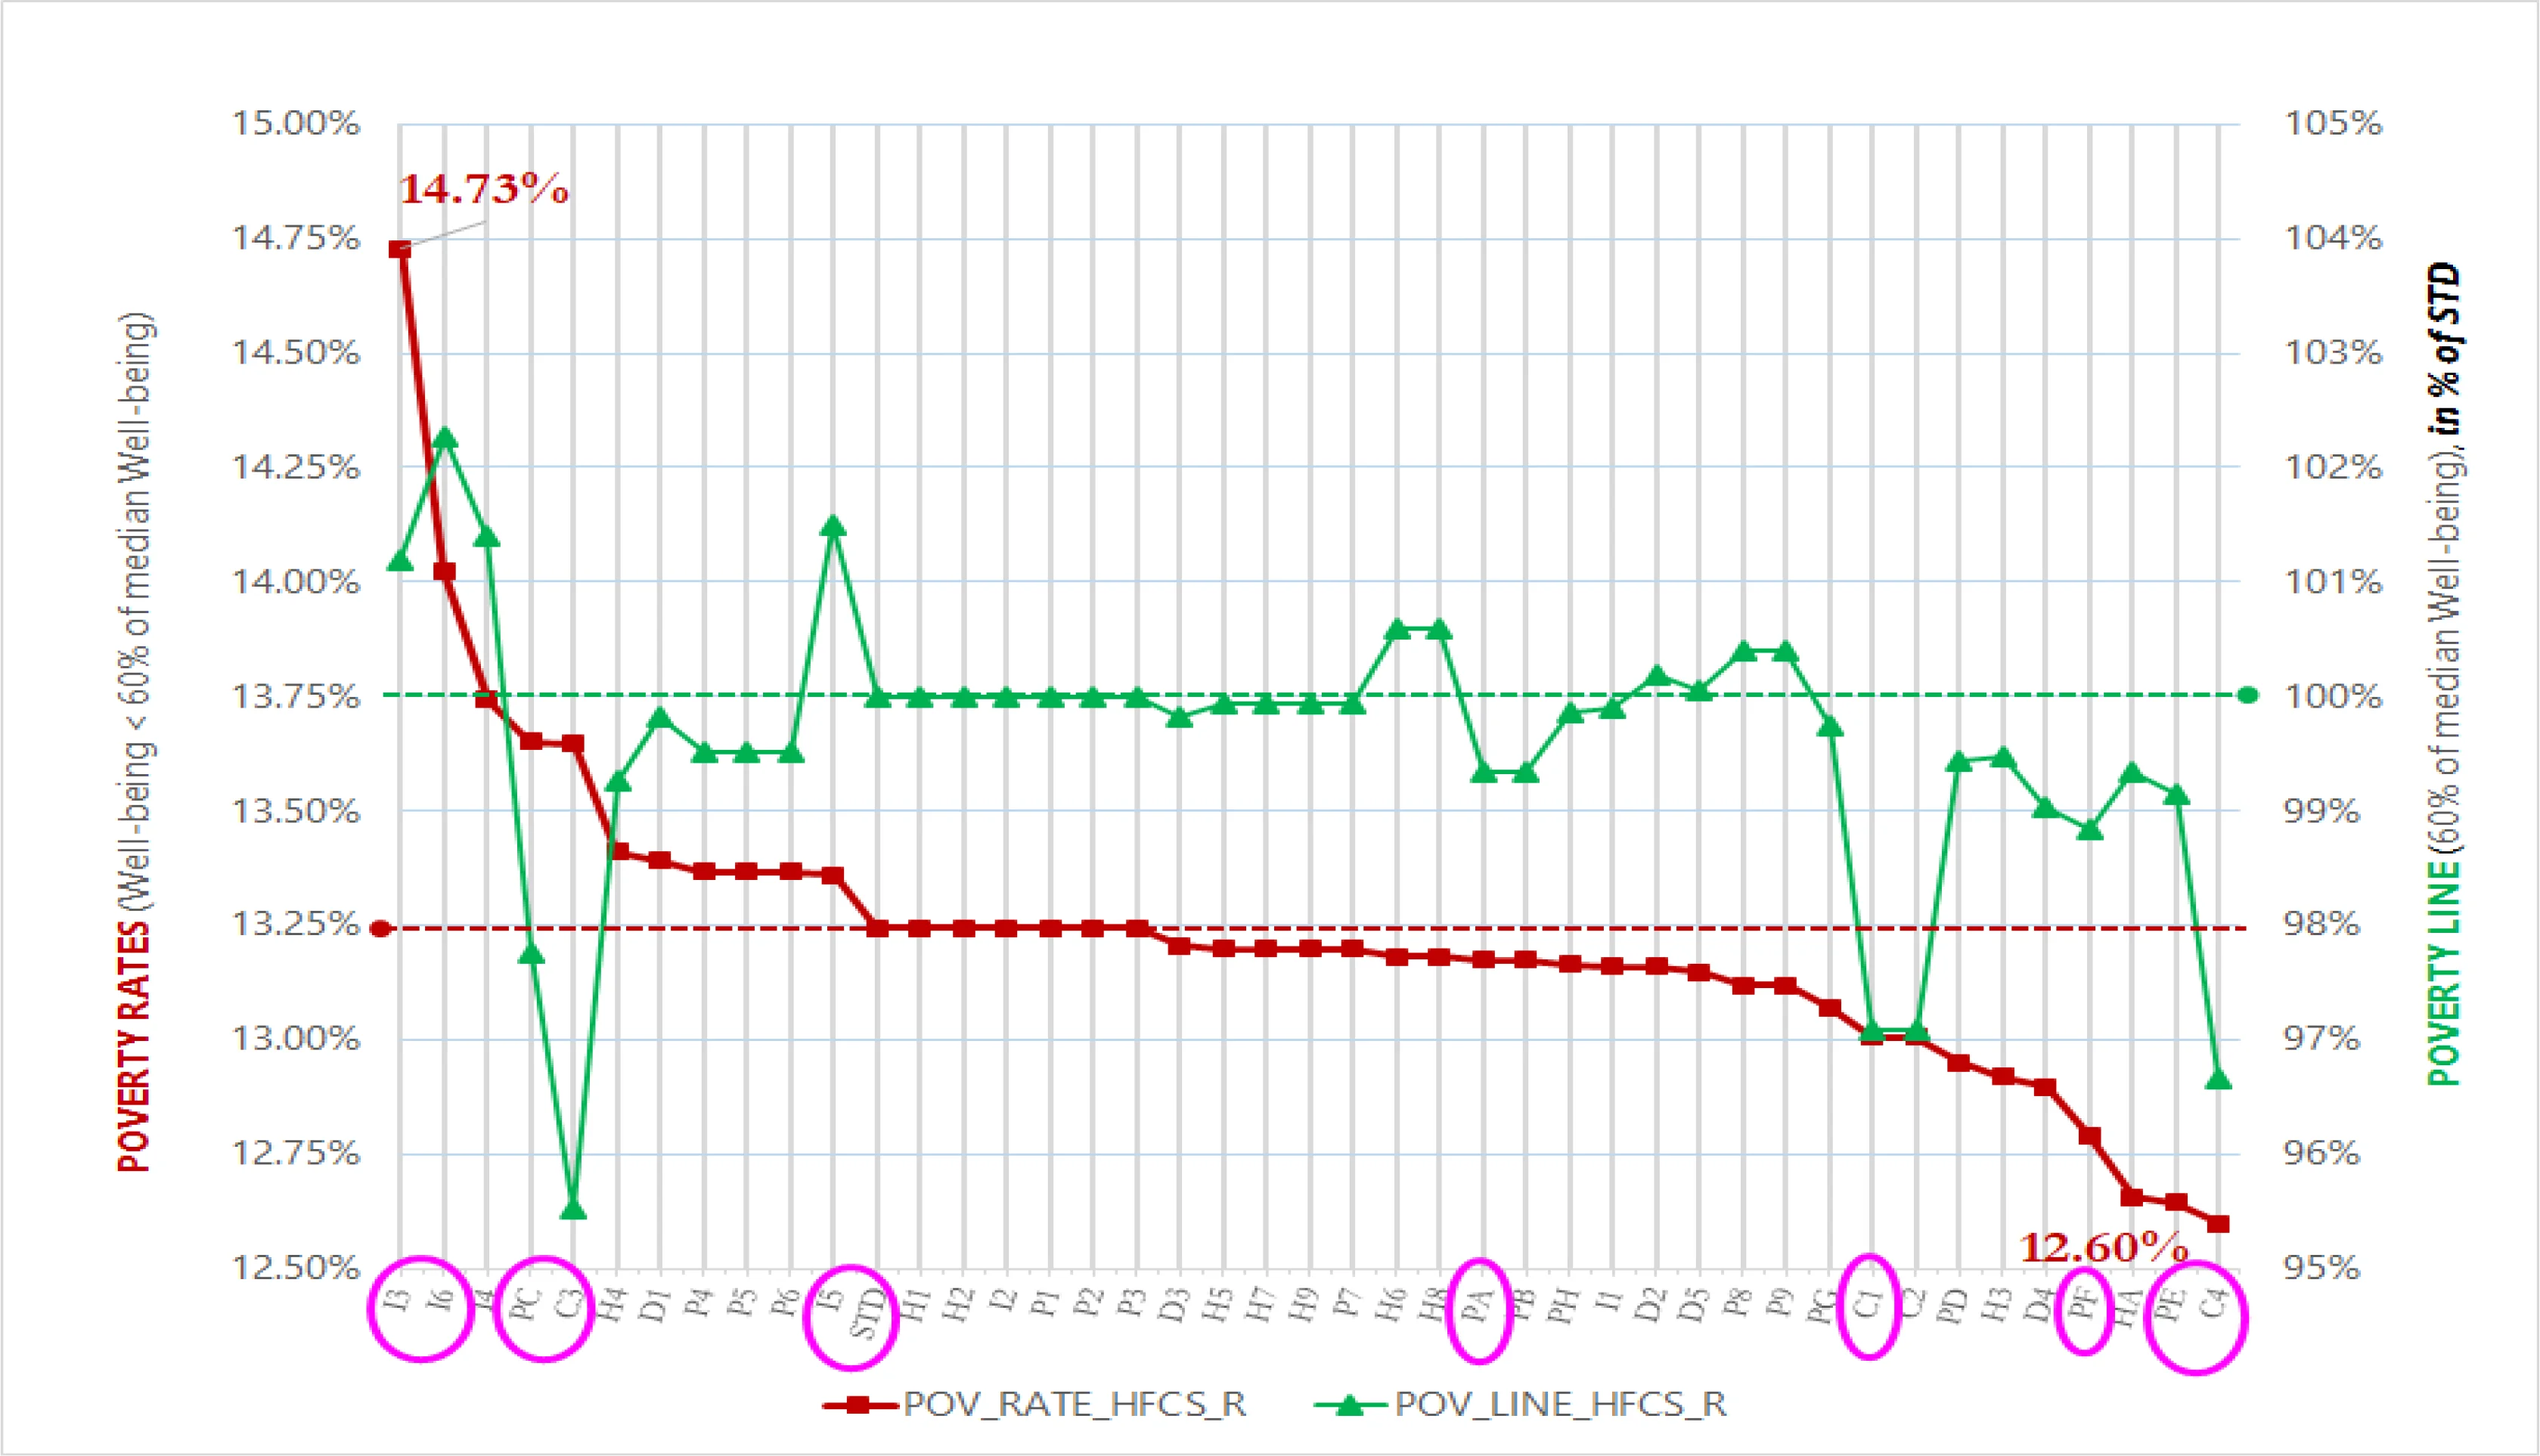
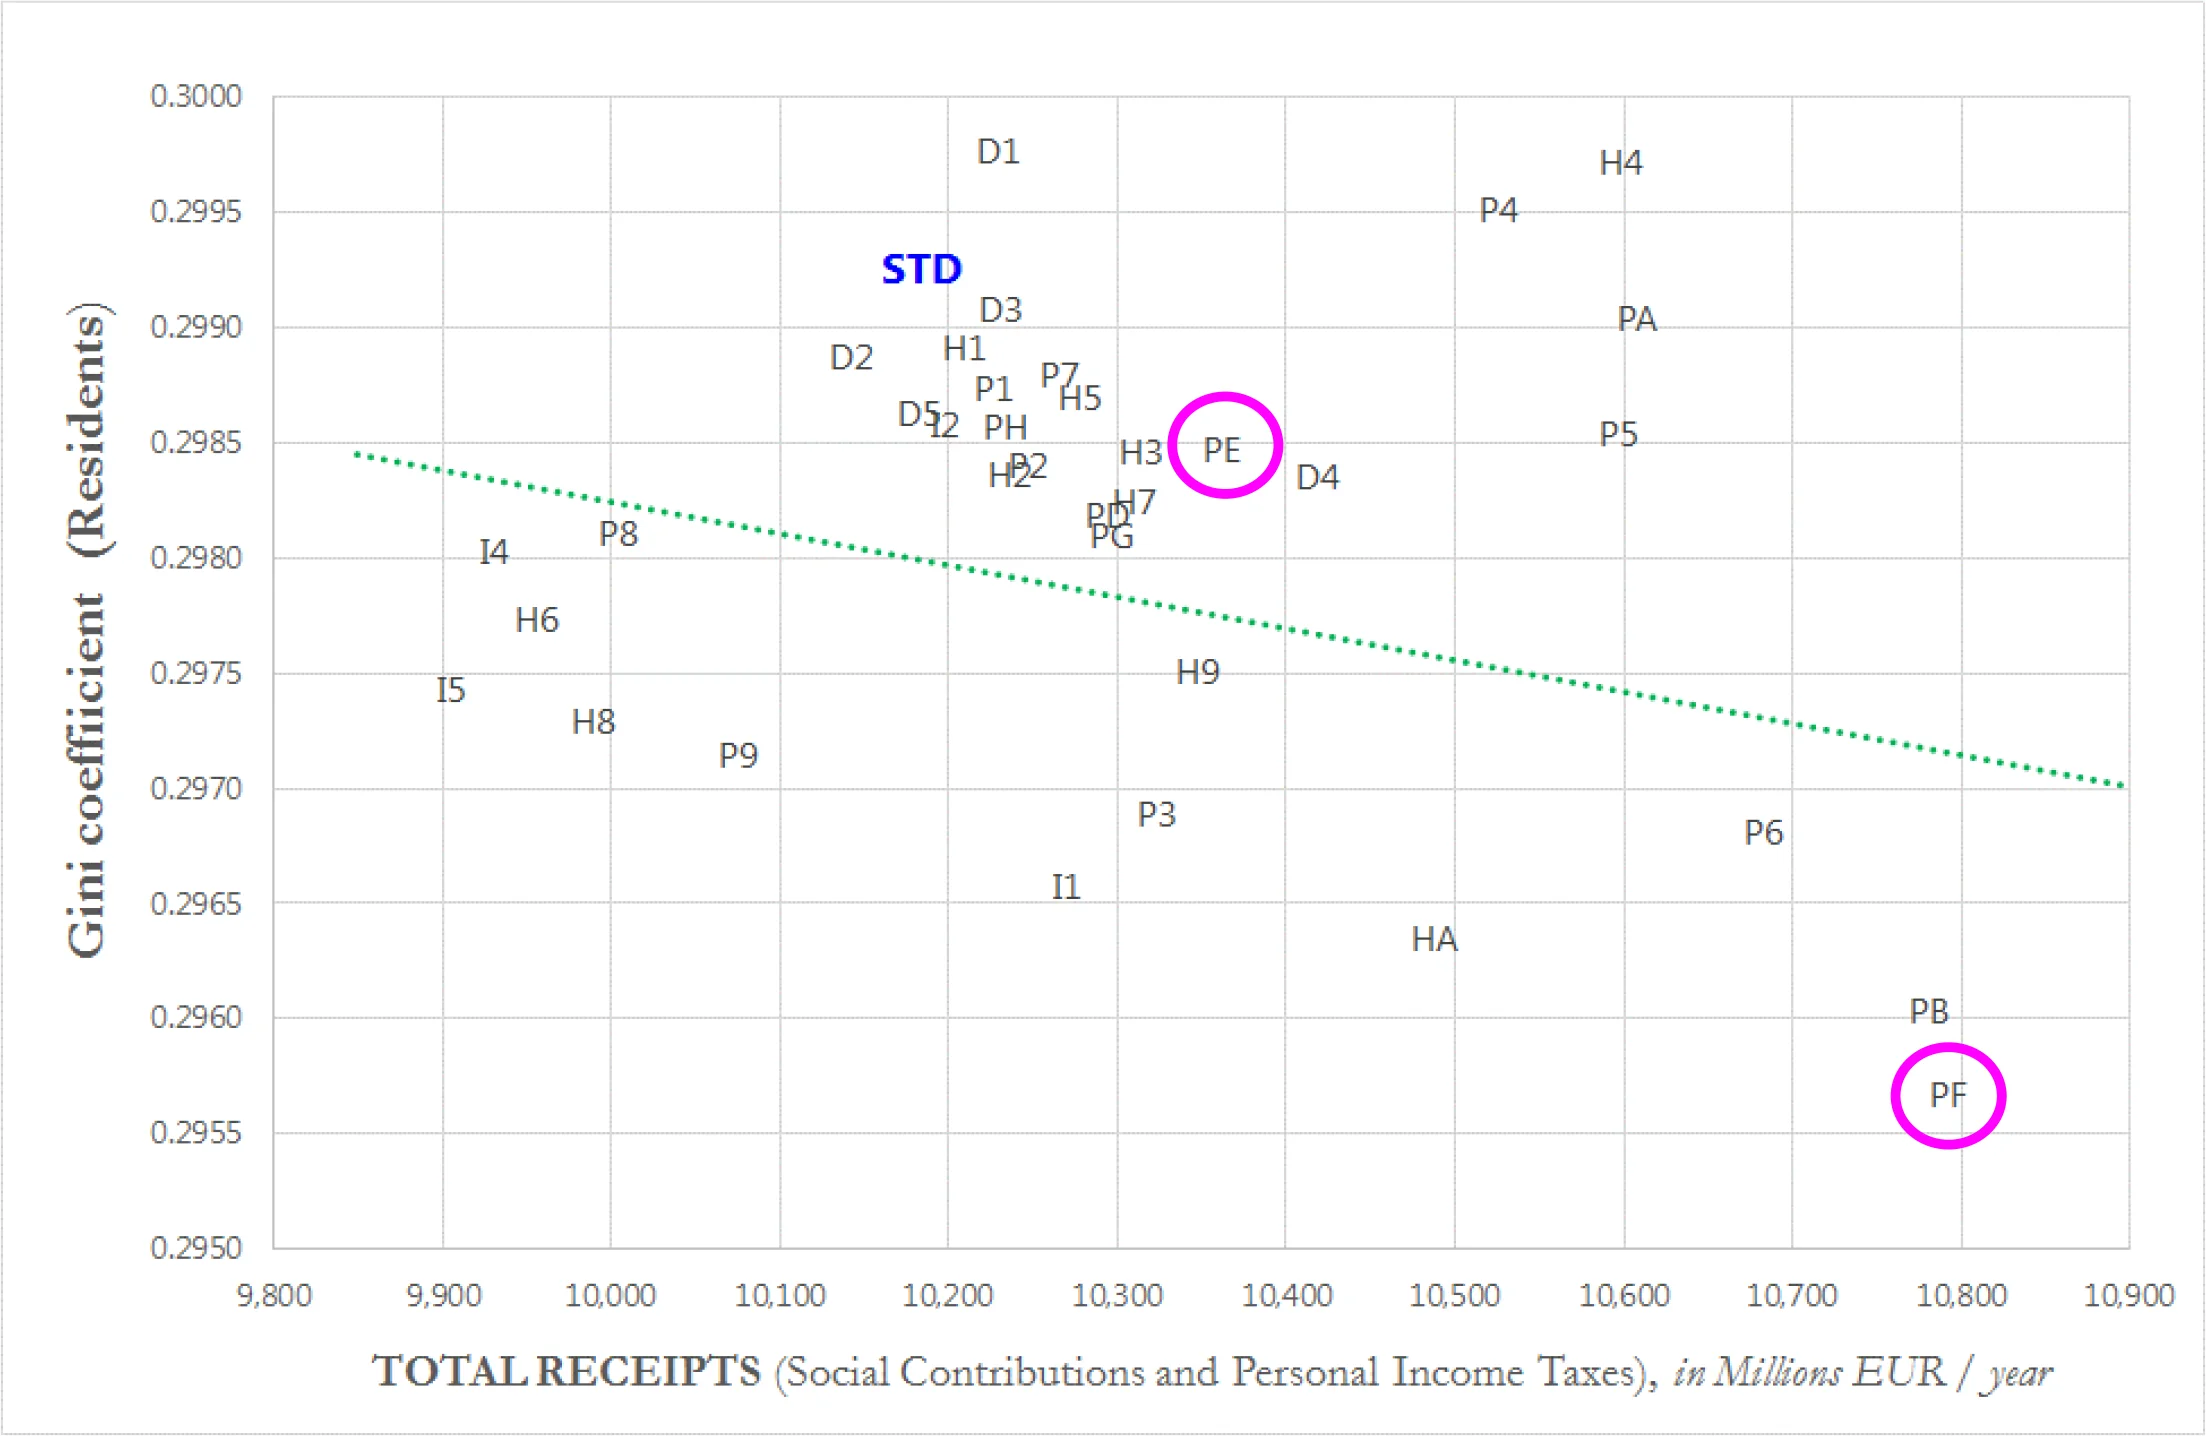
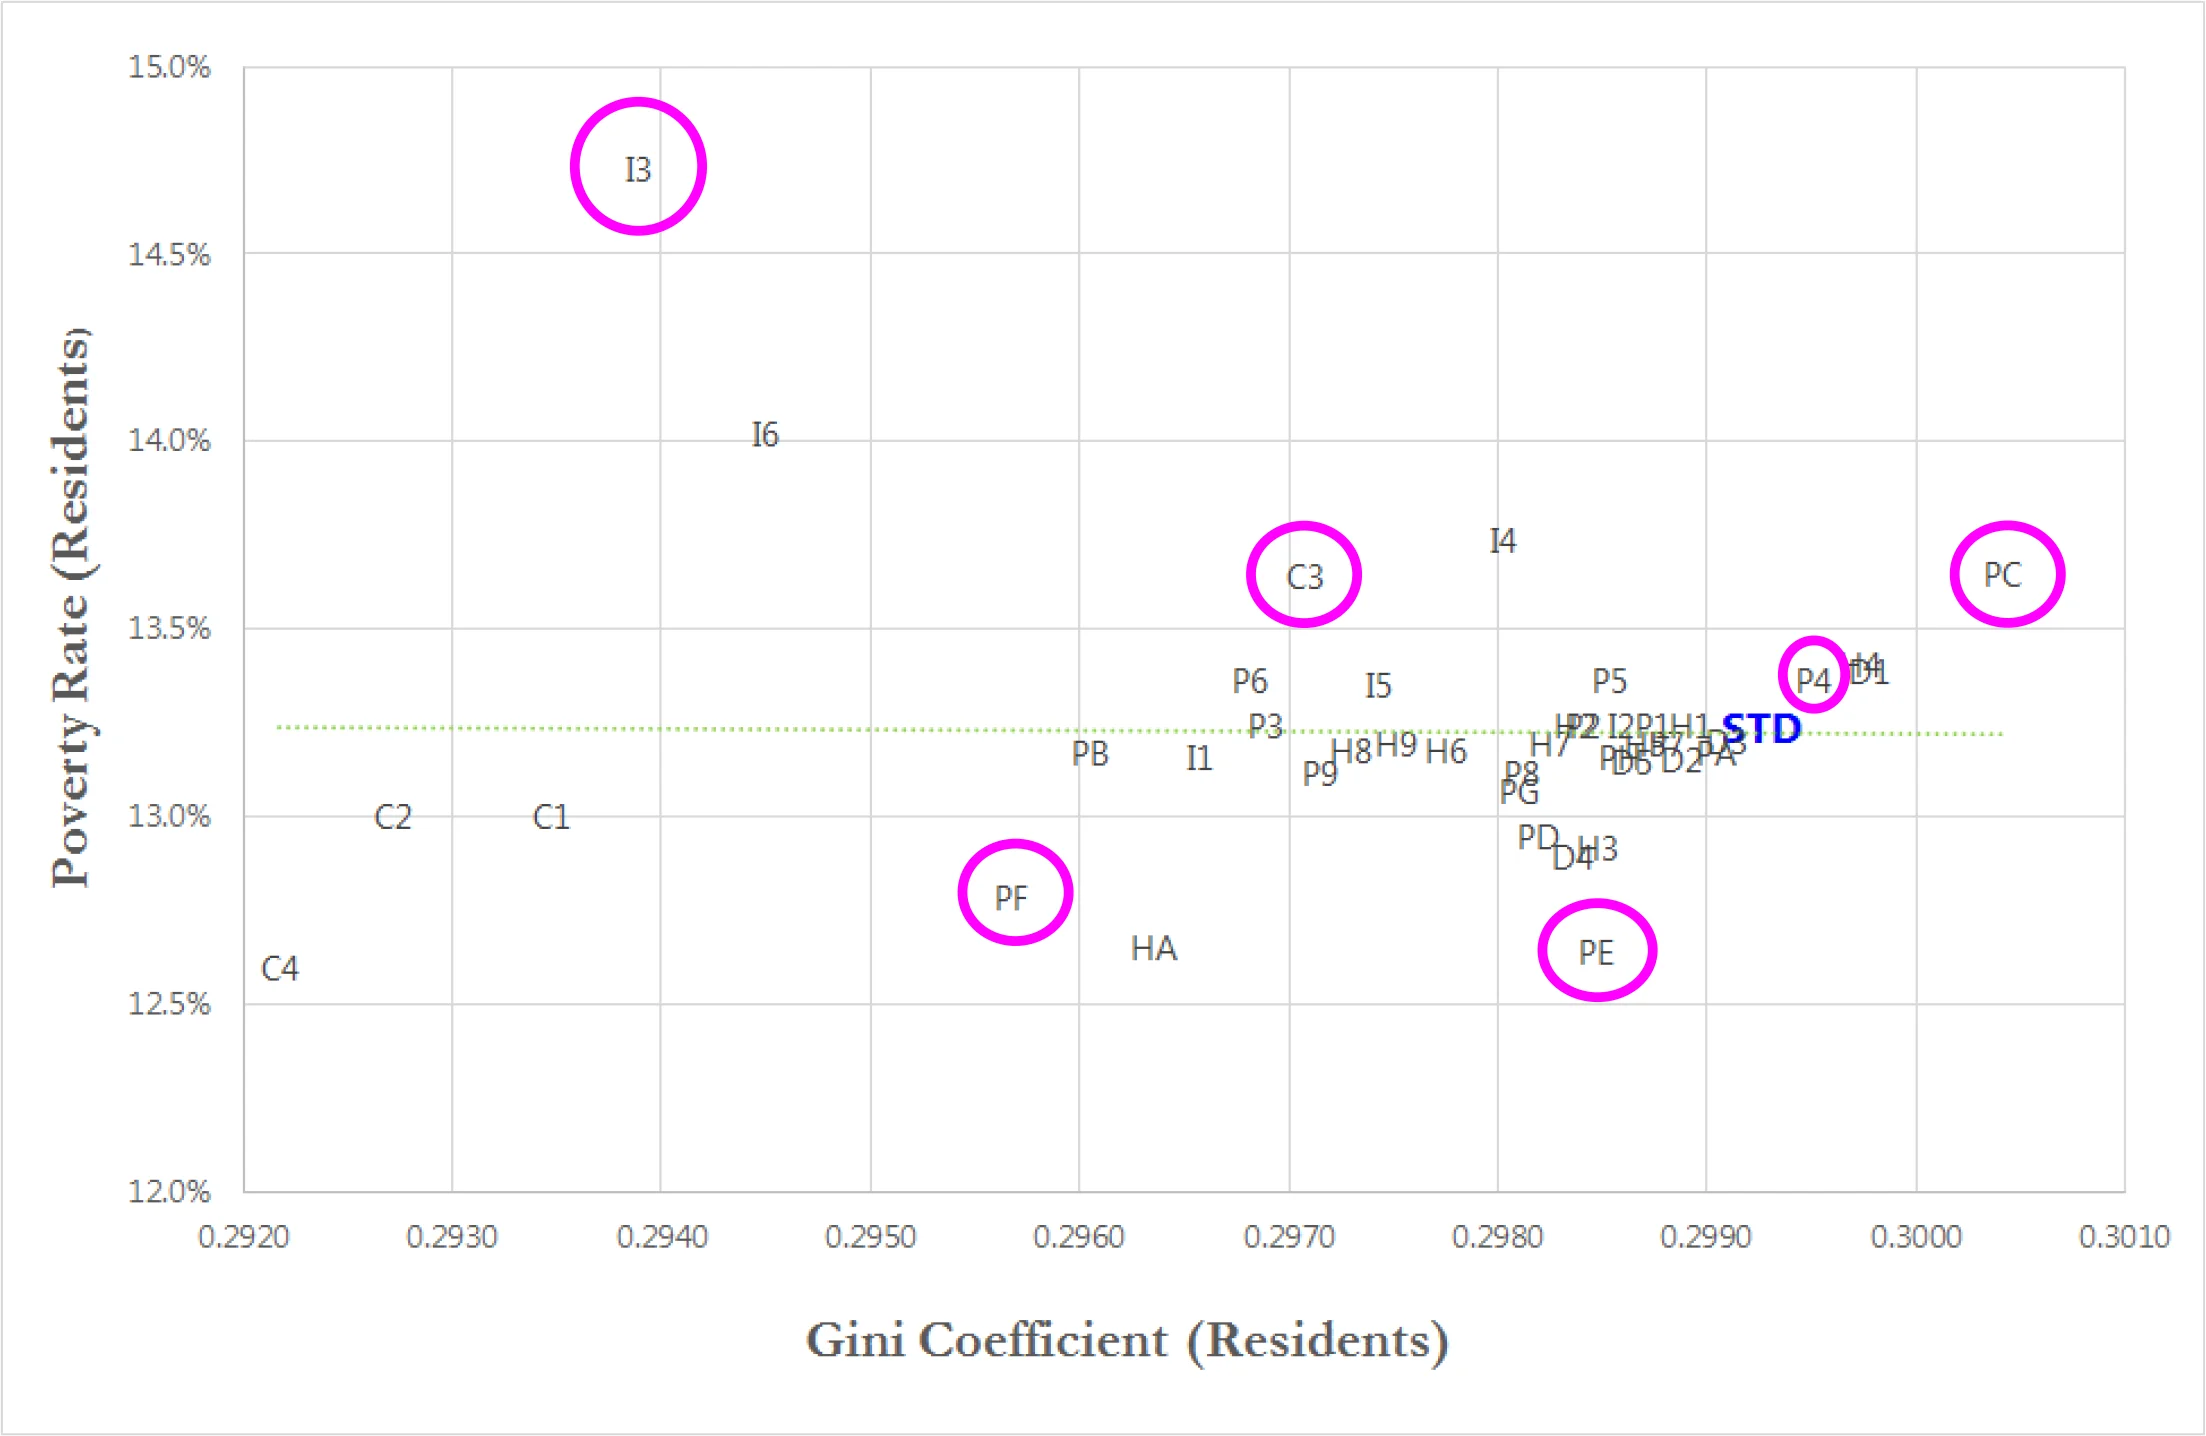
Tables
| Data and EUROMOD platforms | SILC * | HFCS-R | HFCS-XB (Active households & LU-incomes only) | ||
|---|---|---|---|---|---|
| Population covered by the survey, in persons | 574,184 | 535,897 | 418,997 | ||
| Taxable Income, before Tax allowances, in millions € / year (from tinty_s in HFCS-R, or tinty_lu_s for Active XB households) | 20,808 | 20,041 | 7,947 | ||
| … out of additional amount from XBs not covered by the survey (for subsequent macro adjustment, see Section 2.4) | 1,109 | ||||
| Public Revenue (in millions € / year) | |||||
| Social contributions | 3,914 | 3,714 | 2,030 | ||
| whose | Employee | 1,820 | 1,693 | 945 | |
| Self-employed | 178 | 221 | 27 | ||
| Others (Long term care from Social assistance) | 3 | 3 | 0 | ||
| Employers | 1,710 | 1,667 | 1,059 | ||
| Credited (Replacement income, Social assistance, Pensions) | 202 | 130 | 0 | ||
| … out of additional amount from XBs not covered by the survey (for macro adjustment) | 62 | ||||
| Personal Income Tax | 3,289 | 3,439 | 824 | ||
| Implicit Tax Rate on Tax Base (tinty_s – tinta_s, or LU versions if XBs), before Tax Credits | 20.9% | 14.4% | |||
| Global Tax Rate (after Tax Allowances & Credits) = Income Tax / Taxable Income, on average | 17.2% | 10.4% | |||
| … out of additional amount from XBs not covered by the survey (for macro adjustment) | 115 | ||||
| Þ Total Public Revenue (before macro adjustment) | 7,203 | 7,153 | 2,855 | ||
| Inequalities | If All Incomes | ||||
| Gini | |||||
| Relative = Abs / (2*Avg) | 0.2524 | 0.2993 | 0.1940 | ||
| Absolute (in € / month) | 1,701 | 2,103 | 1,088 | ||
| Average (in € / month) | 3,371 | 3,513 | 2,804 | ||
| Poverty | |||||
| Line (in € / month) | 1,790 | 1,770 | 1,564 | ||
| Rate | 11% | 13% | 2% | ||
| by Type of Residence Household: | |||||
| Single (<65) | 14% | 16% | 1% | ||
| Single (65+) | 8% | 9% | 2% | ||
| Single with dependent(s) | 31% | 18% | 0% | ||
| Couple - 0 dep | 6% | 5% | 2% | ||
| Couple - 1-2 dep | 11% | 18% | 2% | ||
| Couple - 3+ dep | 14% | 21% | 2% | ||
| "Well-being", as equivalized income (all in € / month), on average | If All Incomes | ||||
| All | 3,371 | 3,513 | 2,804 | ||
| 1st Decile | 1,574 | 1,472 | 1,635 | ||
| by Type of Residence Household: | |||||
| Single (<65) | 3,308 | 3,249 | 2,828 | ||
| Single (65+) | 3,215 | 3,440 | 2,878 | ||
| Single with dependent(s) | 2,473 | 2,661 | 2,530 | ||
| Couple - 0 dep | 3,922 | 4,150 | 3,194 | ||
| Couple - 1-2 dep | 3,117 | 3,292 | 2,768 | ||
| Couple - 3+ dep | 2,673 | 2,826 | 2,353 | ||
Source: Liégeois (2025a) Table 2
A comparison with official statistics can be found in the EUROMOD country report for Luxembourg (https://euromod-web.jrc.ec.europa.eu/resources/country-reports - Archives - I3.0+ - Annex 2: Validation tables)
| # | Underlying Policy | Ref. | Contents (all in relation with Social Contributions)* |
|---|---|---|---|
| 1 | BASELINE | STD | EUROMOD simulation of System presently in force “LU_2017_STD” |
| 2 | Dependency (Long Term Care) (target cf. health/in-kind, out of pensioners) (7% of social contributions in 2018)† | D1 | Deductibility (for the computation of social contribution base) from 0.25*MSW in STD down to 0% ‡ |
| 3 | D2 | Deductibility (for the computation of social contribution base) from 0.25*MSW up to 0.5*MSW | |
| 4 | D3 | Contribution rate increase from 1.4% in STD up to 1.6% of labor income (to roughly balance the higher deductibility above in [D2]) | |
| 5 | D4 | Contribution rate increase from 1.4% up to 2.4% | |
| 6 | D5 | [D2] + [D3]: Increase deductibility and balance it through a higher contribution rate | |
| 7 | Health care / in-kind (Social Contributions, including “credited”, for employ-ees/-ers, self-employed, replacement income, pensioners, social assistance) (29% of social contributions in 2018) † | H1 | Max threshold for the social contribution base from 5 MSW in STD to 7 MSW (see Section 2.2 and ‡) |
| 8 | H2 | No threshold for the social contribution base (NB: upper bound set to 1000 MSW, practically) | |
| 9 | H3 | Reduced fiscal deductibility of social contributions: from 100% (not taxable in STD) down to 50% | |
| 10 | H4 | Social contribution rates from 2.8% in STD to 3.8% (hence +2% if employ-ees/-ers altogether) | |
| 11 | H5 | Progressivity of social contrib. rates: 2.8% (resp. 3.8%) for that part of labor income < 2 (resp. >=2) MSW | |
| 12 | H6 | Progressivity of social contrib. rates: 1.8% (resp. 3.8%) for that part of labor income < 2 (resp. >=2) * MSW | |
| 13 | H7 | [H5] + [H1]: Progressivity (2.8%/3.8%) and max threshold to 7 MSW | |
| 14 | H8 | [H6] + [H1]: Progressivity (1.8%/3.8%) and max threshold to 7 MSW | |
| 15 | H9 | [H5] + [H2]: Progressiv. (2.8%/3.8%) and no threshold | |
| 16 | HA | [H5] + [H2] + [H3]: Progressivity (2.8%/3.8%), no threshold and fiscal deductibility to 50% only |
For details about “STD” and reference parameters or policies, refer to Islam et al. (2020).
Source: EUROMOD Country Report for LU, Y12 (2018-2021), Table 4.8 (page 73), Employee / Self-employed, Employer and Credited contributions, from External sources and for Residents only.
Minimum Social Wage (MSW, Section 2.2): 1.998,59 EUR/month as on 1 January 2017. In STD, 25% of this amount is deducted from the social contribution base (gross labor income) before deriving social contributions (some % of the base).
| # | Underlying Policy | Ref. | Contents (all in relation with Social Contributions)* |
|---|---|---|---|
| 17 | Pensions (Social Contributions, including “credited”, for employ-ees/ers, self-employed, replacement income) (60% of social contributions in 2018) Source: cf. [***] in Table 2 | P1 | Max threshold for the social contribution base from 5 MSW in STD to 6 MSW† |
| 18 | P2 | Max threshold from 5 MSW to 7 MSW | |
| 19 | P3 | No threshold for the social contribution base (NB: upper bound set to 1000 MSW, practically) | |
| 20 | P4 | Social contribution rate from 8% in STD to 9% both for employees and employers (hence +2% altogether) | |
| 21 | P5 | [P4] + [P2]: Rate from 8% to 9% and max threshold to 7 MSW | |
| 22 | P6 | [P4] + [P3]: Rate from 8% to 9% and no threshold | |
| 23 | P7 | Progressivity of social contribution rates: 8% (resp. 9%) for that part of labor income < 2 (resp. >=2) * MSW | |
| 24 | P8 | Progressivity: 7% (resp. 9%) for that part of labor income < 2 (resp. >=2) MSW | |
| 25 | P9 | [P8] + [P2]: Progressivity (7% and 9%) and max threshold for the social contribution base to 7 MSW | |
| 26 | PA | Progressivity: 9% (resp. 10%) for that part of labor income < 2 (resp. >=2) * MSW | |
| 27 | PB | [PA] + [P3]: Progressivity : 9% (resp. 10%) and no threshold | |
| 28 | PC | Social contribution rate from 8% to 12% for employees/-ers | |
| 29 | PD | CSV: cf. [P1] +Contribution Solidarité Vieillesse / CSV: 5% flat rate with the Minimum Pension (“MP” = 1771.75 €/month in 2017) deducted from the contribution base (pension income) at individual level ; no deductibility from income tax base & No Threshold for CSV | |
| 30 | PE | CSV: cf. [PD], but 25% of MP deducted from the contribution base (pension income) only | |
| 31 | PF | CSV: [PD] + [P6] (social contribution rate to 9% and no max threshold) | |
| 32 | PG | CSV: cf. [PD], hence [P1], but Proportional Tax for CSV (flat, but increasing with class of pension income): 0% if social contrib. base <= MP, 1.4% if base in ]MP, 2*MP], 2.8% if base in ]2*MP, 3*MP] and 4.2% if base > 3*MP | |
| 33 | PH | CSV: cf. [PD], hence [P1], but Progressive Tax for CSV (cf. Income tax), same rates and limits as in PG |
For details about parameters or policies in our benchmark “STD”, refer to Islam et al. (2020).
Minimum Social Wage (MSW, Section 2.2): 1.998,59 EUR/month as on 1 January 2017.
| # | Underlying Policy | Ref. | Contents (all in relation with Income Taxes)* |
|---|---|---|---|
| 34 | Personal Income Taxes (Tax schedule) (equivalent to 86% of social contributions in 2018) Source: cf. [***] in Table 2 | I1 | Brackets unchanged but higher Rates for higher Brackets: 45.897 € and more (40%, rather than 39% in STD), then 42% (40% in STD), 44% (41% in STD) and 46% for higher brackets (42% in STD) |
| 35 | I2 | More higher brackets and higher Rates: 39% up to 100.000 € (100 K), 40% up to 150 K, 41% up to 200 K -up to here as in STD-, then 42% up to 300 K, 44% up to 400 K, 46% up to 500 K, 48% up to 600 K, 50% up to 700 K, 52% up to 800 K, 54% up to 1000 K and 56% over 1000 K | |
| 36 | I3 | Idem [I1] but “class-1a” (Section 2.2) dropped and merged to class-2 | |
| 37 | I4 | Lower Rates for lower (unchanged) brackets: 0%, 2%, 4%, 6%, 8%, 10%, 12%, 14% and 17% respectively for the 9 first tax brackets (0%, 8%, 9%, 10%, 11%, 12%, 14%, 16% and 18% in STD), then unchanged compared to STD | |
| 38 | I5 | Enlargement of lower Brackets (Rates unchanged): 0 € ; 16,000 € ; 17,000 € ; 18,000 € ; 19,000 € and [20,000 € – 20,625 €] for the 6th bracket (0 € ; 11,265 € ; 13,137 € ; 15,009 € ; 16,881 € and [18,753 € - 29,625 €] in STD) | |
| 39 | I6 | All combined [I1] + [I4] + [I5]: higher Rates for higher Brackets and enlargement of lower Brackets (with lower Rates) |
For details about our benchmark “STD” and reference parameters or policies, refer to Islam et al. (2020).
| # | Combined Policy | Ref. | Contents | Remarks |
|---|---|---|---|---|
| 40 | Combination of policies to target an additional funding of 2.77 billion € / year (EUROMOD-base) | C1 | [P6] + ([H2] + [H4]) +([D1] + [D4]) + I1 | “C” (as first letter) for “Combination” of policies, here based on all maximally funding tracks through Pensions (without CSV), Health, Dependency and Income tax Reminder: [P6] = social contribution rate from 8% to 9% & no threshold / [PB] = progressivity 9% and 10% & no threshold / [PC] = 8% to 12% with threshold (5 MSW) |
| 41 | C2 | [PB] + ([H2] + [H4]) +([D1] + [D4]) + I1 | ||
| 42 | C3 | [PC] + ([H2] + [H4]) +([D1] + [D4]) + I1 | ||
| 43 | C4 | [C1] + [PG] | Social contribution rate for pensions from 8% to 9%, no threshold and CSV with proportional rate (hence flat, but increasing with the class of income) |
| Basic Indicator considered ß | C1-C4 ß | Min | Max | STD | |||
|---|---|---|---|---|---|---|---|
| IMIN * | Alternative | IMAX [**] | Alternative | ISTD | Normalized index iSTD (if Cx included) * | ||
| Gini coefficient(residents) | Included | 0.2922 | C4 | 0.3004 | PC | 0.2993 | 0.138 * |
| Excluded | 0.2939 | I3 | |||||
| Poverty Rate(residents) | Included | 12.6% | C4 | 14.7% | I3 | 13.2% | 0.697 |
| Excluded | 12.6% | PE | |||||
| Total Receipts for Luxembourg(in millions €/year) | Included | 9,849 | I6 | 12,432 | C3 | 10,185 | 0.130 |
| Excluded | 11,558 | PC | |||||
See Section 4.2 - The Gini normalized value gSTD directly computed from this table = (0.3004 – 0.2993) / (0.3004 - 0.2922) = 0.134 is slightly deviating from the “effective” value 0.138 mentioned in the table, due to rounding effects
| Criteria and Main values | If considering the combined alternatives C1-C4 (see also Table B1) | If excluding C1-C4 (see also Table B2) |
|---|---|---|
| Total Receipts (social contributions + personal income taxes ; residents + XBs) [Min: 8,849 - STD : 10,185 - Max : 12,432], in million € / year | C3: best C4: 2nd best I6: the worst alternative (but that can also be shown as the best for well-being) | PC: best PF: 2nd best |
| Poverty rate among Residents (proportion of persons under 60% of the median equivalent income) [Min: 12.6% - STD: 13.2% - Max: 14.7%] | C4: best PE: 2nd best | PE: best HA: 2nd best |
| Gini inequality coefficient among residents (mean absolute equivalent income gap divided by twice the average equivalent income) [Min: 0.2922 - STD : 0.2993 - Max : 0.3004] | C4: best C2: 2nd best | I3: best I6: 2nd best |
| General Performance Index (GPI) | C4: best balanced (if weights = 0.3/Gini, 0.3/poverty, 0.4/receipts) C2: 2nd best balanced | PF: best balanced (if weights = 0.3/Gini, 0.3/poverty, 0.4/receipts) HA: 2nd best balanced |
| Correlations | Total Receipts | Receipts from Residents | Receipts from XBs | GINI Residents | POVERTY Residents | POVERTY - Single Resident Households with Dependents | WELL-BEING Residents | GINI XBs | POVERTY XBs | WELL-BEING XBs |
|---|---|---|---|---|---|---|---|---|---|---|
| Total Receipts | 1.00 | |||||||||
| Receipts from Residents | 1.00 | 1.00 | ||||||||
| Receipts from XBs | 0.99 | 0.97 | 1.00 | |||||||
| GINI Residents | -0.40 | -0.45 | -0.26 | 1.00 | ||||||
| POVERTY Residents | -0.11 | -0.14 | -0.05 | -0.01 | 1.00 | |||||
| POVERTY - Single Resident Households with Dependents | -0.21 | -0.23 | -0.16 | -0.08 | 0.82 | 1.00 | ||||
| WELL-BEING Residents | -0.97 | -0.98 | -0.93 | 0.49 | 0.23 | 0.33 | 1.00 | |||
| GINI XBs | -0.42 | -0.44 | -0.35 | 0.68 | 0.19 | -0.07 | 0.44 | 1.00 | ||
| POVERTY XBs | -0.81 | -0.79 | -0.82 | 0.10 | 0.41 | 0.47 | 0.81 | 0.38 | 1.00 | |
| WELL-BEING XBs | -0.98 | -0.97 | -0.98 | 0.28 | 0.16 | 0.30 | 0.96 | 0.35 | 0.87 | 1.00 |
Note to the reader: the correlations refer to the outcomes for all (43) alternatives ; indicators referring to XBs are shown in blue fonts (these refer to the populations covered by the HFCS-XB survey, out of the (total) Receipts from XBs which are macro-adjusted for “non-active” XB households).
| p.m. RECEIPTS (in millions €/year) (Min: 9,849 - Max : 12,432) | ||||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| GINI (Min: 0.2922 - Max : 0.3004) a ß | POVERTY / b Þ (Min: 12.6% - Max: 14.7%) | 0 | 0.3 | 0.6 | 1 | |||||||||
| Best Systems, "Cx" INCLUDED | 1st Best | 2nd Best | 3rd Best | 1st Best | 2nd Best | 3rd Best | 1st Best | 2nd Best | 3rd Best | 1st Best | 2nd Best | 3rd Best | ||
| 0 | INDIC | STD | C3 | C4 | C2 | C3 | C4 | C2 | C4 | C2 | C1 | C4 | PE | HA |
| REC | 10,185 | 12,432 | 11,670 | 11,655 | 12,432 | 11,670 | 11,655 | 11,670 | 11,655 | 11,557 | 11,670 | 10,361 | 10,488 | |
| GINI_R | 0.2993 | 0.2971 | 0.2922 | 0.2927 | 0.2971 | 0.2922 | 0.2927 | 0.2922 | 0.2927 | 0.2935 | 0.2922 | 0.2985 | 0.2964 | |
| POV_R | 13.2% | 13.6% | 12.6% | 13.0% | 13.6% | 12.6% | 13.0% | 12.6% | 13.0% | 13.0% | 12.6% | 12.6% | 12.7% | |
| 0.3 | INDIC | STD | C3 | C4 | C2 | C4 | C2 | C1 | C4 | C2 | C1 | |||
| REC | 10,185 | 12,432 | 11,670 | 11,655 | 11,670 | 11,655 | 11,557 | 11,670 | 11,655 | 11,557 | ||||
| GINI_R | 0.2993 | 0.2971 | 0.2922 | 0.2927 | 0.2922 | 0.2927 | 0.2935 | 0.2922 | 0.2927 | 0.2935 | ||||
| POV_R | 13.2% | 13.6% | 12.6% | 13.0% | 12.6% | 13.0% | 13.0% | 12.6% | 13.0% | 13.0% | ||||
| 0.6 | INDIC | STD | C4 | C2 | C1 | C4 | C2 | C1 | ||||||
| REC | 10,185 | 11,670 | 11,655 | 11,557 | 11,670 | 11,655 | 11,557 | |||||||
| GINI_R | 0.2993 | 0.2922 | 0.2927 | 0.2935 | 0.2922 | 0.2927 | 0.2935 | |||||||
| POV_R | 13.2% | 12.6% | 13.0% | 13.0% | 12.6% | 13.0% | 13.0% | |||||||
| 1 | INDIC | STD | C4 | C2 | C1 | |||||||||
| REC | 10,185 | 11,670 | 11,655 | 11,557 | ||||||||||
| GINI_R | 0.2993 | 0.2922 | 0.2927 | 0.2935 | ||||||||||
| POV_R | 13.2% | 12.6% | 13.0% | 13.0% | ||||||||||
| p.m. RECEIPTS (in millions €/year) (Min: 9,849 - Max : 11,558) | ||||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| GINI (Min: 0.2939 - Max : 0.3004) a ß | POVERTY / b (Min: 12.6% - Max: 14.7%) | 0 | 0.3 | 0.6 | 1 | |||||||||
| Best Systems, “CX” EXCLUDED | 1st Best | 2nd Best | 3rd Best | 1st Best | 2nd Best | 3rd Best | 1st Best | 2nd Best | 3rd Best | 1st Best | 2nd Best | 3rd Best | ||
| 0 | INDIC | STD | PC | PF | PB | PC | PF | PB | PF | HA | PE | PE | HA | PF |
| REC | 10,185 | 11,558 | 10,793 | 10,782 | 11,558 | 10,793 | 10,782 | 10,793 | 10,488 | 10,361 | 10,361 | 10,488 | 10,793 | |
| GINI_R | 0.2993 | 0.3004 | 0.2957 | 0.2960 | 0.3004 | 0.2957 | 0.2960 | 0.2957 | 0.2964 | 0.2985 | 0.2985 | 0.2964 | 0.2957 | |
| POV_R | 13.2% | 13.7% | 12.8% | 13.2% | 13.7% | 12.8% | 13.2% | 12.8% | 12.7% | 12.6% | 12.6% | 12.7% | 12.8% | |
| 0.3 | INDIC | STD | PC | PF | PB | PF | HA | PB | HA | PF | PE | |||
| REC | 10,185 | 11,558 | 10,793 | 10,782 | 10,793 | 10,488 | 10,782 | 10,488 | 10,793 | 10,361 | ||||
| GINI_R | 0.2993 | 0.3004 | 0.2957 | 0.2960 | 0.2957 | 0.2964 | 0.2960 | 0.2964 | 0.2957 | 0.2985 | ||||
| POV_R | 13.2% | 13.7% | 12.8% | 13.2% | 12.8% | 12.7% | 13.2% | 12.7% | 12.8% | 12.6% | ||||
| 0.6 | INDIC | STD | I3 | PF | PB | PF | HA | PB | ||||||
| REC | 10,185 | 10,221 | 10,793 | 10,782 | 10,793 | 10,488 | 10,782 | |||||||
| GINI_R | 0.2993 | 0.2939 | 0.2957 | 0.2960 | 0.2957 | 0.2964 | 0.2960 | |||||||
| POV_R | 13.2% | 14.7% | 12.8% | 13.2% | 12.8% | 12.7% | 13.2% | |||||||
| 1 | INDIC | STD | I3 | I6 | PF | |||||||||
| REC | 10,185 | 10,221 | 9,849 | 10,793 | ||||||||||
| GINI_R | 0.2993 | 0.2939 | 0.2945 | 0.2957 | ||||||||||
| POV_R | 13.2% | 14.7% | 14.0% | 12.8% | ||||||||||