Taxes and benefits

Research articles · Jun 30, 2009

FiFoSiM – An integrated tax benefit microsimulation and CGE model for Germany

Andreas Peichl, Thilo Schaefer

IZA Bonn, ISER and University of Cologne, Germany; Center for Public Economics, University of Cologne, Germany

Volume 2(1) Spring 2009

Cite as: A. Peichl, T. Schaefer; 2009; FiFoSiM – An integrated tax benefit microsimulation and CGE model for Germany; International Journal of Microsimulation; 2(1); 1–15. doi: 10.34196/ijm.00008

Abstract

This paper describes FiFoSiM, the integrated tax benefit microsimulation and computable general equilibrium (CGE) model of the Center of Public Economics at the University of Cologne. FiFoSiM consists of three main parts. The first part is a static tax benefit microsimulation module. The second part adds a behavioural component to the model: an econometrically estimated labour supply model. The third module is a CGE model which allows the user of FiFoSiM to assess the global economic effects of policy measures. Two specific features distinguish FiFoSiM from other tax benefit models: First, the simultaneous use of two databases for the tax benefit module and second, the linkage of the tax benefit model to a CGE model.

This article contains 4 figures and 5 tables.

Figures

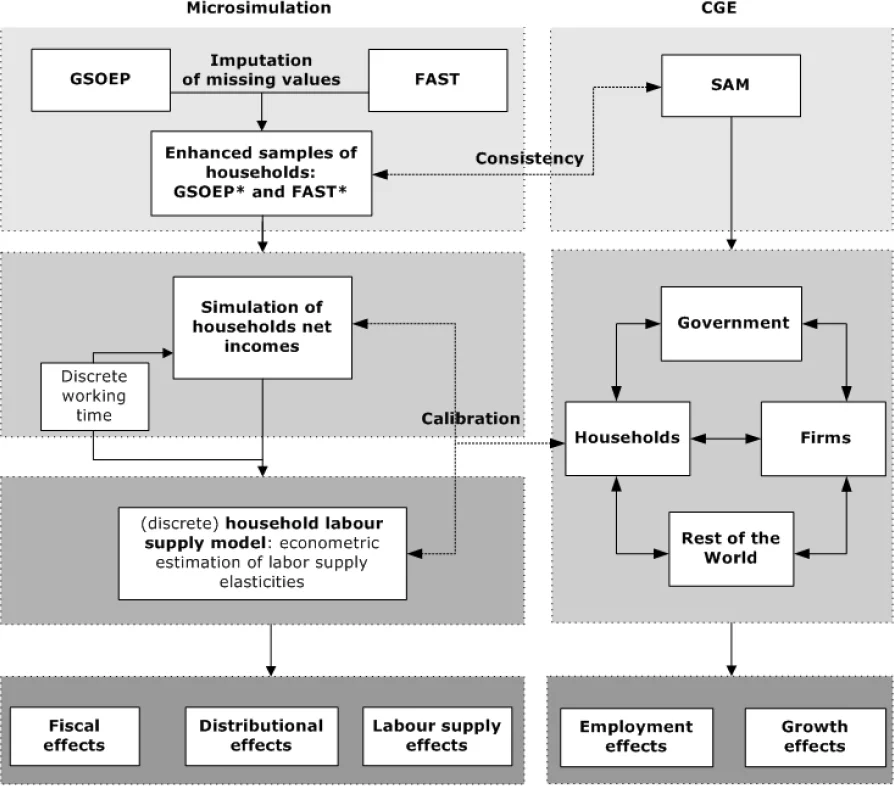
Figure 1. Basic setup of FiFoSiM.
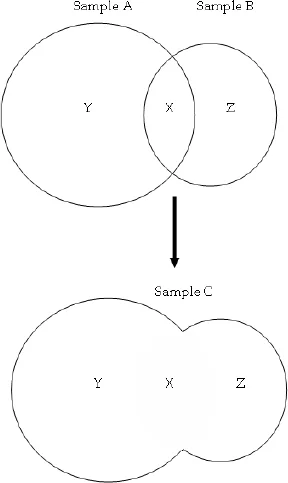
Figure 2. The basic principle of statistical matching.
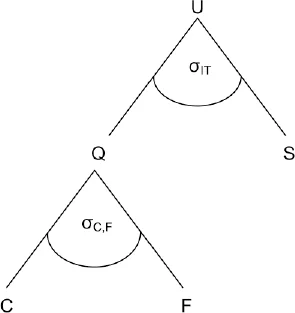
Figure 3. Nested CES utility function.
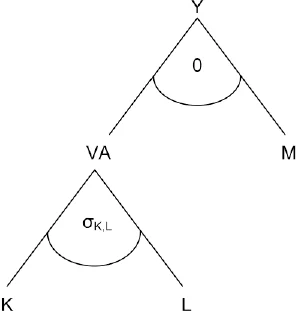
Figure 4. Structure of the nested FiFoSiM production function.

Tables

Table 1. Strength and limitations of the dual database.
Year Ref. fast fast* gsoep gsoep*
2005 181.00 178.75 181.16 185.85 180.69
2006 192.85 190.02 192.64 197.27 192.23
2006 200.67 198.71 201.46 206.51 200.30

Notes: The reference value (Ref.) is a federal government estimate of personal income tax for each year.

indicates an enhanced dataset.

Table 2. Calculation of personal income tax.
  Sum of net incomes from 7 categories (receipts from each source minus expenses)
= adjusted gross income
− deductions (social security and insurance contributions, personal expenses)
= taxable income (x)
. tax formula
= tax payment (T)
Table 3. Duration of unemployment benefit entitlement.
Old regulation until 31.01.2006 New regulation from 01.02.2006
Employment period (months) Age (Years) Benefit period (months) Employment period (months) Age (Years) Benefit period (months)
12   6 12   6
16   8 16   8
20   10 20   10
24   12 24   12
30 45 14 30 55 15
36 45 18 36 55 18
44 47 22      
52 52 26      
64 57 32      
Table 4. Fiscal effects of reform without behavioural reactions.
  Personal income tax (€ billion)
Reform phase FAST* GSOEP*
Pre-reform 181.16 180.69
Introduction 179.15 179.08
Final 168.12 166.89
Table 5. Estimated results (FAST*) of the reforms proposed by Mitschke.
  Reform phase
  Introduction Final
PIT revenue − €2 billion − €13 billion
Labour supply +103,000 +251,000
Employment +370,000 +540,000
Economic growth +1.1% +1.7%