Cite as: L. Calcagno; 2021; The Emergency Family Income (IFE) in Argentina: could it become a permanent safety net?; International Journal of Microsimulation; 14(2); 32–49. doi: 10.34196/ijm.00235
Abstract
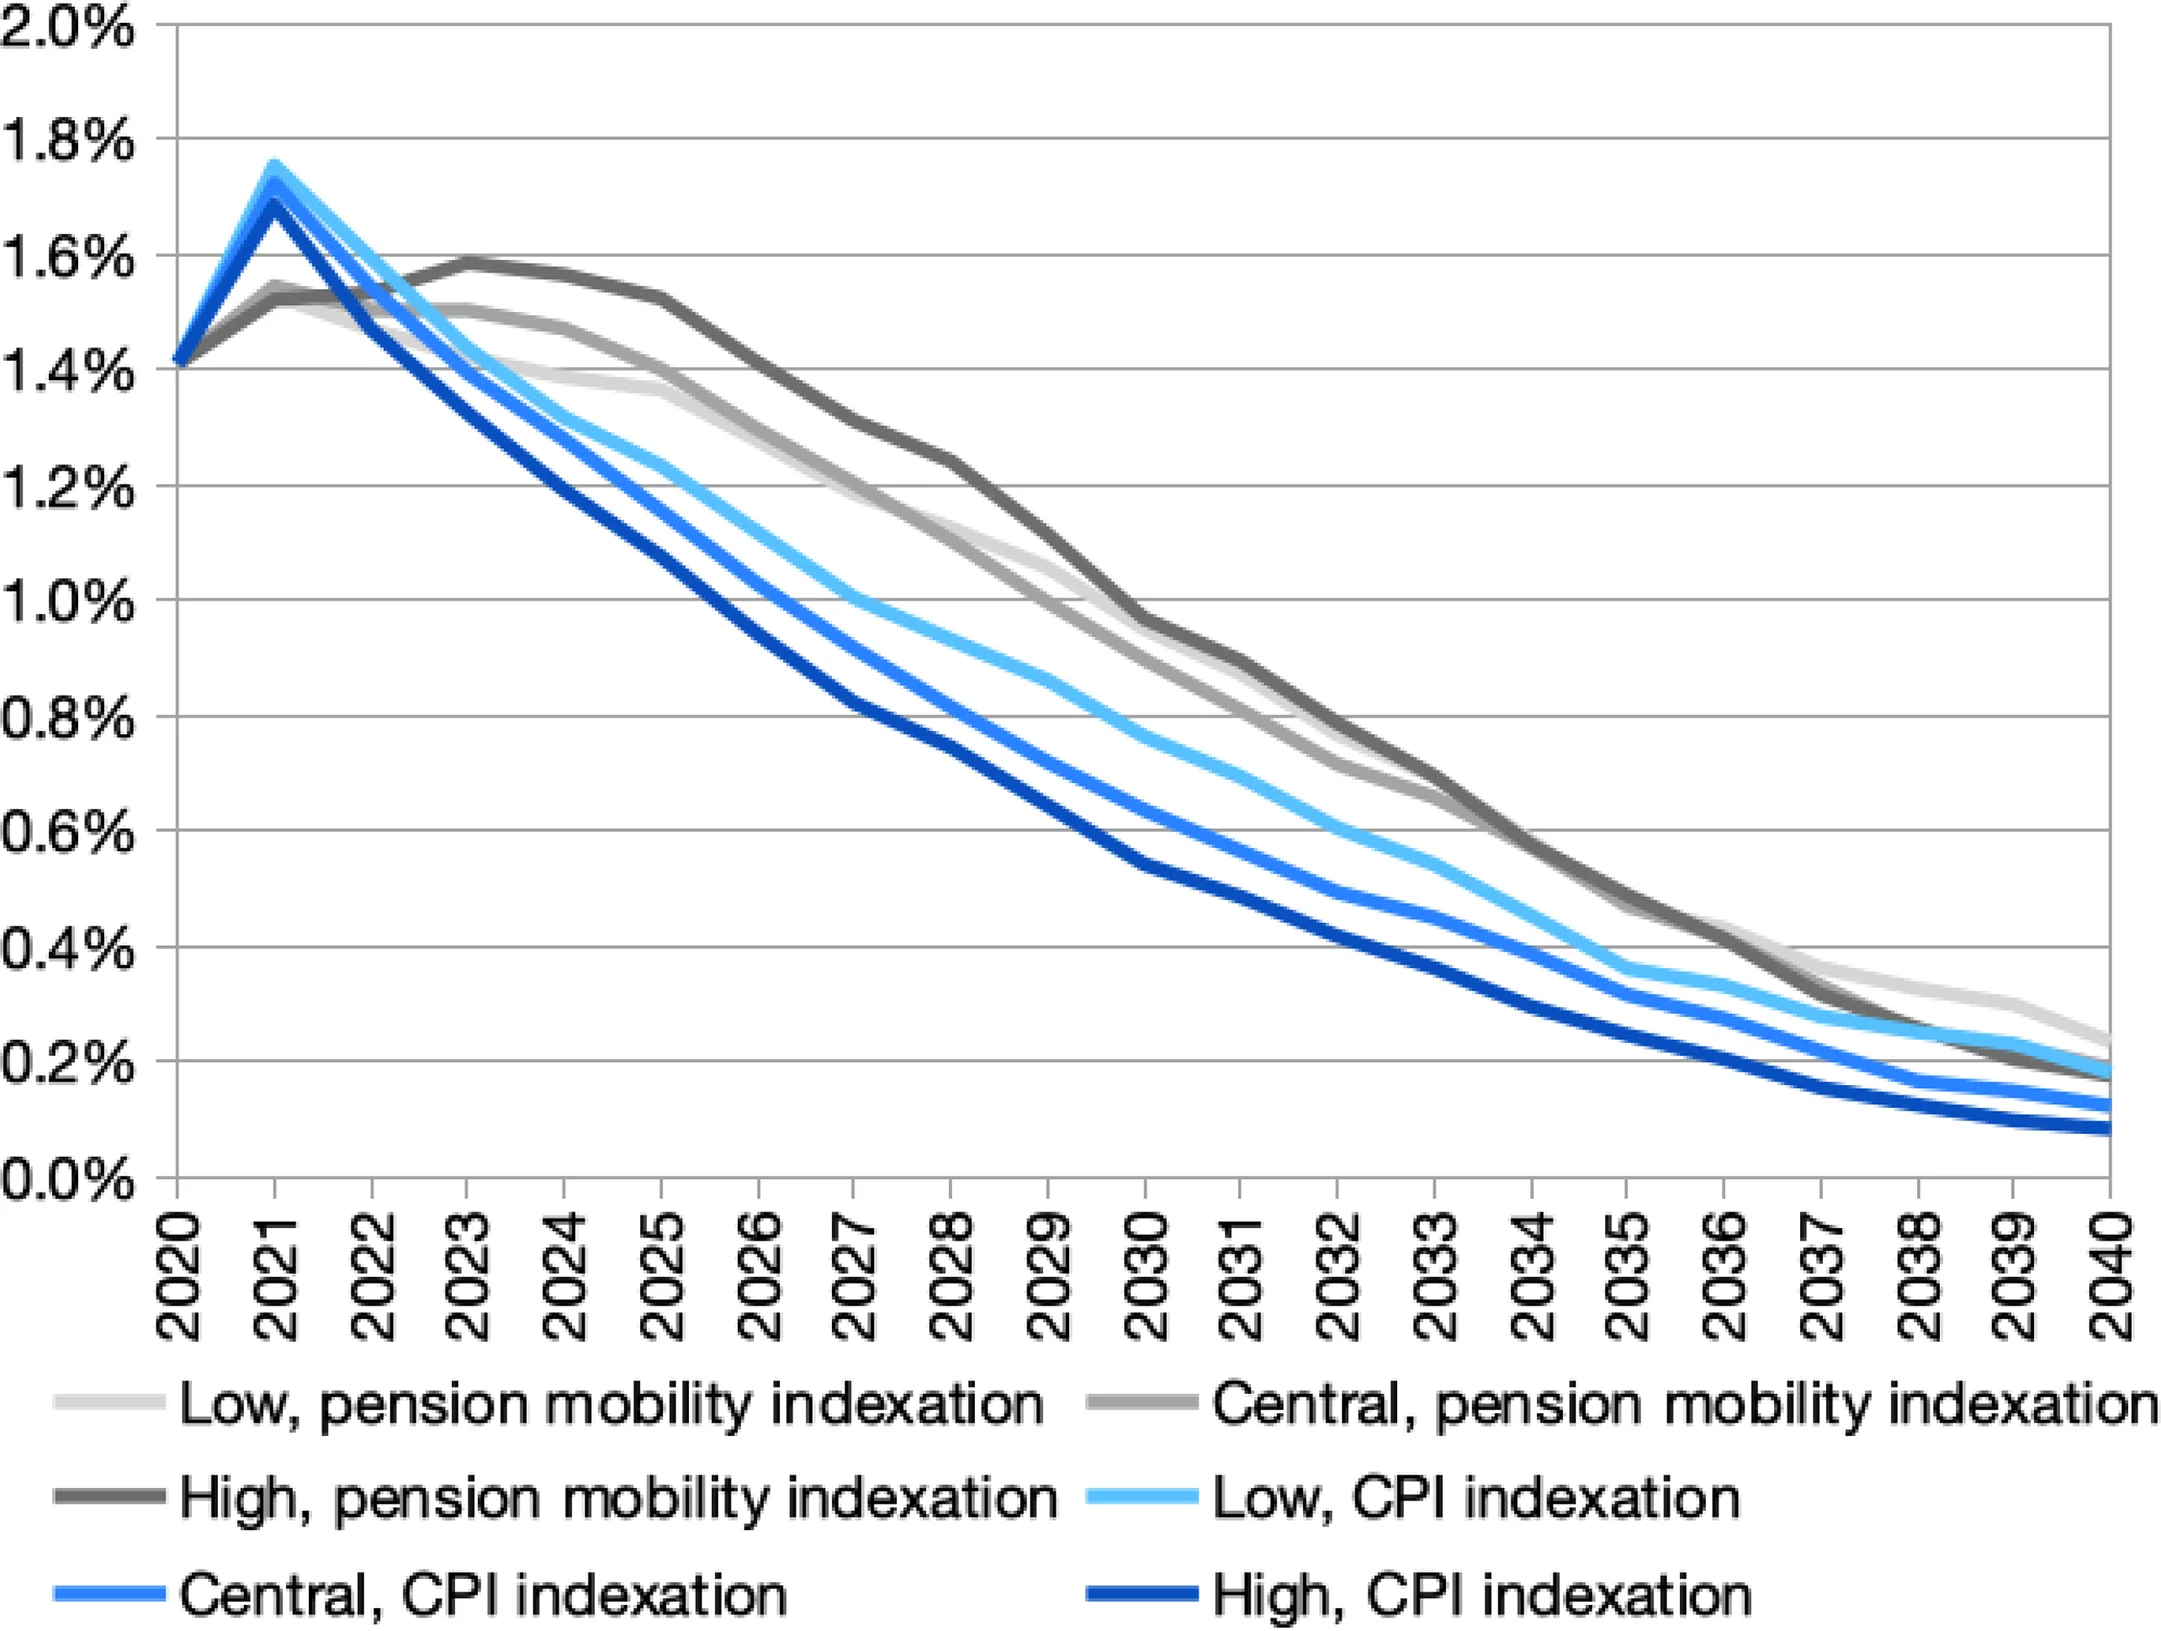
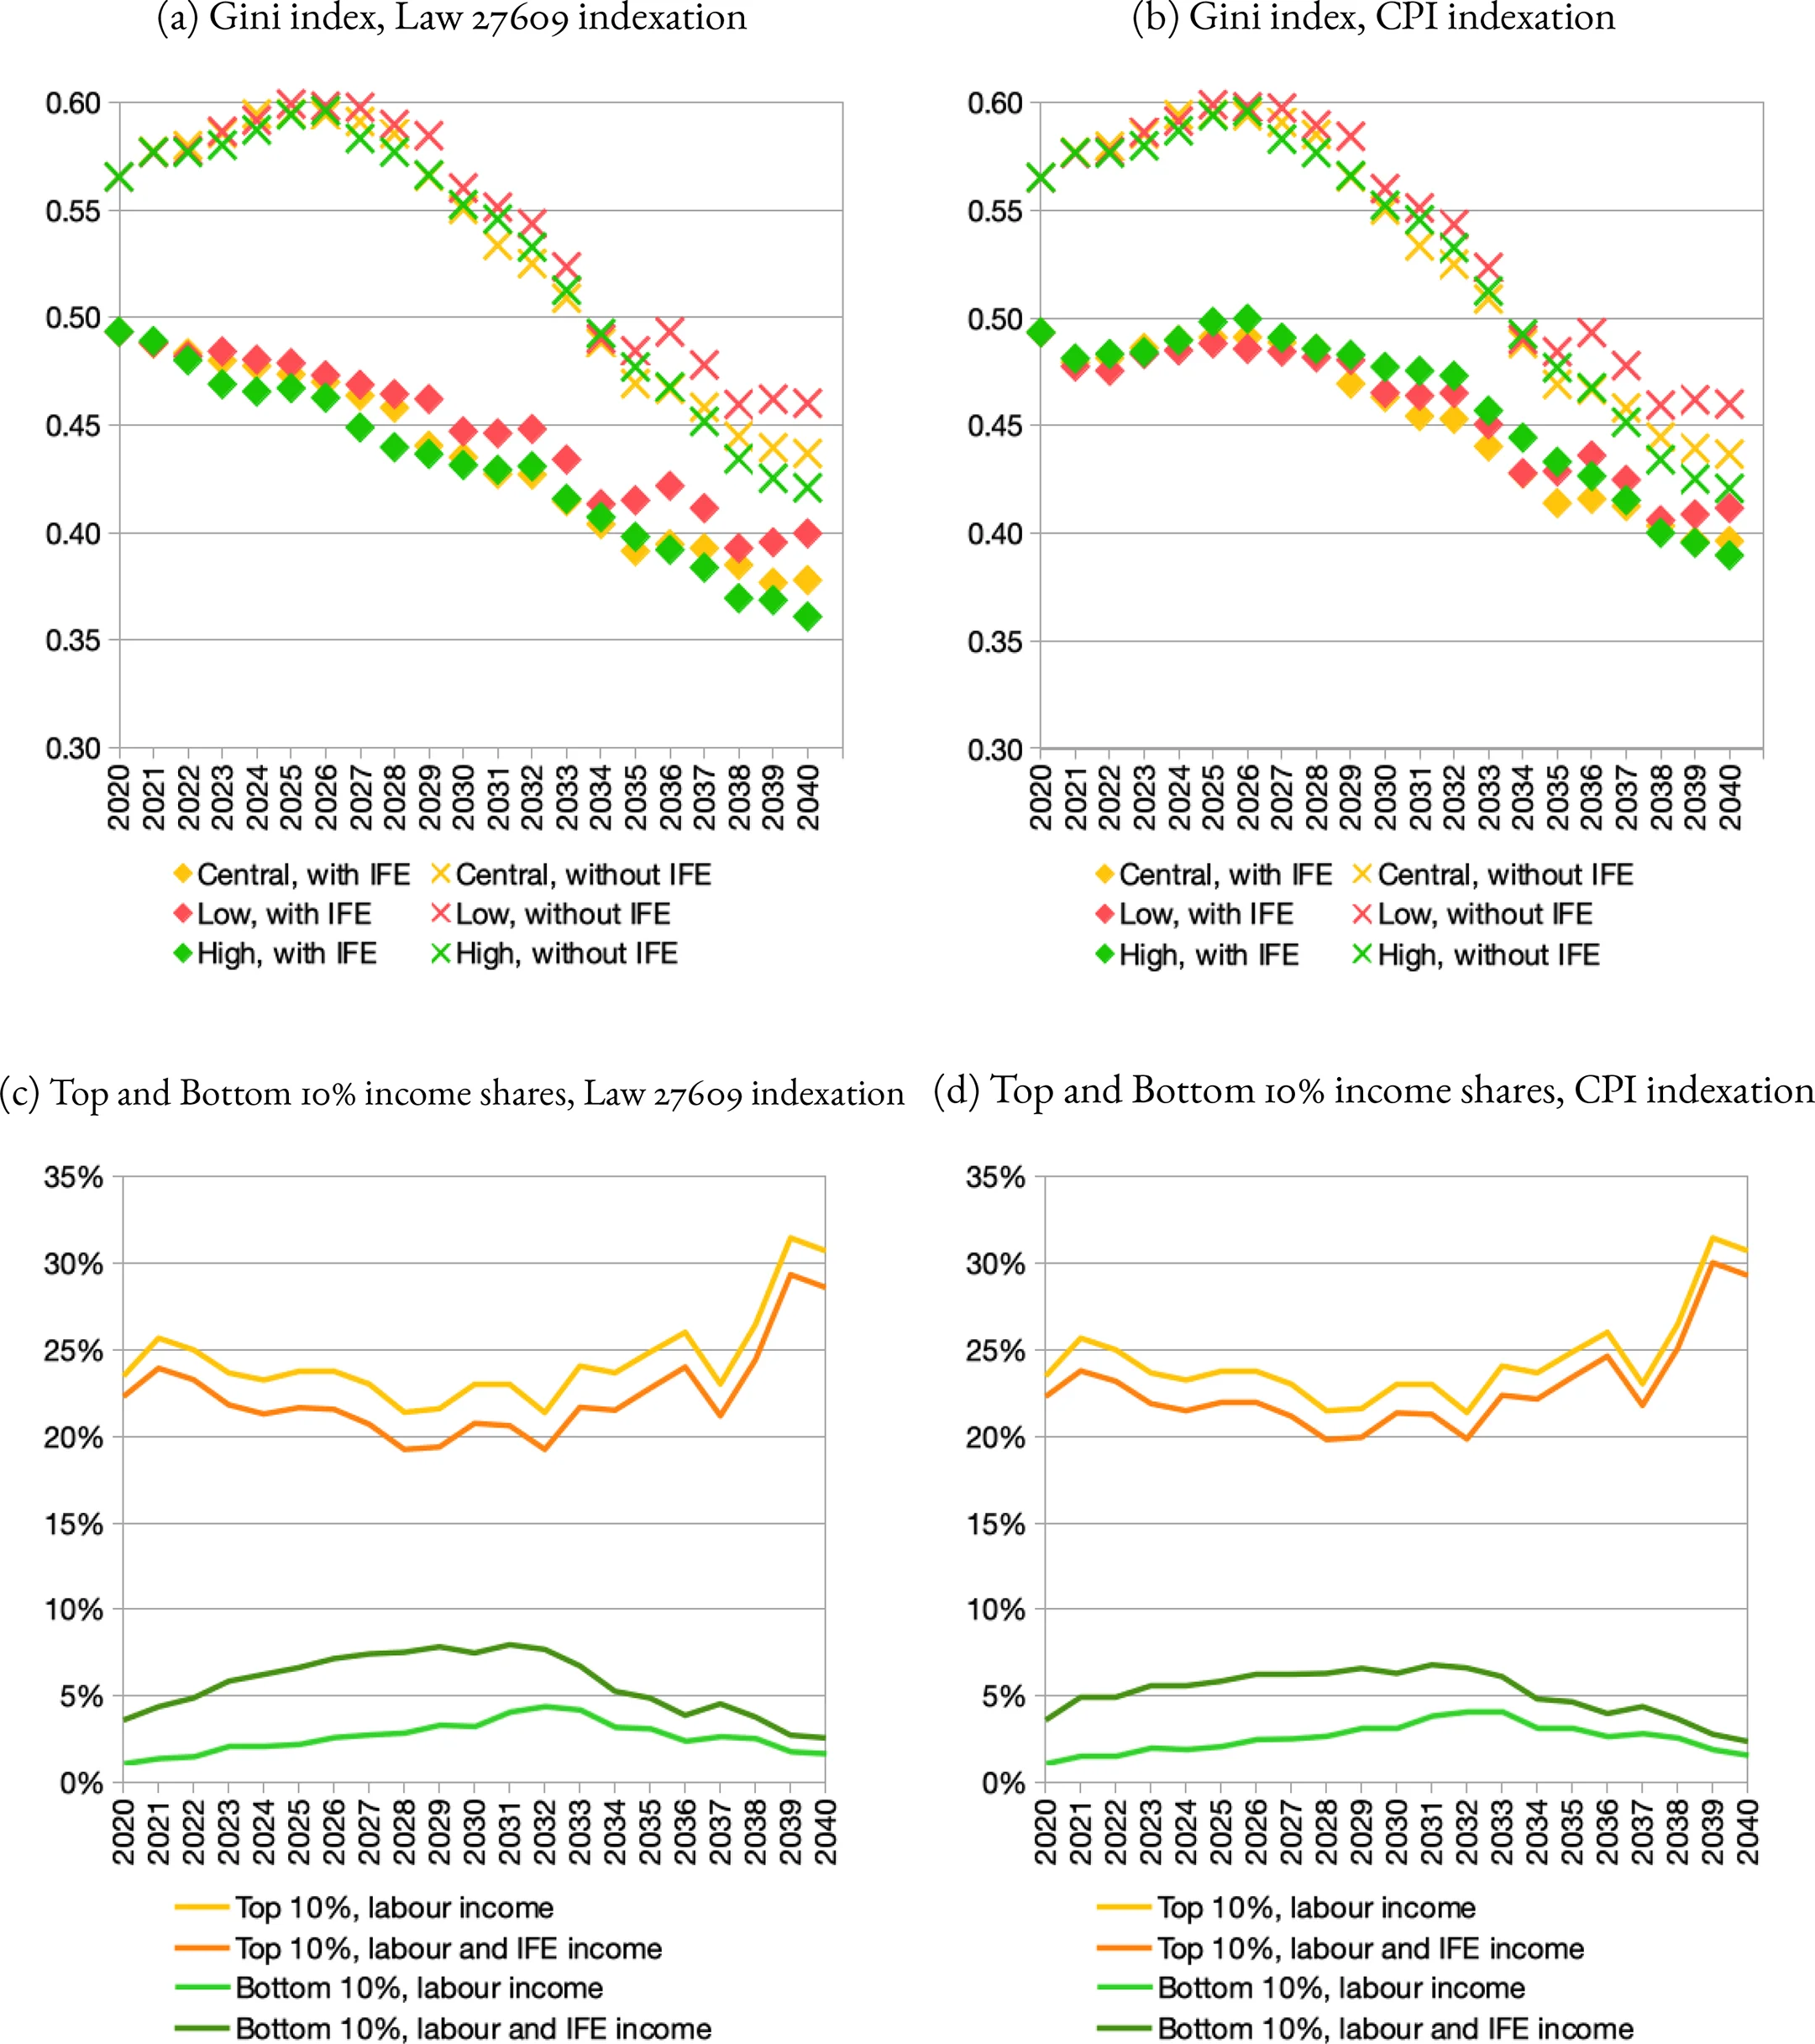
Argentina adopted an early lock-down strategy to mitigate the COVID19 pandemic in March 2020. To allow households that were out of the formal labour market to abide by the lock-down, an Emergency Family Income (IFE) was given to households with no pension or formal labour income between April and September 2020. The benefit was praised for its role in reducing poverty and providing for millions of households that had lost their income, but it was discontinued after September 2020 when most of the COVID19 restrictions had been lifted. In this paper, we run counter-factual dynamic simulations of what would have been the cost and distributive impact of maintaining the IFE after September 2020, and making it a permanent benefit. We show this would have represented initially a yearly additional expenditure of nearly 1.5% of GDP, with a downward trend. This is comparable to the cost of all family benefits. We also estimate that a permanent IFE would have significantly reduced income inequality. We thus show a permanent IFE would be financially feasible, although whether it is desirable or how it should be funded is open to debate.
This article contains 8 figures.
Figures
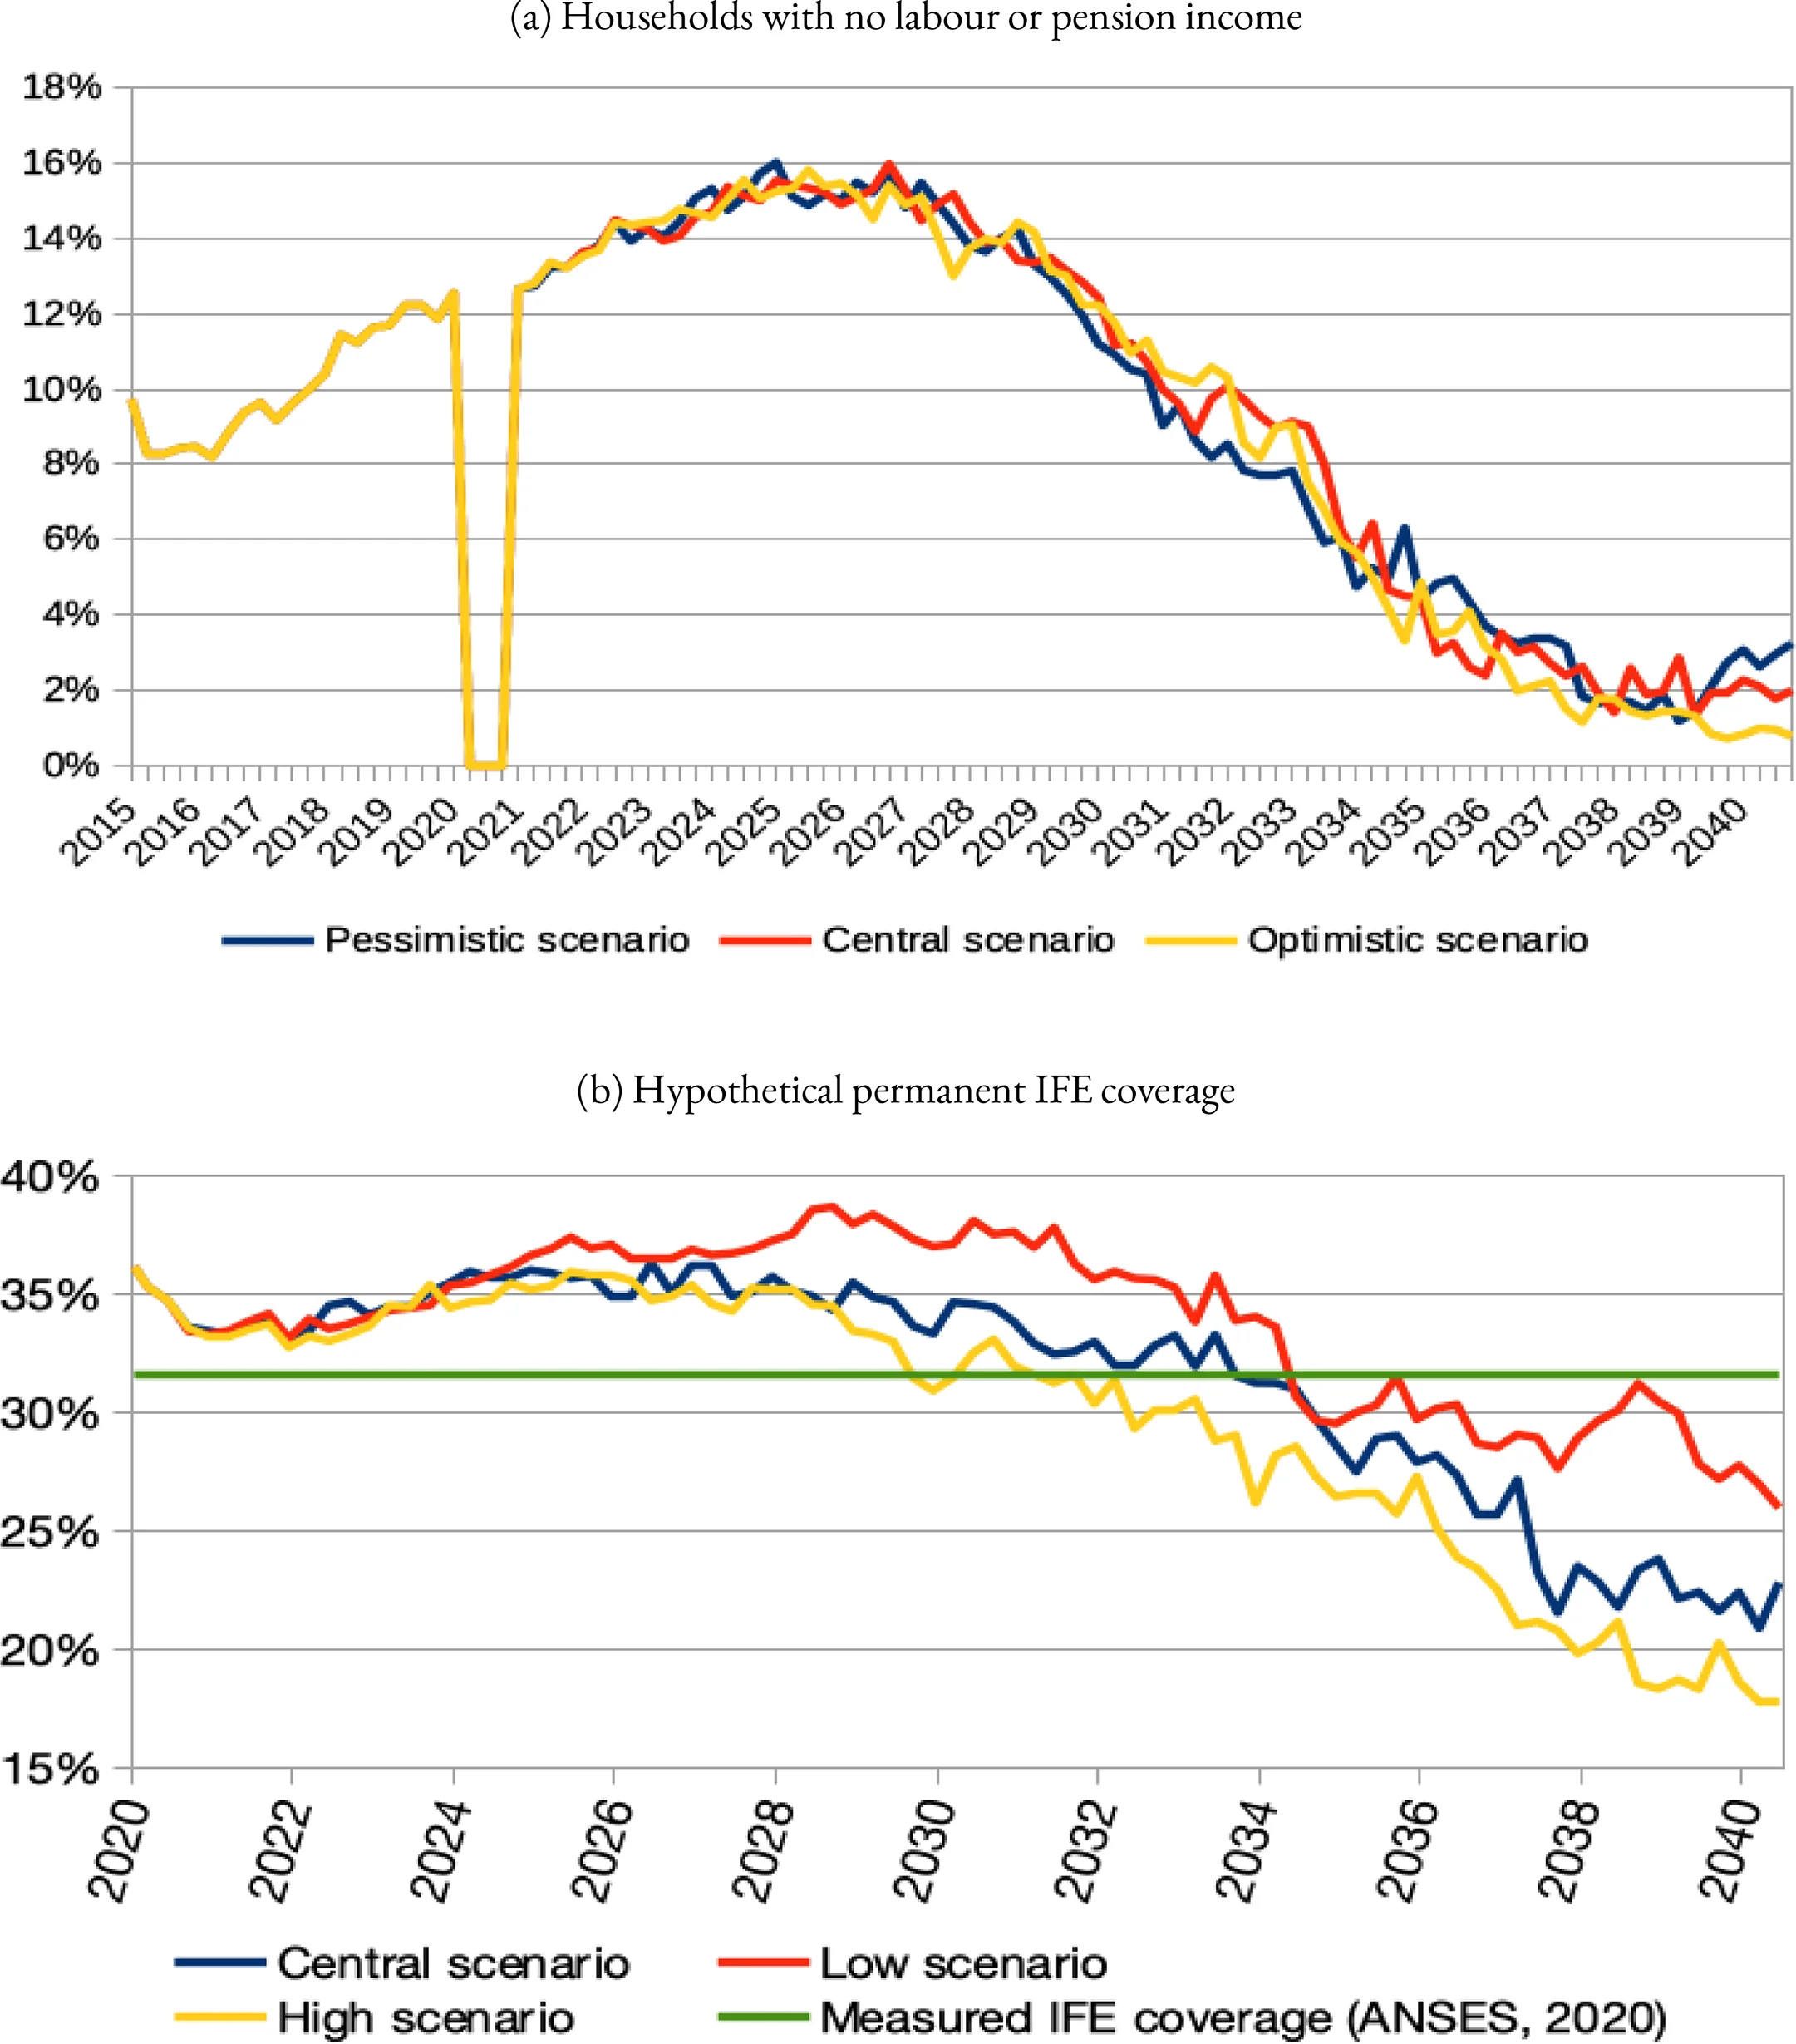
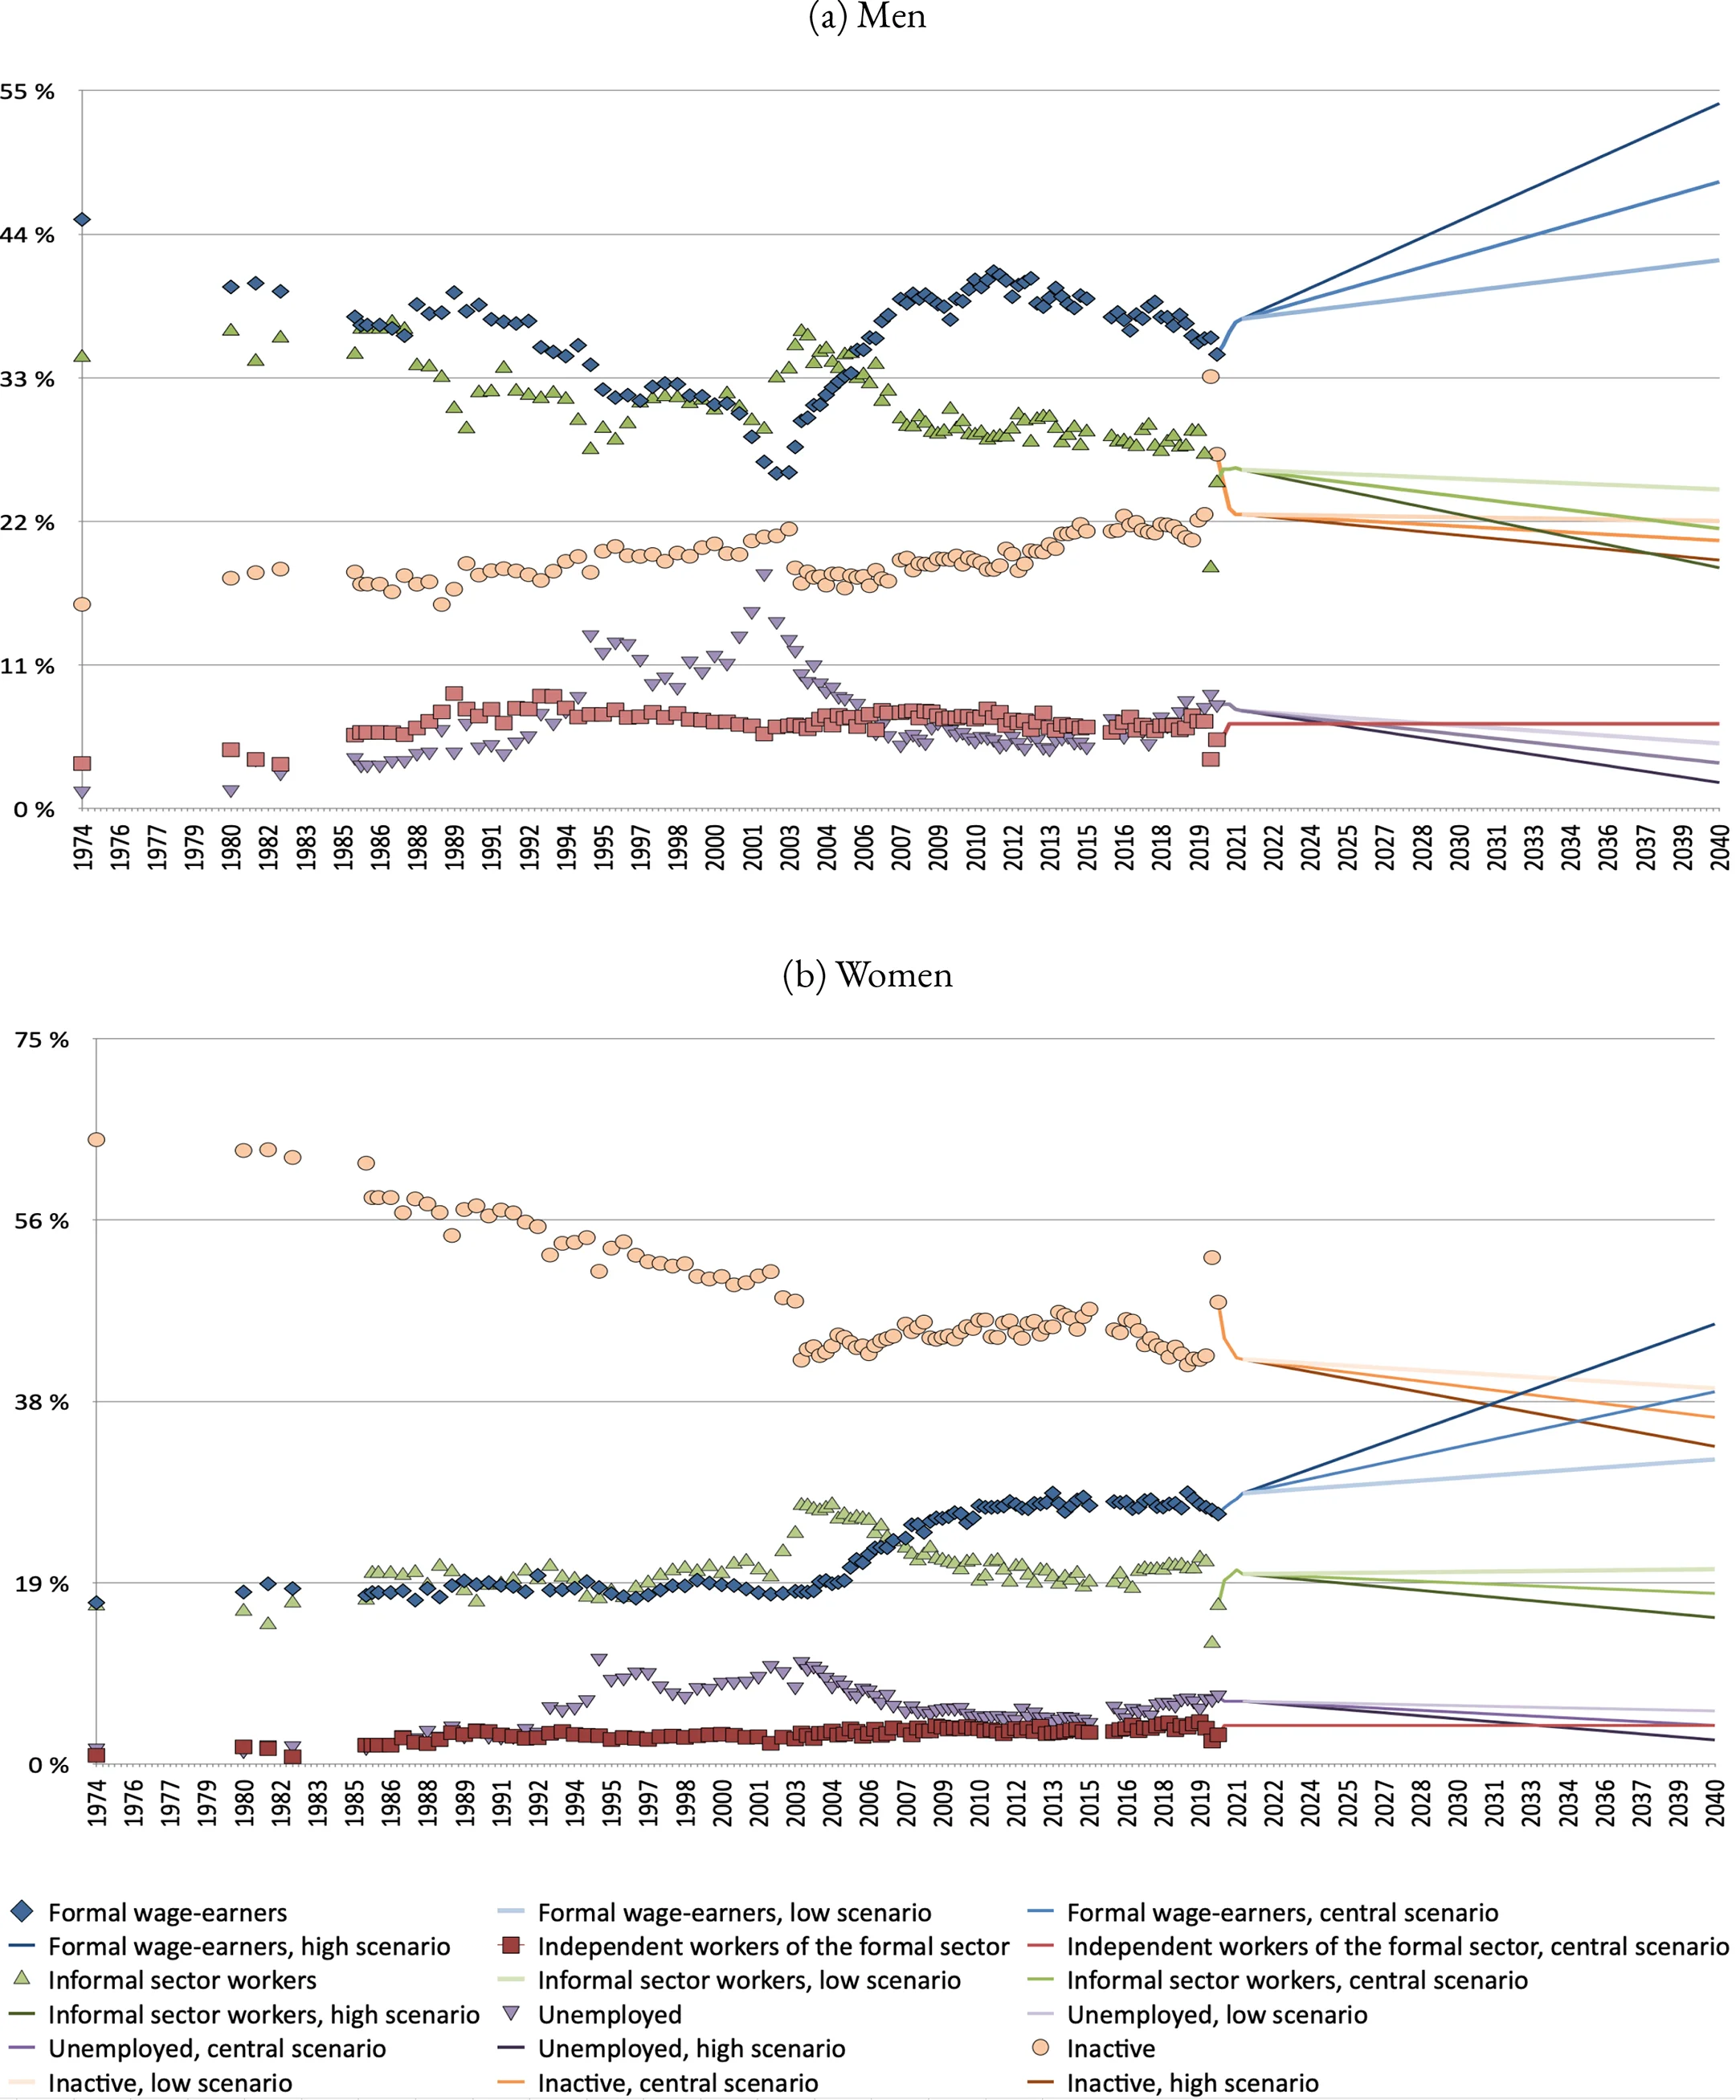
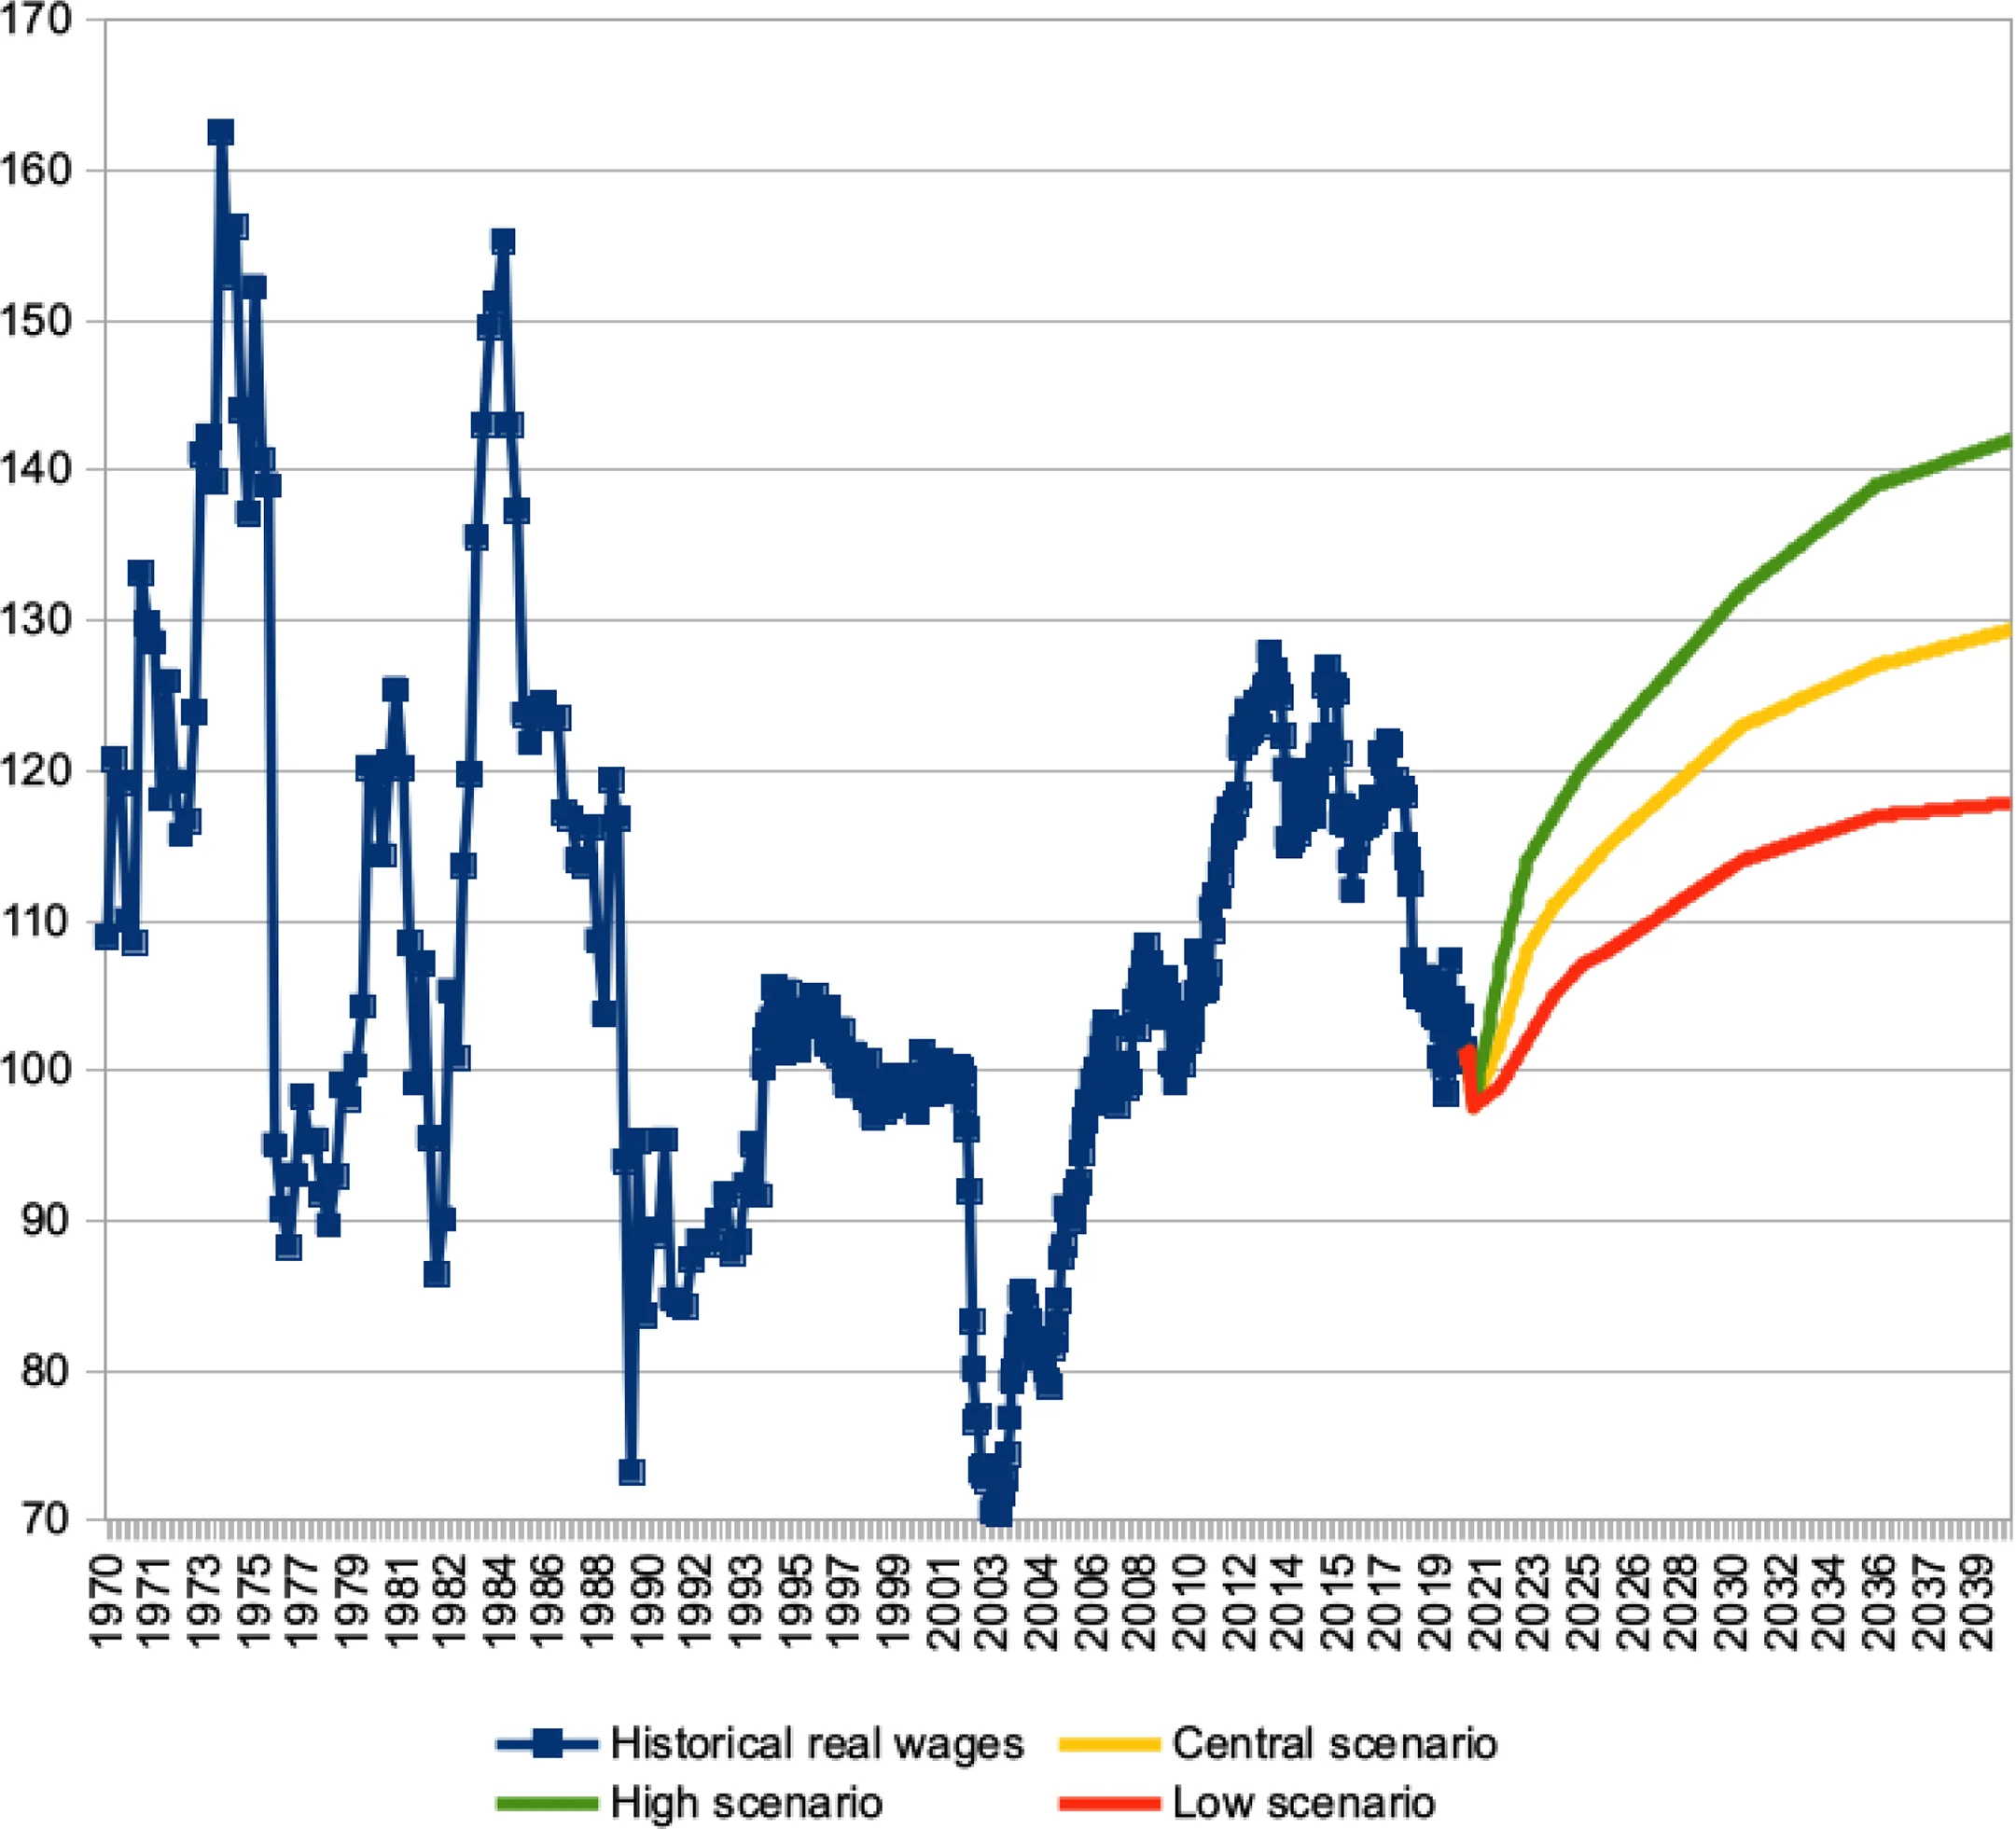
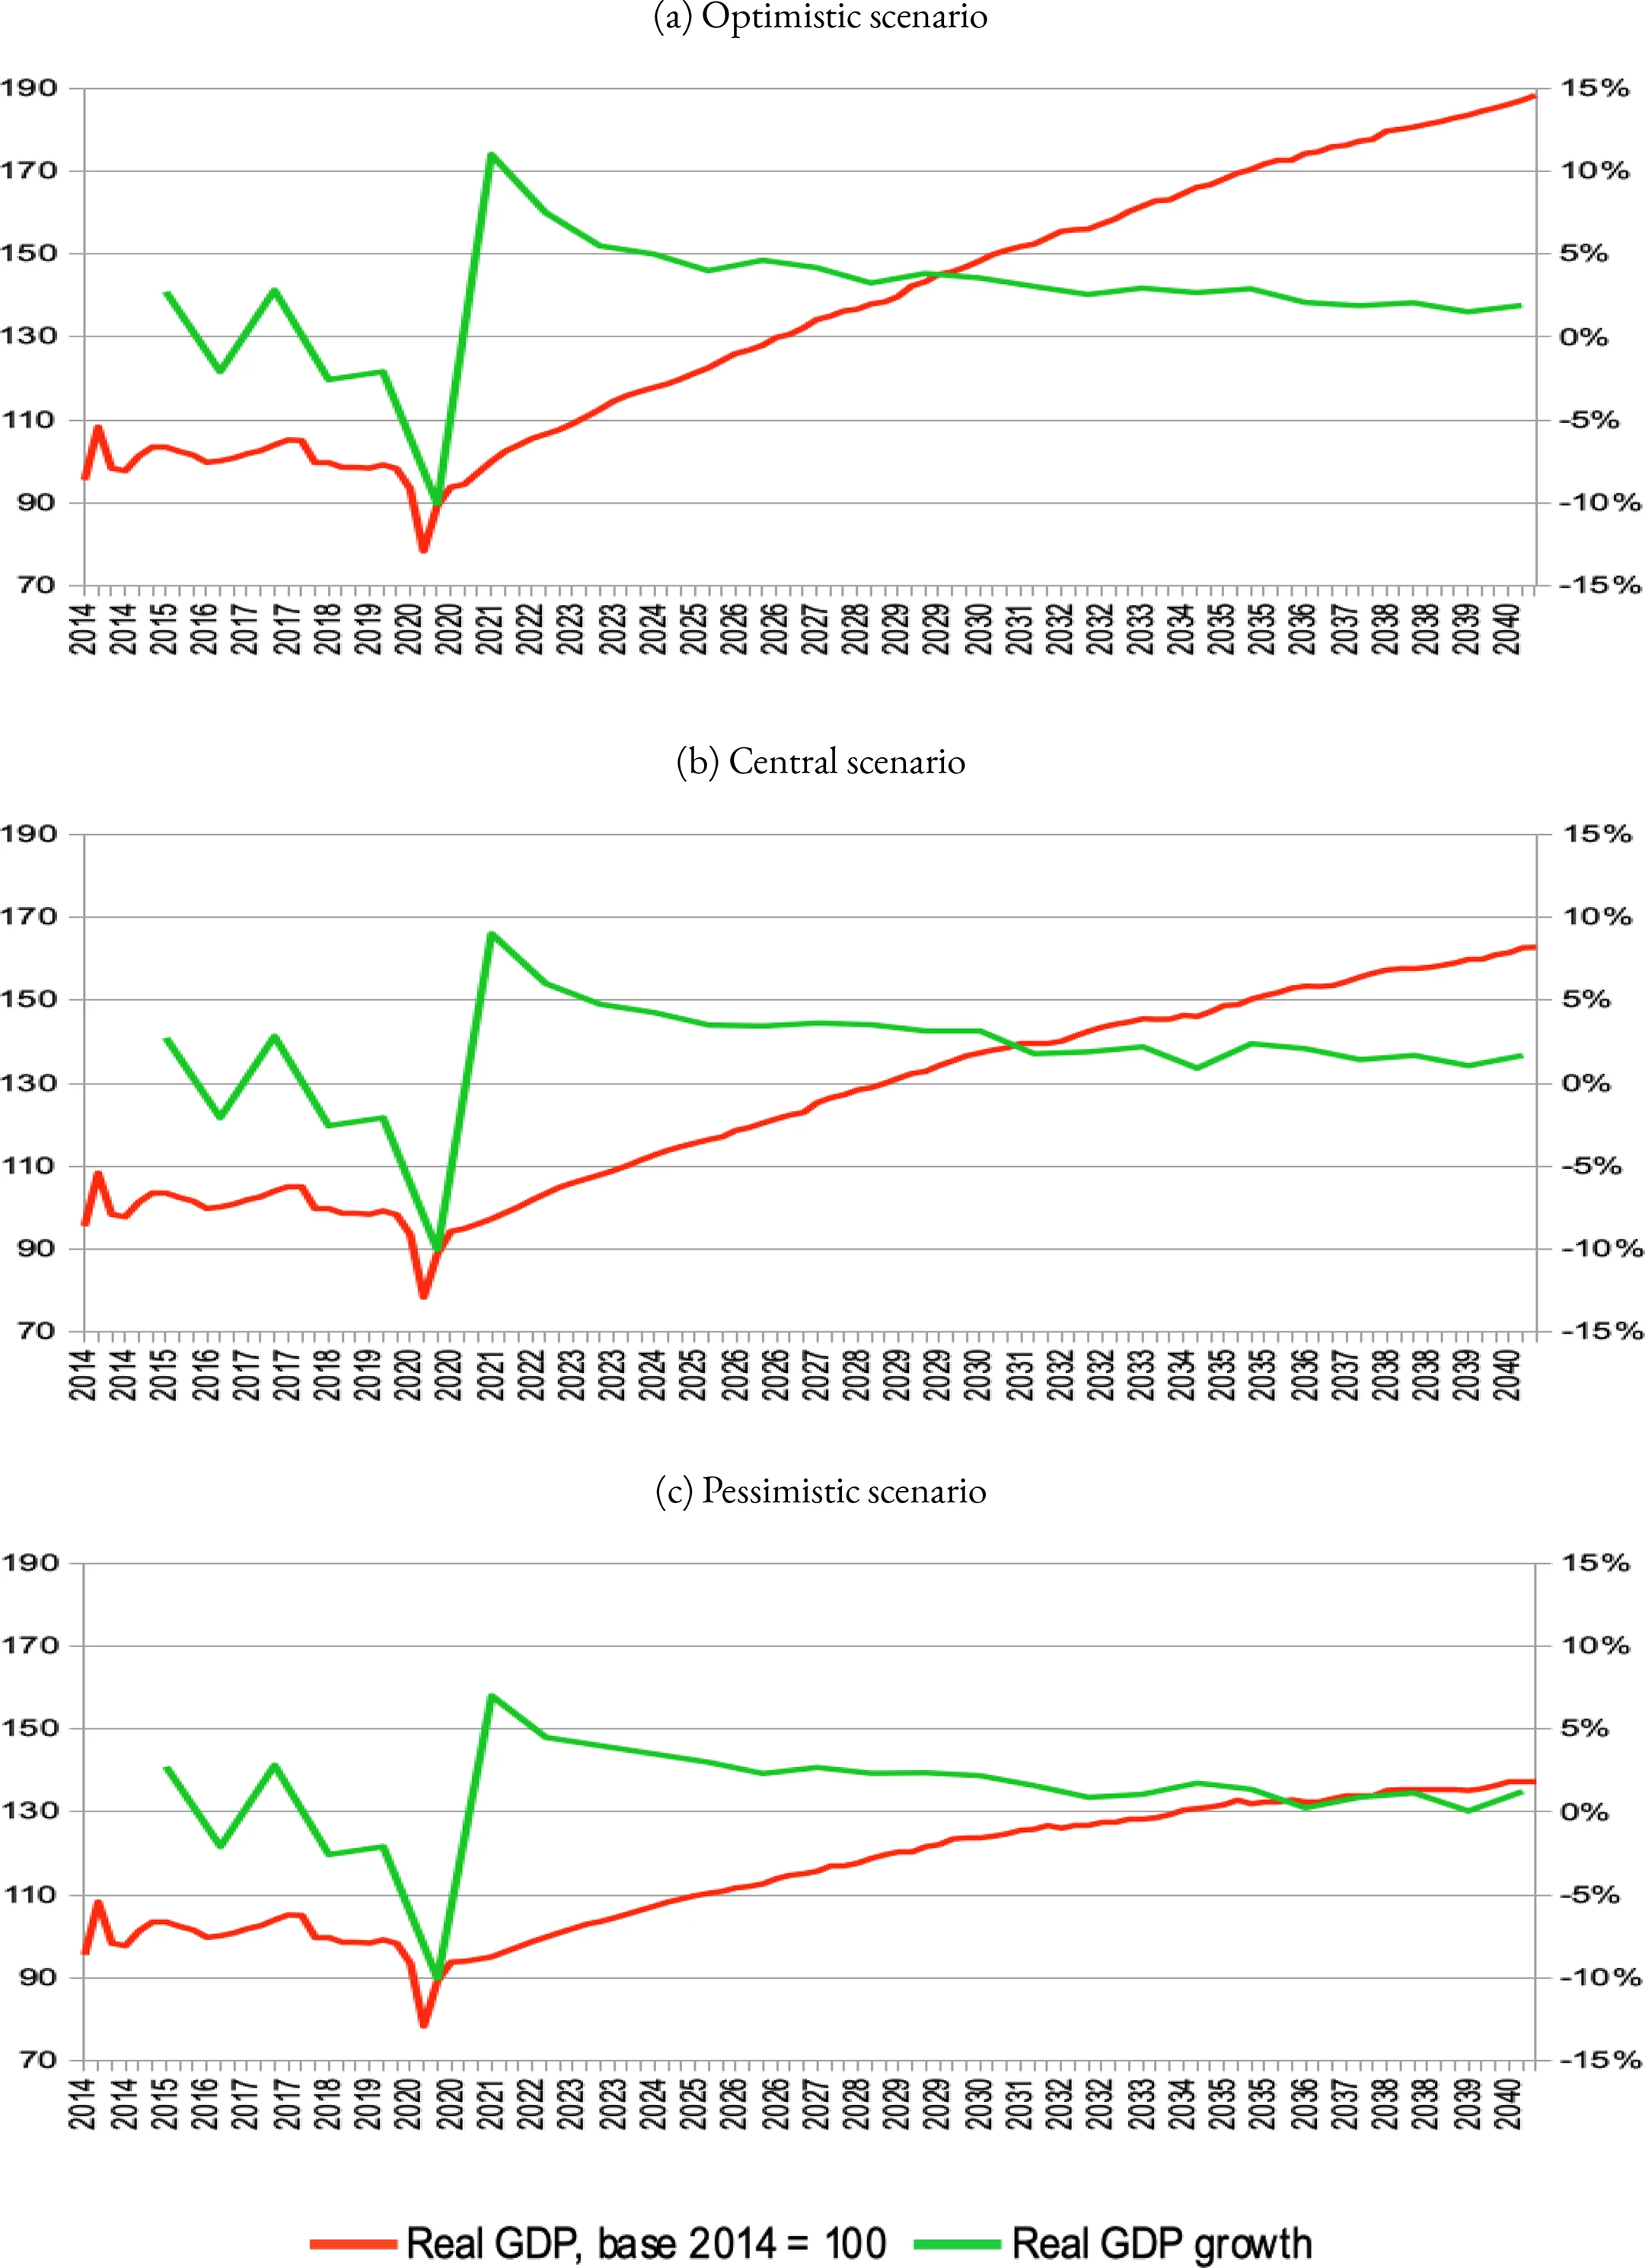
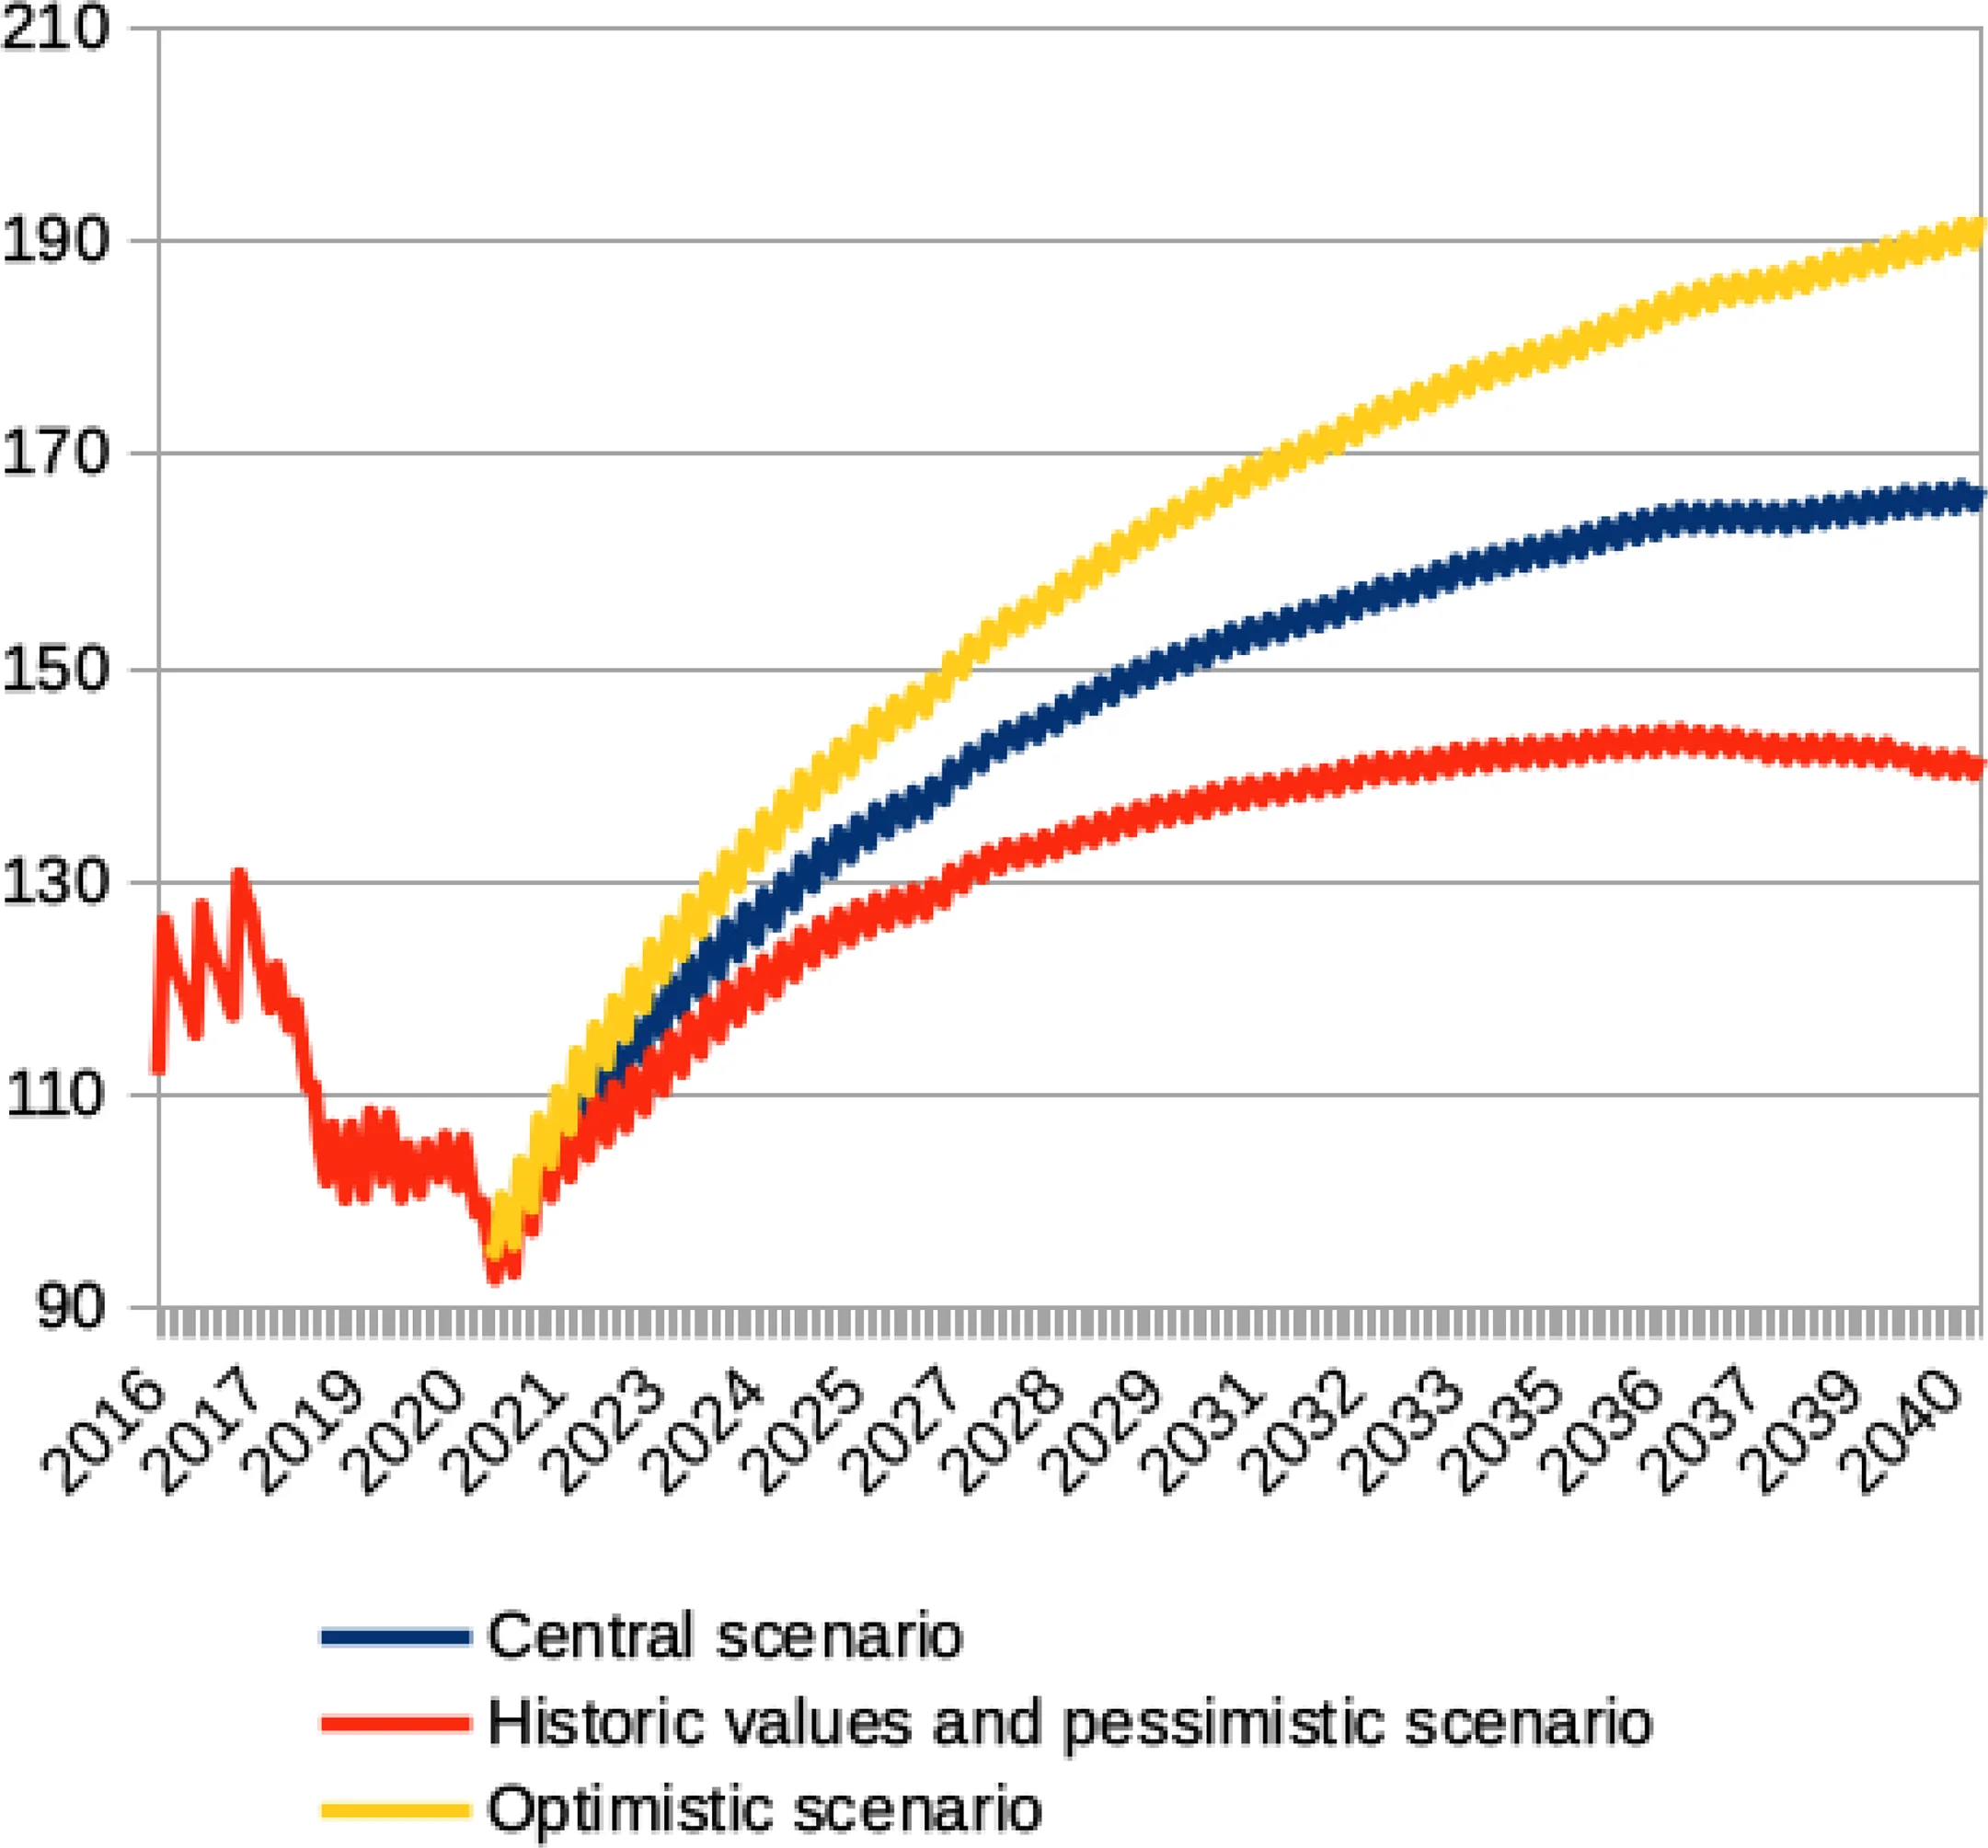
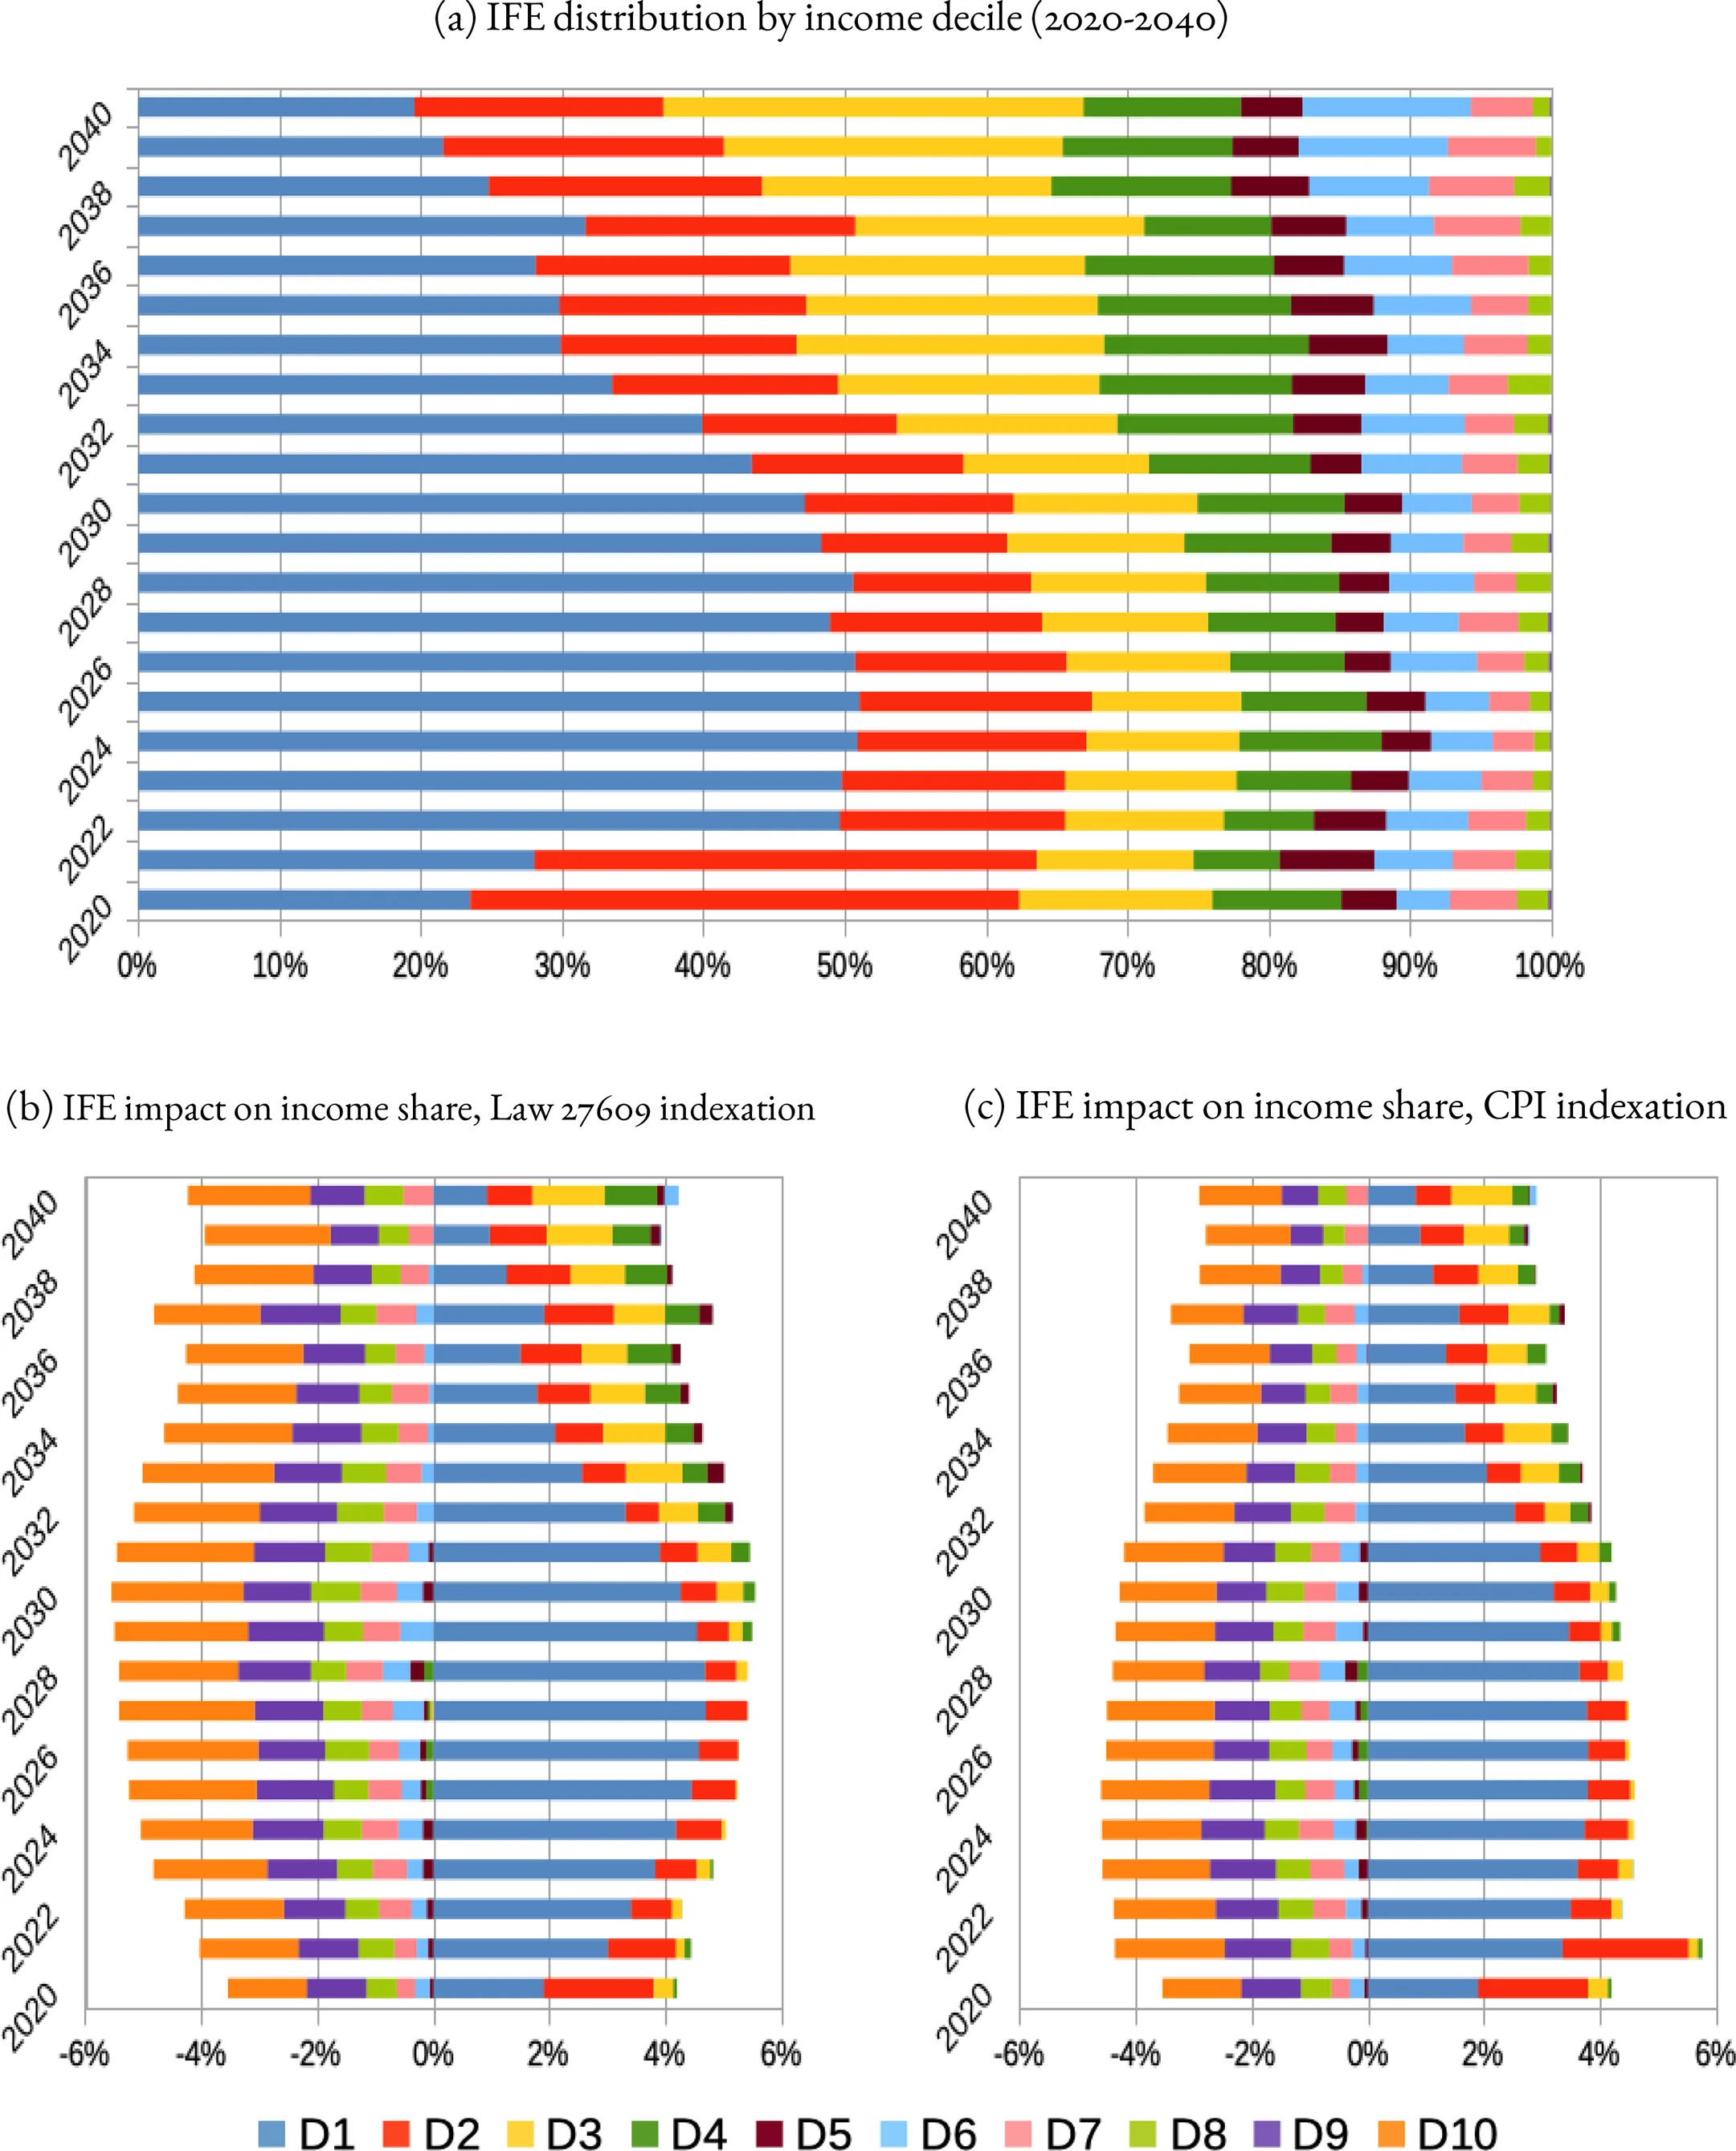
Figure 1. Households with no labour or pension income, and IFE coverage (2015-2040).Figure 2. Labour-market participation rates for people aged 16 to 69, past rates, and projected scenarios (1974-2040). Source: historical values taken from EPH survey (1974-2020).Figure 3. Quarterly real wage evolution, by scenario (1970-2040). Sources: for historical values, see Calcagno (2018). The base period is December 2006.Figure 4. Projected real GDP by economic scenario.Figure 5. Real pension mobility by economic scenario (2016-2040). Note: The base period is December 2020.Figure 6. Permanent IFE cost as a share of GDP, by scenario and indexation method (2020-2040).Figure 7. Gini index and top and bottom 10% share of income with and without a permanent IFE benefit (2020-2040). Note: Households with neither labour nor IFE income are excluded from this analysis. For the share of the top and bottom 10% in thetotal of a given income type however, the determination of the wealthiest and poorest households is always done with respect tototal income (labour, pension, IFE and family benefits). The Top and Bottom 10% shares are only computed in the centraleconomic scenario. Household income is equivalised following CEDLAS and The World Bank (2014), who adopted thecalibration established by Deaton and Zaidi (2002).Figure 8. Distributive impact of a permanent IFE by income decile (2020-2040). Note: Households with neither labour nor IFE income are excluded from this analysis. Income deciles are however always computed with respect to total income (labour, pension, IFE, and family benefits). The income deciles are only computed in the centraleconomic scenario. Household income is equivalised following CEDLAS and The World Bank (2014), who adopted thecalibration established by Deaton and Zaidi (2002). Reading example for Figure 8c in 2021, a permanent IFE indexed on pensionmobility Law 27690 would increase the first decile income share by 3.4 percentage points, when compared to its labour incomeparticipation.